

Magnite Keeps About Nine Cents of Each Ad Dollar, and Its Cut Isn't Going Up
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A sell-side ad exchange reports revenue after the publisher has been paid, so its stated top line already is its fee. That makes a flat percentage on rising volume look identical to share gains until the lines are read apart, and the September quarter reads them apart.
Magnite's contribution after traffic acquisition costs rose 20% to $200.6m, ahead of its own guide, with connected television up 39%; it raised full-year growth in that line to about 17% from 13-14%. Nexxen's equivalent line grew 8%, with the fast parts sitting in its demand-side platform and data licensing rather than its exchange.
The rally is not dollars migrating from buyers to sellers: The Trade Desk beat its own September guide and jumped about 21.8%. What rose at the exchanges is impressions cleared, and the rate charged on them did not move.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
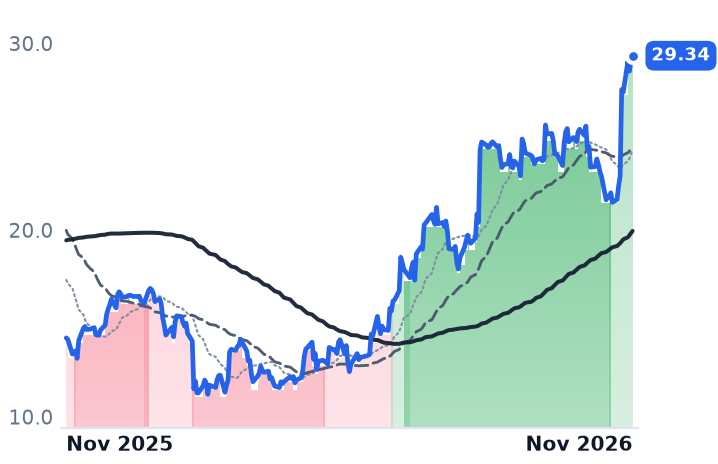
MGNI | Magnite | Ad Exchanges | 🟢 Cont. Bull | +20.9% | +106.2% |
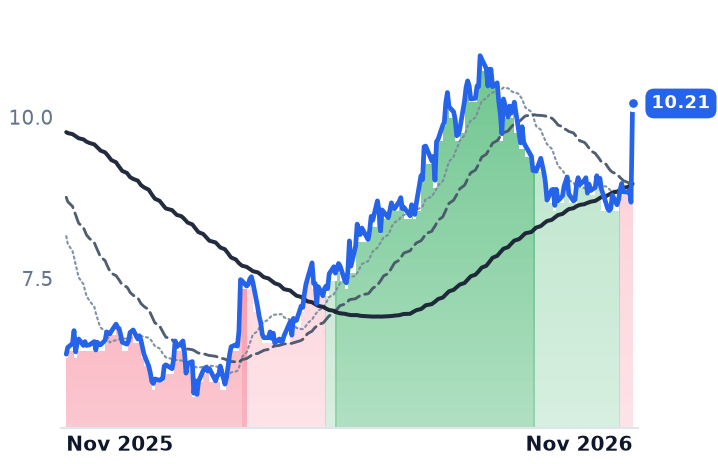
NEXN | Nexxen International | Ad Exchanges | 🔴 Cont. Bear | +15.8% | +61.4% |
| Compared against · context, not the story | |||||
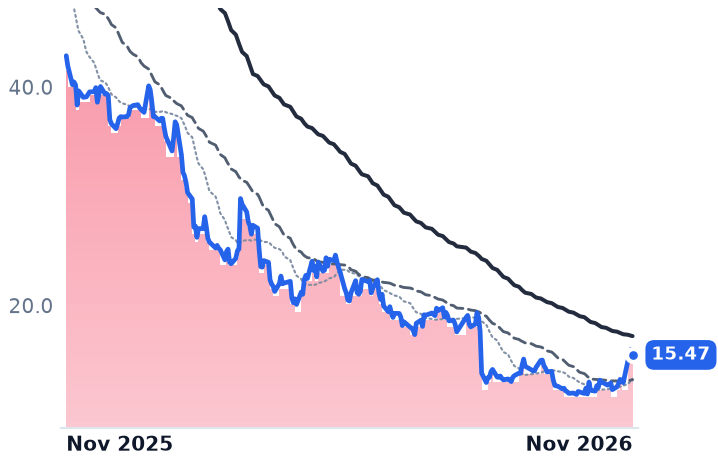
TTD | The Trade Desk | Programmatic Platforms | 🔴 Cont. Bear | +30.1% | −63.9% |
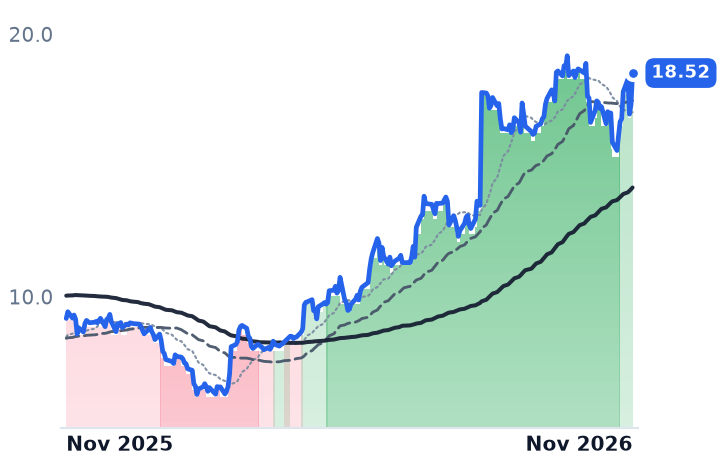
PUBM | PubMatic | Marketing, Advertising & Growth | 🟢 Cont. Bull | +5.0% | +101.9% |
CRTO | Criteo | Programmatic Platforms | 🔴 Cont. Bear | +15.6% | −20.7% |
DV | DoubleVerify | Marketing, Advertising & Growth | 🟢 Cont. Bull | +0.3% | +29.6% |
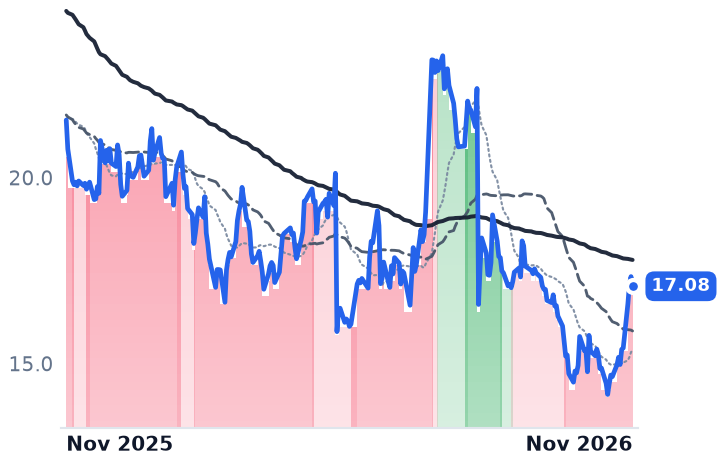
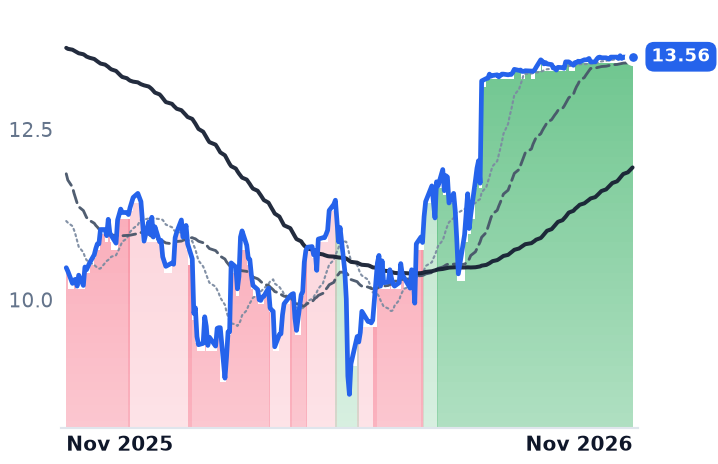
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MGNI | $4.2B | 23.1x | 25.8x | 5.5x | 5.4x | 8.2x | 8.1x | 21.6x | 5.5% |
NEXN | $581.5M | 43.8x | 9.5x | 1.5x | 1.5x | 2.0x | 1.9x | 5.4x | 15.3% |
TTD | $6.0B | 15.2x | 35.1x | 2.0x | 2.2x | 2.6x | 2.9x | 6.9x | 14.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PUBM | $803.5M | n/m | — | 2.8x | 2.6x | 4.3x | 4.0x | 25.5x | 5.8% |
CRTO | $877.3M | 8.6x | 4.8x | 0.5x | 0.8x | 0.9x | 1.6x | 3.1x | 20.2% |
DV | $2.1B | 36.2x | 30.7x | 2.7x | 2.5x | 3.3x | 3.2x | 12.4x | 7.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MGNI | Revenue | +16.7% | +10.6% | +12.2% |
| EPS | +29.7% | +20.2% | +17.9% | |
NEXN | Revenue | +11.5% | +9.1% | +8.2% |
| EPS | +12.3% | +15.9% | +9.0% | |
TTD | Revenue | −4.9% | −5.2% | +5.8% |
| EPS | −57.5% | −40.6% | +51.1% | |
PUBM | Revenue | +10.9% | +8.4% | +9.9% |
| EPS | −78.8% | −257.2% | +147.5% | |
CRTO | Revenue | −10.3% | +2.3% | +6.6% |
| EPS | −22.2% | +14.0% | +10.4% | |
DV | Revenue | +7.4% | +8.6% | +6.1% |
| EPS | +50.1% | +30.5% | +6.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Magnite, the independent exchange where owners of streaming channels, mobile apps and websites sell their advertising inventory, beat its September-quarter guidance and raised its year. The money it keeps after paying inventory partners grew 20% to $200.6m, above the $188m-$192m range it had guided, with connected television contributing $105.4m of it, up 39%.
The twelve-month run in sell-side exchange shares has been read as a transfer of dollars from the demand side of programmatic advertising to the supply side, as the buying platforms lose fee ground to walled gardens. That reading does not survive the week. The Trade Desk, the largest independent buying platform, reported September revenue of $736m, ahead of its own guide though down 0.5% from a year earlier, and the shares jumped about 21.8% on 9 November. Both sides of the pipe re-rated at once.
The reported top line is already the fee
Magnite's September revenue was $204.2m against that $200.6m of contribution ex-TAC, so traffic acquisition cost was roughly $3.6m, about 1.8% of revenue. Almost everything the company reports as revenue is the slice it retained. Its 10-Q says as much: revenue is a function of transactions, the price inventory clears at, and, where revenue is net, the take rate, which varies by publisher, channel and transaction type.
So size the pipe. Management describes more than $9bn of annualized ad spend crossing the platform; consensus carries 2026 revenue of $780.3m. Divide and the exchange retains roughly 9 cents of each advertiser dollar. The Trade Desk kept 21.6 cents in 2025, $2.896bn of revenue on $13.4bn of client spend. Barrett has said core take rates are stable and not under pressure, with mix and volume doing the work. What rose was the number of impressions cleared, not the percentage kept.
Costs that did not move
That is why operating leverage, and not price, shows up on the earnings line: operating income grew 101.8% year on year against 13.8% revenue growth. Operating expenses were flat at $154m while contribution grew a fifth, lifting adjusted EBITDA to $83m at a 42% margin against 34%. "Through this effort, we have reduced our cost per billion ad requests by over 50% year-over-year for streaming," chief financial officer Brian Gephart told investors on 4 November, describing on-premise capacity that held cloud costs roughly flat.
The volume is contracted, not spot. Magnite named a three-year extension with LG Ad Solutions including exclusive ad serving, HP TV+ taking it as primary video ad server, and Pinterest as primary supply platform for its global programmatic deals. OpenAI has tapped Magnite and PubMatic to fill unsold ChatGPT inventory. "We expect a long-term 3 to 5 year growth rate in CTV of approximately 25%," chief executive Michael Barrett said on the same call. The non-CTV book, open-web display and mobile, grew 5% to $95m.
Nexxen's growth is happening away from its exchange
Nexxen runs both ends, an exchange plus a self-service buying platform and a television data business. Its September quarter showed revenue of $102.9m and contribution ex-TAC of $100.3m, up 8%. Connected TV rose 39% to $34.1m and data products 73%, enterprise business through its own buying platform over 40% — while desktop fell 29%. Non-IFRS earnings of $0.32 a share missed the $0.35 consensus.
Guidance was reaffirmed rather than raised. "We continue to expect contribution ex-TAC in the range of $388 million to $402 million, representing approximately 12% year-over-year growth at the midpoint," chief financial officer Sagi Niri said on 12 November. Delivering 8% in the September quarter leaves the December quarter carrying the difference. The balance sheet gives room to wait: $152.9m of cash and no debt against a $581m market value, with no shares repurchased in the quarter as management keeps capacity for bolt-on deals.
One mechanism, two prices
Magnite trades at 21.6 times trailing EBITDA, down from 23.09x in mid-August even as the shares rose, because raised earnings outran the price. Its headline price-to-earnings pair is unusable; trailing net income contains a $123.1m one-off booked in the December quarter of 2025.
Nexxen is on 5.4 times trailing EBITDA and 9.5 times forward earnings, with a 15.3% trailing free cash flow yield. The decelerating contribution line supplies part of the reason. The Trade Desk, at 35.1 times forward earnings against 15.2x trailing, is priced for a recovery consensus does not yet model: revenue is forecast down 4.9% this year and 5.2% next.
Magnite is up 106.2% over twelve months, 20.2% of it in the session after the print. Nexxen is up 61.4% over the same year but down 4.9% over three months.
The results account for Magnite's move and only part of Nexxen's. Magnite is paid per impression on multi-year streamer supply it has locked up, and raised every line of its year; Nexxen's exchange is growing at single digits while its buying platform and data licensing run at 40% and 73%, which is a different business being re-rated under the same label. PubMatic, the third listed exchange, is up 101.9% over twelve months on 17% revenue growth and CTV above 30% — this is the whole shelf repricing streaming volume, and about 74% of connected-TV ad sales now transact programmatically, which is what makes the volume reach an exchange at all.
One thing the price is not paying for is a courtroom windfall. Judge Brinkema rejected the Justice Department's bid to break up Google's ad exchange on 2 September, ordering behavioral remedies instead; the final order is still pending, the implementation window unclear, and Magnite's 2027 framing excludes any benefit from it. The exchanges are being valued on streaming impressions they already clear, at a rate nobody has yet managed to raise.