

Air Products Cancelled Its Hydrogen Megaprojects and Refilled the Backlog With Chip Gases
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Air Products spent fiscal 2026 writing off the green-hydrogen complexes its previous management committed to, and the book it has rebuilt in their place is almost entirely semiconductor work. The industrial-gas backlog ended September at about $3.3bn, of which $2.6bn is electronics, after more than $2.0bn of electronics wins in twelve months.
The September quarter grew 12.3%, carried by nine percentage points of volume, and fiscal 2027 adjusted earnings are guided to $14.15-$14.50 a share, up 5-8%, with capital spending cut to $3.0-$3.5bn from a legacy run-rate near $5bn. Linde, whose electronics sales grew 15% organically last quarter, runs the larger book.
The prints support the business case at both. What they do not yet support at Air Products is cash: its trailing free-cash-flow yield is 0.68% against Linde's 2.10%, and the first positive free-cash year is still only a guide.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
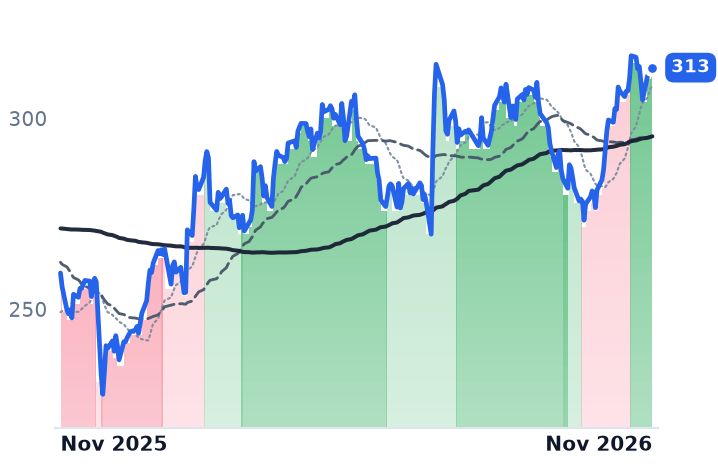
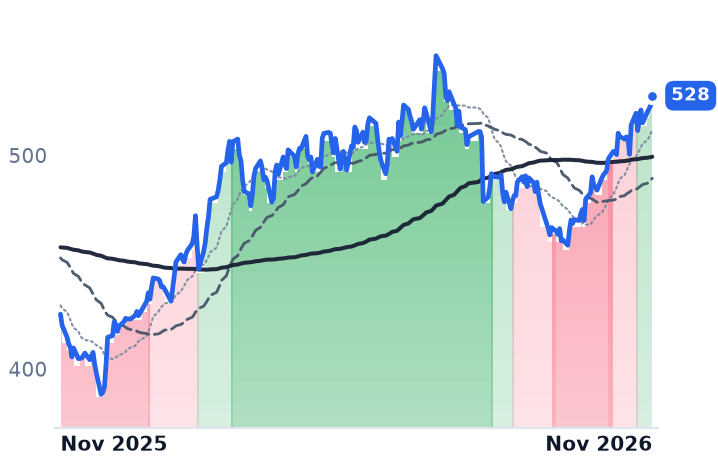
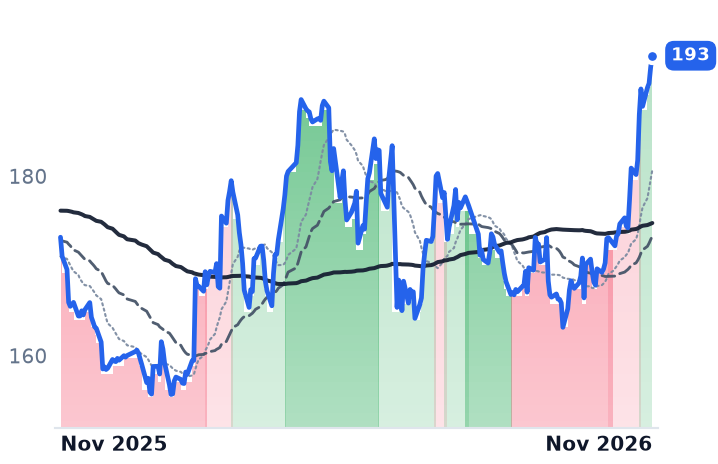
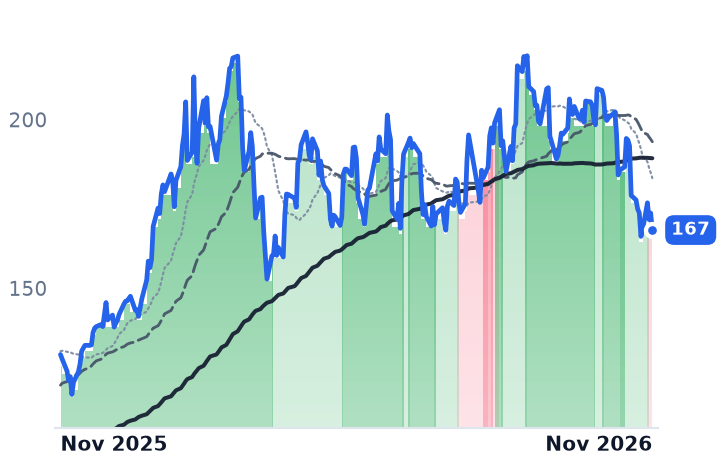
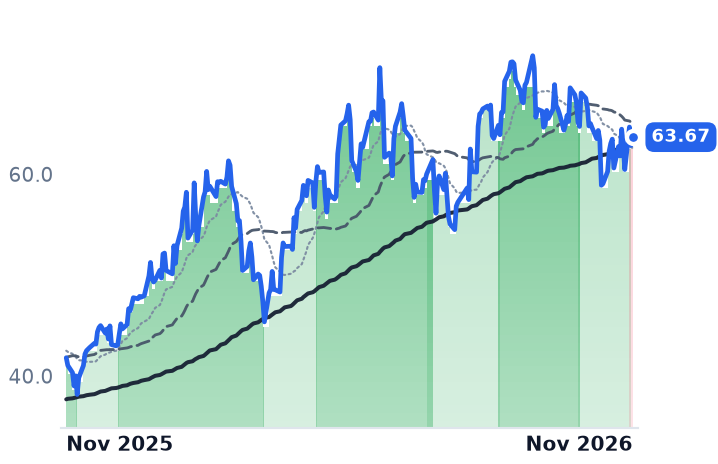
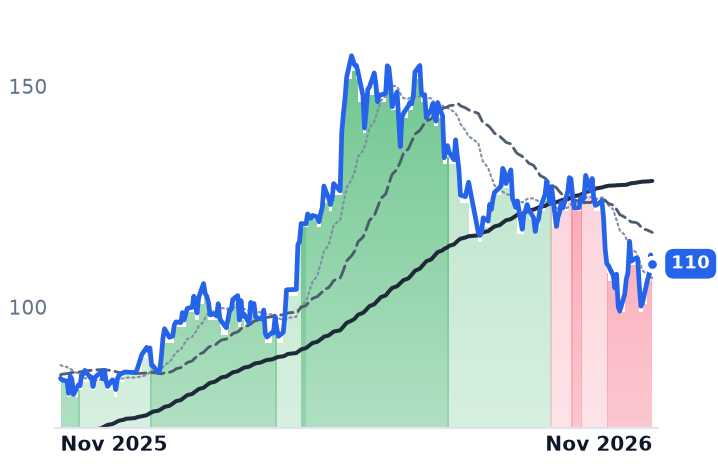
APD | Air Products and Chemicals | Industrial Gases | 🟢 Cont. Bull | +7.5% | +20.7% |
LIN | Linde | Industrial Gases | ⚠️ Emerging Bear | +7.3% | +24.0% |
| Compared against · context, not the story | |||||
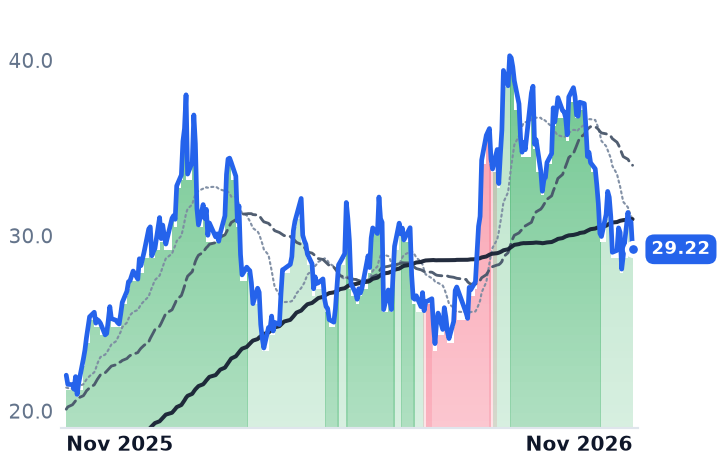
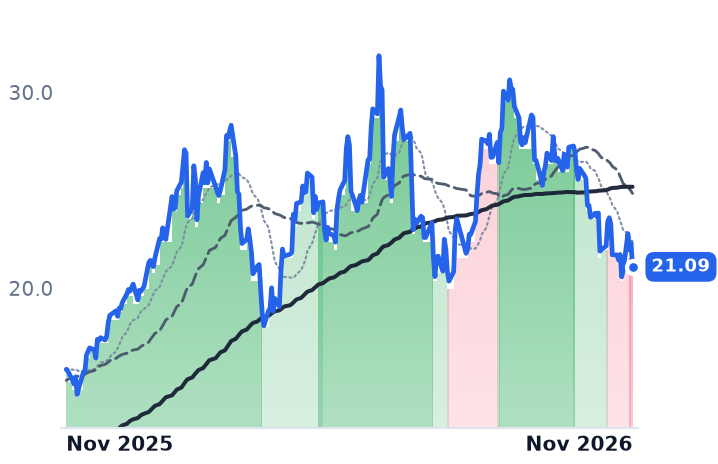
AI.PA | L'Air Liquide | Chemicals - Specialty | 🔴 Cont. Bear | +13.5% | +11.7% |
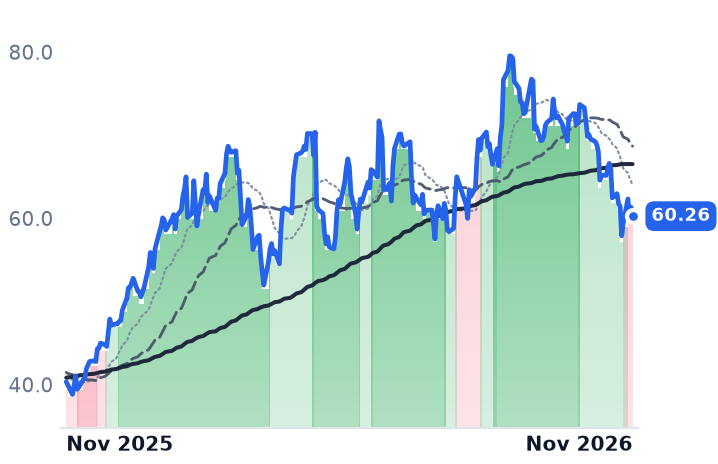
FCX | Freeport-McMoRan | Diversified Resources | 🟢 Cont. Bull | −13.7% | +49.3% |
SCCO | Southern Copper | Integrated Producers | 🟢 Cont. Bull | −16.7% | +28.3% |
TECK | Teck Resources | Diversified Resources | 🟢 Cont. Bull | −1.7% | +52.3% |
ERO | Ero Copper | Focused Miners | 🟢 Cont. Bull | −15.3% | +32.6% |
HBM | Hudbay Minerals | Polymetallic Miners | ⚠️ Emerging Bear | −13.0% | +33.0% |
PRY.MI | Prysmian S.p.A | Electrical Equipment & Parts | ⚠️ Emerging Bear | −3.0% | +30.9% |
NEX.PA | Nexans | Electrical Equipment & Parts | ⚠️ Emerging Bear | +0.9% | +6.3% |
NKT.CO | NKT A/S | Electrical Equipment & Parts | ⚠️ Emerging Bear | +2.7% | +20.9% |
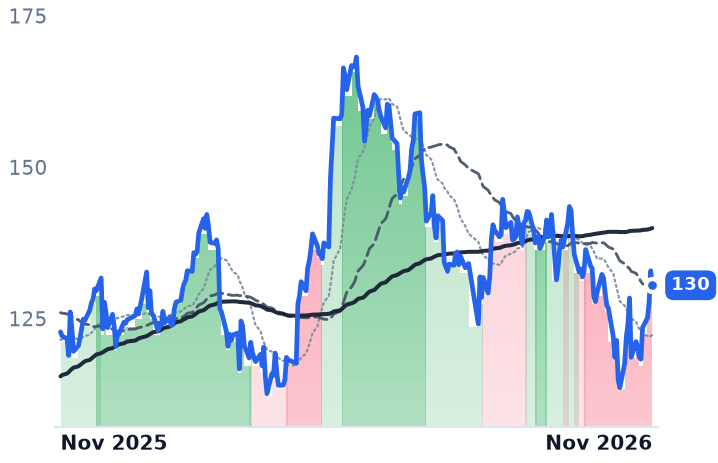
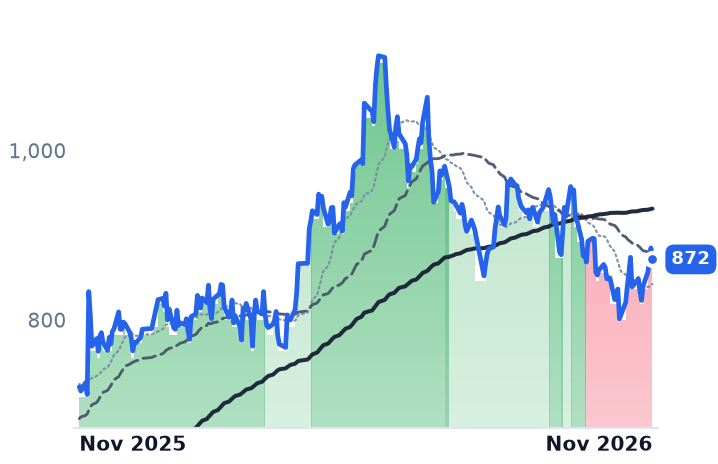
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APD | $70.4B | 132.3x | 22.0x | 5.4x | 5.2x | 17.2x | 16.4x | 113.1x | 0.7% |
LIN | $241.3B | 34.8x | 29.4x | 6.7x | 6.6x | 17.9x | 17.7x | 19.9x | 2.1% |
AI.PA | $118.9B | 32.0x | 28.8x | 4.4x | 4.2x | 12.1x | 11.6x | 16.1x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FCX | $103.6B | 35.5x | 24.2x | 4.0x | 3.5x | 14.9x | 13.1x | 12.2x | 5.7% |
SCCO | $171.5B | 30.1x | 26.8x | 10.9x | 10.1x | 17.4x | 16.2x | 17.6x | 3.5% |
TECK | $33.1B | 19.1x | 11.4x | 3.4x | 2.2x | 9.7x | 6.3x | 7.9x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ERO | $3.5B | 11.3x | 8.7x | 3.4x | 2.8x | 7.9x | 6.6x | 7.0x | 4.4% |
HBM | $13.4B | 17.8x | 20.0x | 5.4x | 4.6x | 13.8x | 11.7x | 8.1x | 1.8% |
PRY.MI | $37.9B | 27.3x | 27.0x | 1.8x | 1.7x | 6.7x | 6.3x | 15.3x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEX.PA | $6.0B | 71.4x | 18.4x | 0.8x | 0.7x | 7.8x | 7.5x | 12.4x | 4.7% |
NKT.CO | $47.7B | 23.9x | — | 1.8x | — | 8.8x | — | 20.4x | -10.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APD | Revenue | +6.1% | +6.2% | +6.7% |
| EPS | +12.2% | +6.9% | +7.9% | |
LIN | Revenue | +7.9% | +4.6% | +5.6% |
| EPS | +9.0% | +9.1% | +10.1% | |
AI.PA | Revenue | +5.0% | +4.6% | +4.6% |
| EPS | +11.3% | +11.2% | +10.0% | |
FCX | Revenue | +15.7% | +20.0% | +3.0% |
| EPS | +91.4% | +35.7% | +14.0% | |
SCCO | Revenue | +29.2% | −4.2% | −0.8% |
| EPS | +50.0% | −6.3% | −4.4% | |
TECK | Revenue | +41.4% | −0.1% | −15.4% |
| EPS | +128.4% | −14.7% | −25.6% | |
ERO | Revenue | +59.9% | +9.5% | −4.0% |
| EPS | +74.0% | +20.4% | −3.4% | |
HBM | Revenue | +31.3% | +16.1% | −1.2% |
| EPS | +78.4% | +29.2% | −2.1% | |
PRY.MI | Revenue | +15.2% | +13.5% | +8.0% |
| EPS | +17.8% | +30.6% | +18.9% | |
NEX.PA | Revenue | +13.8% | +7.9% | +8.9% |
| EPS | −10.7% | +27.8% | +18.8% | |
NKT.CO | Revenue | +3.6% | +17.6% | +13.6% |
| EPS | +3.3% | +32.1% | +44.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Air Products closed its fiscal year with a project backlog that is now mostly semiconductor work, the result of a deliberate swap. The Allentown, Pennsylvania supplier of oxygen, nitrogen, hydrogen, helium and ultra-high-purity electronics gases spent the year cancelling the green-hydrogen complexes its prior management had committed capital to, and signing on-site plants next to chip fabs in their place.
That swap matters beyond the write-off, because the whole "AI needs physical inputs" complex is bought as one trade and paid on incompatible terms. In the first week of November, after US midterm ballot measures curtailing data-center construction, the Nasdaq 100 fell 4.5% and copper repriced with it: Southern Copper is down 19.1% over 30 days and Freeport-McMoRan 16.1%. Air Products rose 9.4% over the same stretch and Linde 7.5%. Metal reprices on a demand forecast; a gas plant built inside a customer's fenceline is paid on a signed contract, with power and feedstock rebilled.
Nine of the twelve points were volume
September-quarter revenue was $3.556bn, up 12.3% and the fastest growth of the fiscal year, against 4.6% in the June quarter. Nine percentage points came from volume, with one point each from price, energy cost pass-through and currency, and quarterly adjusted earnings of $3.61 a share rose 6%. Full-year revenue reached $12.991bn, up 7.9%, with gross profit up 8.5%.
The backlog behind that is where the company has changed. Industrial-gas projects under contract stood at about $3.3bn at year-end, up from $3.0bn three months earlier, with $2.6bn of it electronics and space after more than $2.0bn of electronics wins in twelve months. The pipeline still under evaluation exceeds $4.0bn.
What $2.9bn of cancelled hydrogen bought
The cost of getting there sits in one quarter. Air Products said on 30 June 2026 it would not proceed with the Louisiana Clean Energy Complex, taking a pre-tax charge not exceeding $2.9bn; the June quarter carries a GAAP operating loss of $2.097bn, which is why the full year shows an operating loss of $40.9m on growing gross profit, and why a trailing price/earnings ratio of 132x says nothing about the business. A planned green liquid hydrogen plant at Massena, New York was cancelled too, the Jiutai gasification stake was sold for more than $250m, and NEOM in Saudi Arabia is construction-complete and entering commissioning, with full operation expected in the second half of 2027 and no material contribution to fiscal 2027.
Capital spending is guided to $3.0-$3.5bn next year, against a legacy run-rate near $5bn, with over $1bn of it going to traditional industrial-gas projects. "The effort that we did as a company to reduce our CapEx was one of the things that I'm most proud of our performance in '26," chief executive Eduardo Menezes told investors on 5 November, adding that "our goal long term is to have a backlog in the range of $4 billion to $4.5 billion."
The 2027 guide is slower, and says why
Fiscal 2027 adjusted earnings are guided to $14.15-$14.50 a share, up 5-8% against the 12% just delivered, built on roughly 2% base volume growth plus 3% from new assets starting up. Management disclosed the offsets: equity affiliate income flat after a 14% gain, a tax rate rising to 19%, and higher interest expense on projects no longer capitalized, together about two points of earnings. Chief financial officer Melissa Schaeffer flagged a further drag from a switch to average-cost inventory accounting for helium: "this will create a modest headwind in FY '27...but it's not a cash headwind. Purely an accounting." No buyback is assumed.
Linde is doing the same thing on a bigger book
The fab demand is visible at the larger rival. Linde's September quarter brought revenue of $9.404bn, up 9.2%, and record adjusted earnings of $4.59 a share with electronics up 15%, on a backlog of $11bn of which $7.9bn is sale-of-gas, and roughly $2bn of electronics plants under construction in the US, Korea and China with staggered start-ups over two to three years. Its own quarter was not clean: GAAP operating income fell 8.2% on a $425m restructuring charge, and chief executive Sanjiv Lamba said of Europe on 29 October, "There is absolutely no catalyst."
The discount is paid for in cash
Air Products trades at 22.0x forward earnings and 16.4x forward gross profit, against Linde at 29.4x and 17.7x. The relative position has flipped: in August the same gross-profit meter read 16.8x for Air Products against Linde's 13.9x, a 21% premium; it now reads 17.2x against 17.9x. Both multiples have expanded since early October, when Air Products stood at 19.2x forward and Linde at 26.8x, with estimates little changed.
The cash explains the gap. Air Products' trailing free-cash-flow yield is 0.68% against Linde's 2.10%, and the first positive free-cash year is a fiscal 2027 guide, not a result.
So the results account for the twelve-month advance and most of the recent one: volume-led growth, a contracted book growing toward management's own target, a 15% headcount reduction since fiscal 2024 that captured $95m of savings, and capital spending cut by roughly a third. What they do not account for is the flat reaction to the print itself, when the shares fell 1.3% on 5 November and 1.5% the next day before recovering by 12 November. The likelier reading is that the market is still pricing the conversion of that backlog, and waiting for the cash to show up where the contracts say it should. Management, for its part, expects data-center demand to keep semiconductor requirements rising for the next five to six years.
What Air Products cannot do is set the pace. Major customer award decisions on its electronics and space pipeline are expected within twelve months, constrained by regulatory hurdles and labor availability. Those decisions belong to the fab owners.