

CrowdStrike Grew Faster Four Quarters Running and Is Still Dearer Than It Was in July
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
CrowdStrike has changed what it tells investors about Falcon Flex, the pooled commitment through which it now sells most new business: the committed-dollar total it once headlined is gone, replaced by the recurring revenue it has already recognized from Flex adopters. The pipeline of signed-but-unconverted dollars is no longer measurable from outside the company.
What is still measurable argues the book is in good order. Contracted revenue not yet recognized stood at $10.7bn at the end of July against $7.2bn a year earlier, and the quarter added a record $332.8m of net new annual recurring revenue. The month's selling was sector-wide, and after it the shares still fetch 51.9x forward gross profit, roughly twice what Palo Alto commands. The markdown repriced growth; it did not catch a conversion problem.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
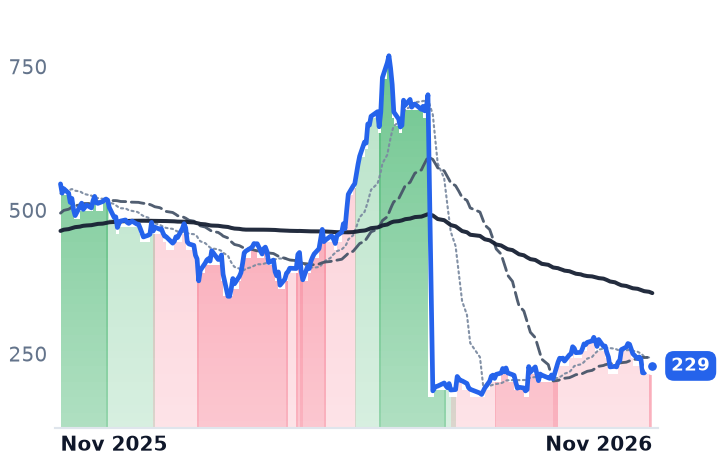
CRWD | CrowdStrike | Cybersecurity & Threat Protection | 🔴 Cont. Bear | −13.1% | −58.0% |
| Compared against · context, not the story | |||||
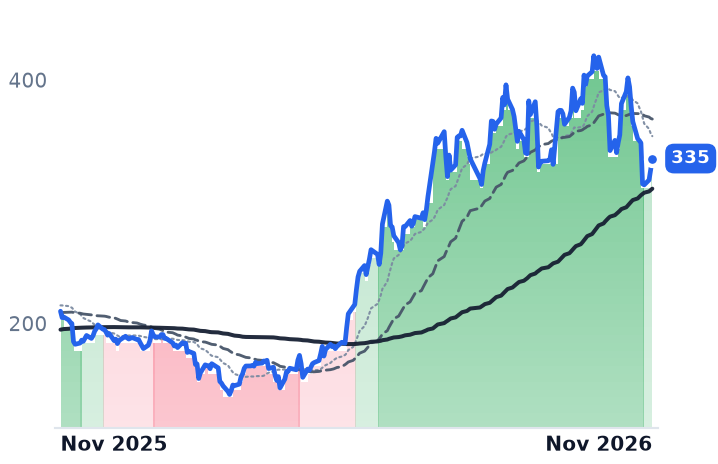
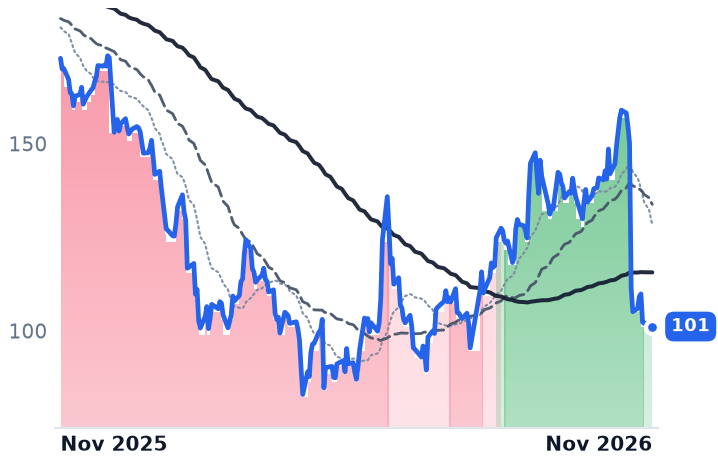
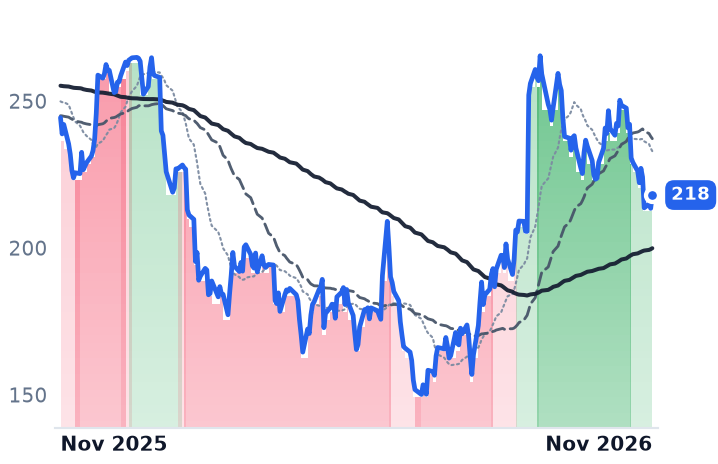
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🟢 Cont. Bull | −16.7% | +59.7% |
FTNT | Fortinet | Cybersecurity & Threat Protection | 🟢 Cont. Bull | −33.4% | +55.3% |
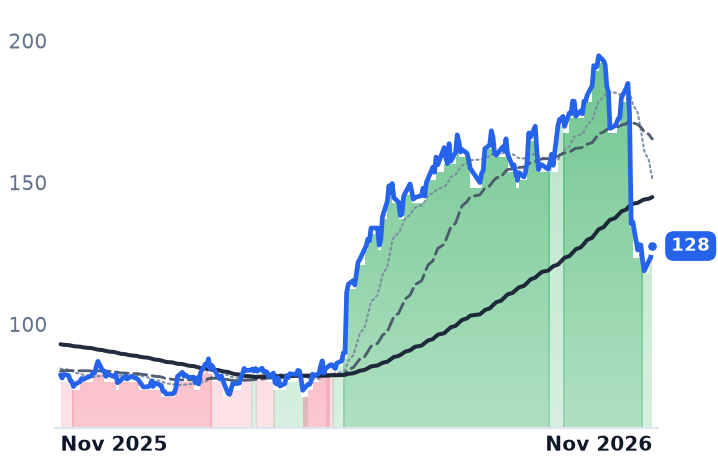
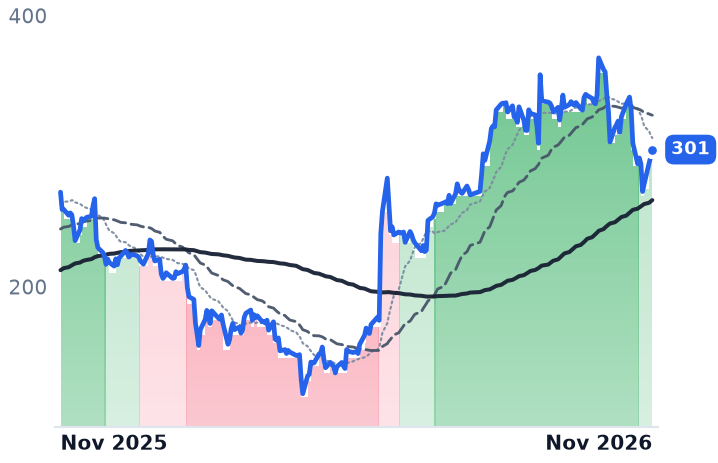
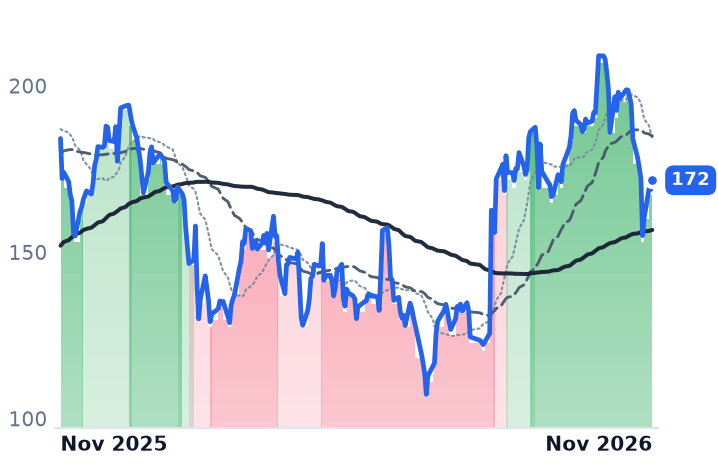
ZS | Zscaler | Cybersecurity & Threat Protection | 🟢 Cont. Bull | −16.3% | −38.9% |
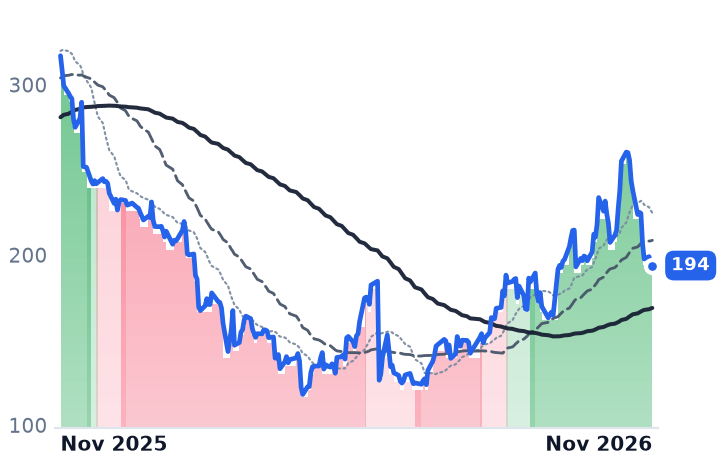
NOW | ServiceNow | Sales, Service & Customer Management | 🟢 Cont. Bull | −29.2% | −41.5% |
CRM | Salesforce | Sales, Service & Customer Management | 🌱 Emerging Bull | −9.5% | −10.8% |
SNOW | Snowflake | Data, Analytics & Intelligence | 🟢 Cont. Bull | −16.0% | +11.6% |
PLTR | Palantir Technologies | Data Platforms & Databases | 🟢 Cont. Bull | −17.5% | −6.8% |
OKTA | Okta | Identity & Access Management | 🟢 Cont. Bull | −19.4% | +118.0% |
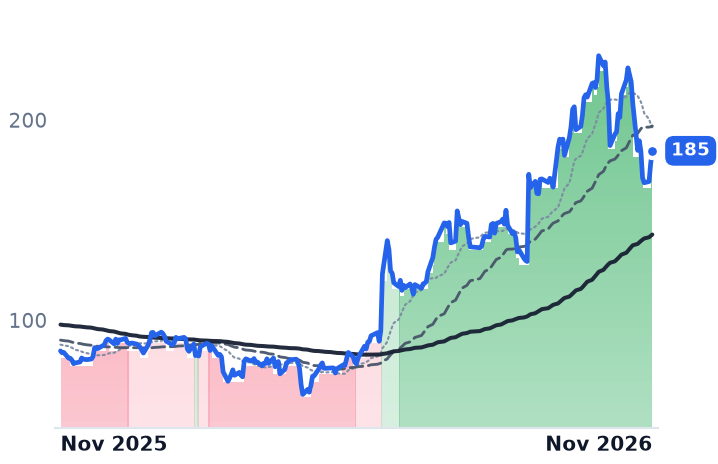
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRWD | $234.5B | — | 182.7x | 43.5x | 39.0x | 57.8x | 51.9x | 527.3x | 0.7% |
PANW | $256.9B | 682.3x | 75.0x | 22.4x | 18.1x | 31.8x | 25.8x | 166.8x | 1.6% |
FTNT | $94.1B | 41.3x | 36.0x | 11.9x | 11.5x | 15.0x | 14.4x | 30.7x | 3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ZS | $31.6B | n/m | 39.7x | 9.4x | 8.0x | 12.3x | 10.5x | 174.4x | 2.5% |
NOW | $105.8B | 72.8x | 25.8x | 6.9x | 6.5x | 9.4x | 8.9x | 32.6x | 4.5% |
CRM | $175.8B | 19.4x | 12.8x | 4.0x | 3.8x | 5.2x | 4.9x | 12.5x | 8.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SNOW | $97.3B | n/m | 124.4x | 17.9x | 15.4x | 26.7x | 23.0x | n/m | 1.2% |
PLTR | $394.9B | 136.5x | 108.2x | 64.2x | 48.6x | 75.7x | 57.3x | 126.8x | 0.9% |
OKTA | $28.2B | 99.8x | 42.9x | 9.2x | 8.7x | 11.7x | 11.2x | 66.7x | 3.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CRWD | Revenue | +22.2% | +25.1% | +22.9% |
| EPS | −1.2% | +35.0% | +27.9% | |
PANW | Revenue | +24.3% | +24.0% | +14.3% |
| EPS | +15.5% | +10.7% | +16.1% | |
FTNT | Revenue | +21.0% | +11.4% | +11.0% |
| EPS | +32.3% | +9.2% | +12.8% | |
ZS | Revenue | +25.2% | +17.9% | +16.3% |
| EPS | +29.2% | +18.3% | +14.8% | |
NOW | Revenue | +22.6% | +18.5% | +18.1% |
| EPS | +13.5% | +21.6% | +22.2% | |
CRM | Revenue | +9.3% | +11.5% | +9.9% |
| EPS | +17.4% | +42.3% | −4.1% | |
SNOW | Revenue | +29.4% | +35.7% | +29.0% |
| EPS | +72.3% | +82.9% | +36.4% | |
PLTR | Revenue | +86.1% | +49.3% | +48.2% |
| EPS | +122.1% | +42.4% | +50.3% | |
OKTA | Revenue | +12.0% | +10.8% | +9.9% |
| EPS | +24.3% | +14.1% | +10.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
CrowdStrike sells most of its new business through a pooled commitment called Falcon Flex: an enterprise signs up for a multi-year dollar amount, then draws modules against it later as it needs them, from endpoint and identity protection to cloud workload defense and log management. Earlier in this cycle the company told investors how large that committed pool had become. It no longer does.
The intuitive reading of a de-rating at a company that signs commitments before it recognizes revenue is that the commitments have stopped converting. The filings argue the reverse. Remaining performance obligations, the contracted revenue CrowdStrike has booked but not yet earned, reached $10.7bn at 31 July 2026 against $7.2bn a year earlier. Revenue over the same span grew 26%. About 46% of that balance, roughly $4.9bn, is due to be recognized within twelve months.
Four quarters of going faster, not slower
Quarterly revenue growth has accelerated in each of the last four periods, from 22.2% to 23.3%, then 25.6% and 25.8%, on revenue of $1.471bn in the July quarter. Annual recurring revenue reached $5.84bn, up 25%, with a record $332.8m of net new ARR added in the quarter, itself up 51%. The full-year outlook for net new ARR was raised by 630 basis points, to a $1.350bn-$1.359bn range implying about 34% growth. Gross margin widened to 74.6% from 73.5%.
"Q2 was the best quarter in CrowdStrike's history," founder and chief executive George Kurtz said in the 26 August 2026 release. "Delivering record Falcon Flex results, record net new ARR, and accelerating growth—the Falcon is soaring."
What a Flex customer's bill does after signing
The conversion ladder is disclosed as uplift rather than dollars. Moving a standard subscription onto Flex lifts that account's ending ARR by more than 40% on average; a first re-commitment adds a further 25%; accounts that have re-committed at least twice carry ARR 53% above where their first Flex began. By the company's September investor briefing about 630 accounts had re-committed, six times the prior year, with the first re-commitment typically arriving around eight months into a multi-year contract. More than 935 Flex accounts were added in the July quarter alone, more than the prior three quarters combined.
That consolidation pitch rests on a real position: third-party estimates put CrowdStrike at roughly 22.7% of endpoint protection, against Microsoft Defender's 15.6% and SentinelOne's 11.5%, with its strength concentrated in large cloud-first estates.
The numbers that stopped being published
Flex total deal value, the committed-dollars headline, was last quantified at more than $3.2bn in the April-2025 quarter, up more than sixfold. Its replacement is ending ARR from accounts that have adopted Flex, which passed $2.29bn at 31 July and grew 101%. That is a recognized measure, so the gap between dollars committed and dollars converted has left the public record. The five-or-more-module adoption rate, 67% as of 31 January 2025, is gone too; the disclosures now run 51% of subscription customers on six or more modules, 35% on seven and 26% on eight. A quarterly net retention percentage is no longer given, only the statement that gross and net retention both increased.
Cash is the one check that does not depend on management's framing, and it holds: free cash flow of $377m, 26% of revenue, with the full year guided to at least 30%. Stock compensation ran at about $377m in the same quarter, which is why GAAP net income was $5.3m and why sales and gross profit are the anchors that mean anything here.
A month of selling that came from outside the company
The worst session was 5 November, when the close fell 9.9% and Palantir, CrowdStrike and Okta all dropped about 10% as investors cut exposure to the data-center build-out after the Democratic congressional sweep. Three days earlier Deutsche Bank had upgraded the stock to Buy and raised its target to $300 from $240. On 29 October, Fortinet and ServiceNow both beat revenue estimates and were sold hard anyway. Over 30 days CrowdStrike's 12.9% decline was the third-smallest among the seven software and security names on this shelf, and the stock is still up 4.7% over three months.
So almost none of the fall traces to the business, and the compression has not undone much. At 57.8x trailing gross profit, CrowdStrike is dearer than the 48.4x it fetched in late July, and 51.9x forward. Palo Alto, which sells firewalls plus subscription services to large enterprises and governments, trades at 25.8x forward gross profit; Fortinet, whose FortiGate hardware business earned a 30.6% operating margin in the September quarter, at 14.4x; Zscaler, selling cloud-delivered secure access per user on 24.9% growth and a 76.7% gross margin, at 10.5x. CrowdStrike costs twice the nearest of them. The markdown repriced the growth; it did not find a flaw in the conversion.
What an owner is paying for, then, is a conversion engine whose best evidence is now a thickening order book and management's description of it. The next test of both arrives on 1 December, after the US close.