

ASML Says Its Planned 2027 and 2028 Output Will Not Meet Demand; Customers Are Prepaying
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Every listed maker of wafer-fabrication tools has been marked down hard in a month, on the reading that a memory shortage can be answered by node migration inside cleanrooms that already exist and so buys few new machines. The four vendors in the group that have reported since mid-October describe a different limit: physical fab space and parts.
ASML's September-quarter revenue grew 55.2% with gross margin up to 57.4%, and customer advances for tools due more than a year out rose €5.73bn in the quarter to €9.30bn. Lam Research grew 54.4% on a record 52.3% gross margin and said its December guide would have been higher but for supply constraints. Axcelis booked $222m for a 1.5x book-to-bill and named greenfield cleanroom availability as the gate.
The quarters explain none of the drawdown's ordering, which tracked size rather than memory content. Onto Innovation is the unresolved case: its forward earnings multiple of 21.4x rests on consensus revenue growth of 43% it has not yet reported against.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
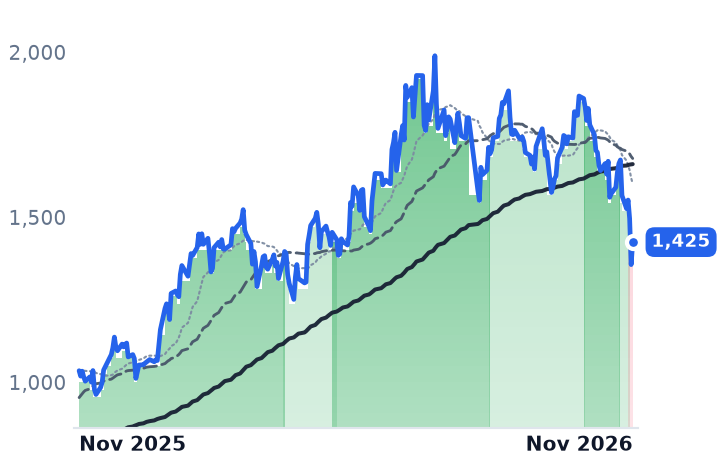
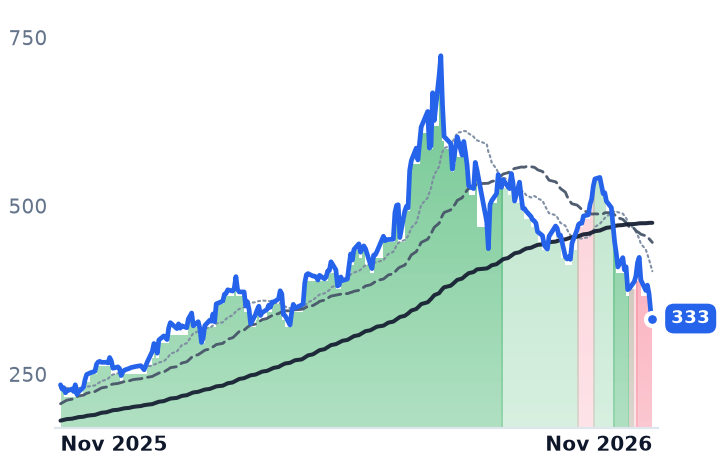
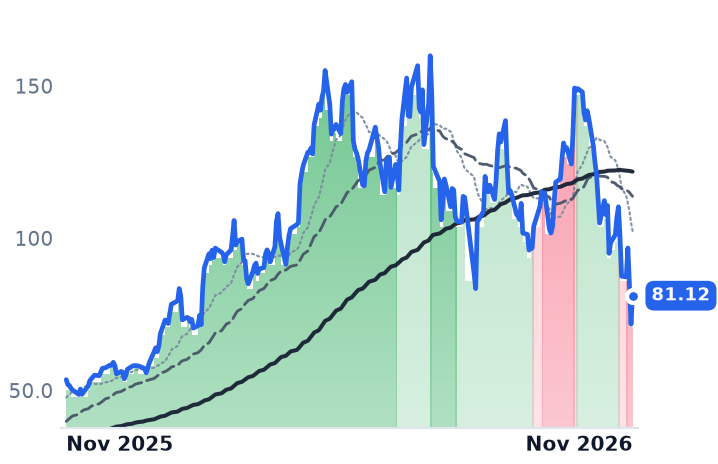
ASML | ASML | Fabrication Equipment & Materials | 🟢 Cont. Bull | −20.0% | +37.6% |
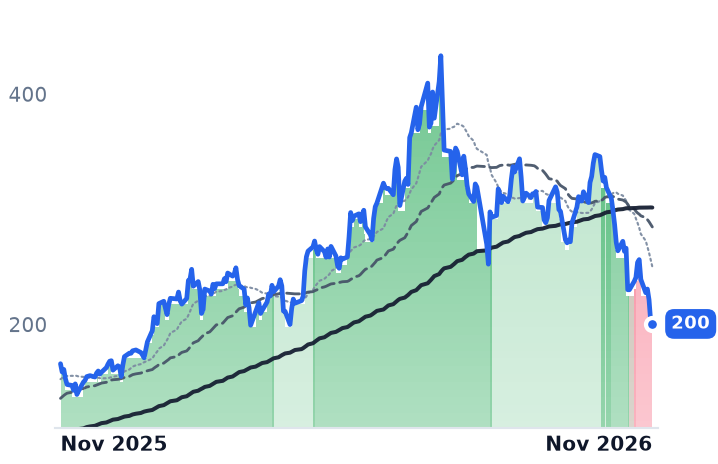
LRCX | Lam Research | Fabrication Equipment & Materials | 🟢 Cont. Bull | −37.1% | +20.8% |
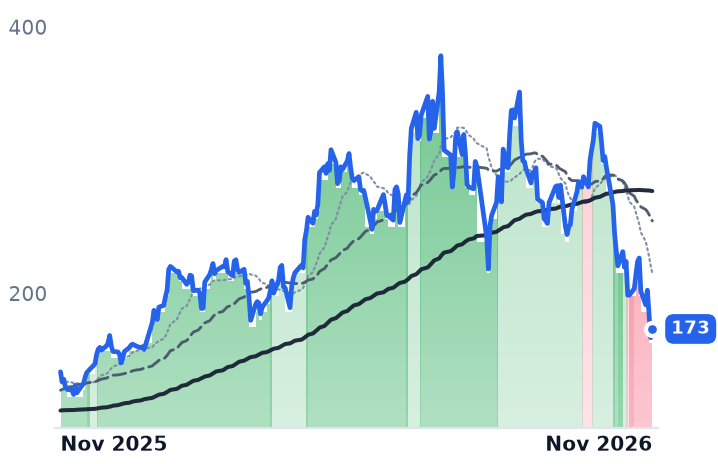
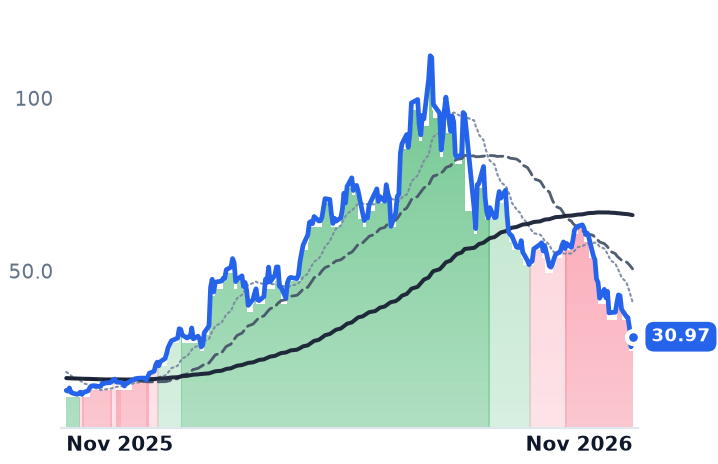
ONTO | Onto Innovation | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −41.2% | +22.8% |
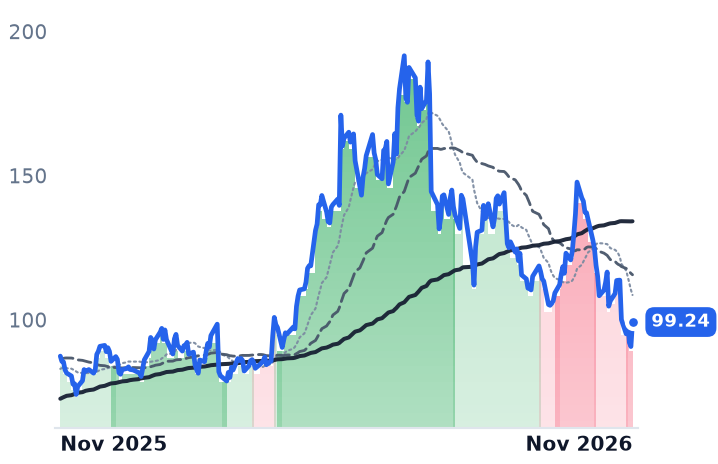
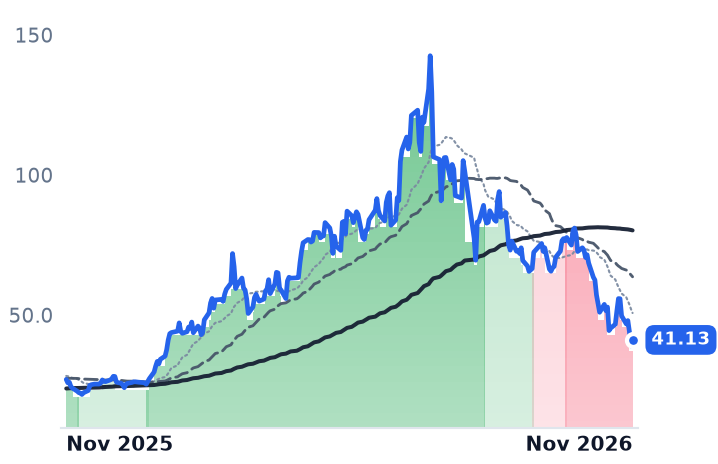
ACLS | Axcelis Technologies | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −26.3% | +13.5% |
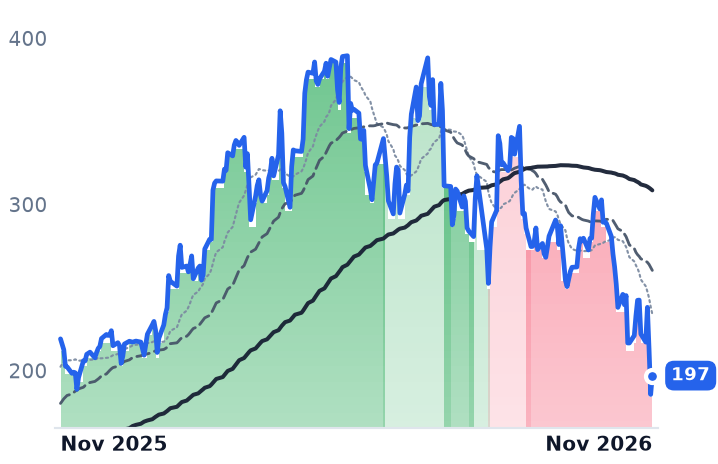
AMAT | Applied Materials | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −34.4% | +42.0% |
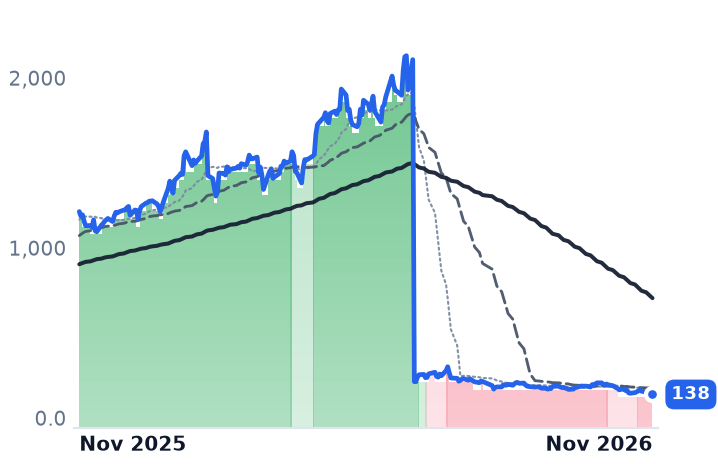
KLAC | KLA | Fabrication Equipment & Materials | 🔴 Cont. Bear | −29.2% | −88.6% |
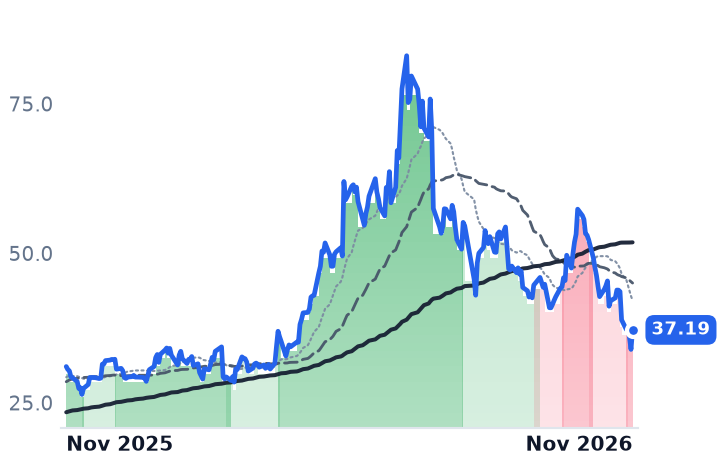
VECO | Veeco Instruments | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −28.9% | +19.7% |
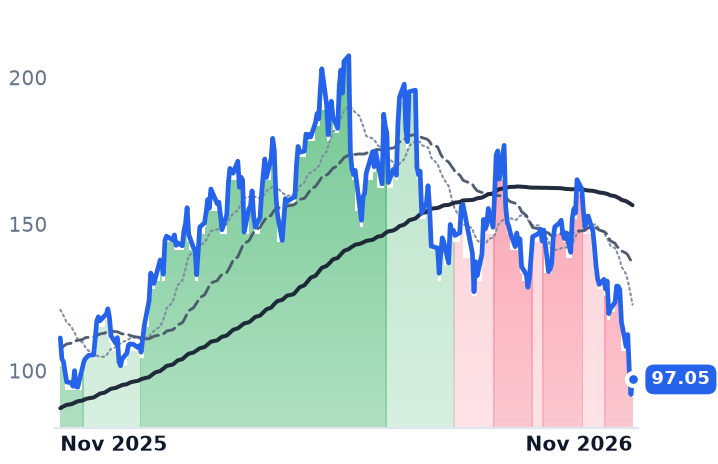
CAMT | Camtek | Test & Assembly Services | 🔴 Cont. Bear | −36.5% | −12.7% |
FORM | FormFactor | Test & Assembly Services | ⚠️ Emerging Bear | −41.9% | +51.5% |
ICHR | Ichor | Other | ⚠️ Emerging Bear | −48.3% | +100.8% |
UCTT | Ultra Clean | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −40.0% | +52.3% |
AEIS | Advanced Energy Industries | Power Conversion & Control | 🔴 Cont. Bear | −31.8% | −10.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ASML | $549.1B | 36.7x | 34.6x | 12.5x | 12.4x | 23.1x | 22.8x | 29.8x | 4.3% |
LRCX | $250.8B | 29.7x | 20.8x | 9.6x | 7.1x | 18.8x | 13.9x | 24.3x | 2.6% |
ONTO | $8.5B | 64.7x | 21.4x | 7.6x | 5.9x | 15.1x | 11.7x | 35.1x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACLS | $3.1B | 29.3x | 24.2x | 3.4x | 3.5x | 8.0x | 8.1x | 21.5x | 2.0% |
AMAT | $264.0B | 28.5x | 17.7x | 8.6x | 5.6x | 17.3x | 11.4x | 22.9x | 2.1% |
KLAC | $180.4B | 34.4x | 24.0x | 12.4x | 9.6x | 20.2x | 15.6x | 28.2x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VECO | $2.3B | 87.9x | 25.1x | 3.1x | 2.8x | 8.4x | 7.6x | 44.5x | 5.5% |
CAMT | $4.5B | 33.7x | 26.9x | 8.3x | 7.6x | 16.6x | 15.2x | 35.8x | 0.0% |
FORM | $6.3B | 36.5x | 24.0x | 6.5x | 6.0x | 13.1x | 12.2x | 27.3x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ICHR | $1.2B | 527.5x | 17.2x | 1.1x | 0.9x | 8.1x | 7.2x | 22.1x | -5.8% |
UCTT | $2.0B | 70.9x | 12.0x | 0.8x | 0.7x | 5.0x | 4.4x | 13.7x | -8.3% |
AEIS | $8.0B | 26.5x | 15.9x | 3.5x | 3.2x | 8.7x | 7.8x | 18.0x | 0.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ASML | Revenue | +36.8% | +29.7% | +25.6% |
| EPS | +66.3% | +38.0% | +32.0% | |
LRCX | Revenue | +27.0% | +52.4% | +20.1% |
| EPS | +41.9% | +69.5% | +25.6% | |
ONTO | Revenue | +2.2% | +43.1% | +30.8% |
| EPS | −5.1% | +63.3% | +44.9% | |
ACLS | Revenue | +8.3% | +11.9% | +26.0% |
| EPS | −8.7% | +28.3% | +56.2% | |
AMAT | Revenue | +21.5% | +36.5% | +22.0% |
| EPS | +36.8% | +46.5% | +31.2% | |
KLAC | Revenue | +12.2% | +39.5% | +20.1% |
| EPS | +14.5% | +55.5% | +23.1% | |
VECO | Revenue | +21.0% | +38.9% | — |
| EPS | +11.7% | +111.1% | — | |
CAMT | Revenue | +20.5% | +35.0% | +17.0% |
| EPS | +12.5% | +42.4% | +18.0% | |
FORM | Revenue | +34.6% | +24.3% | +26.7% |
| EPS | +199.2% | +29.0% | +38.5% | |
ICHR | Revenue | +30.7% | +31.9% | +10.7% |
| EPS | +955.2% | +90.7% | +18.8% | |
UCTT | Revenue | +35.2% | +39.9% | +14.8% |
| EPS | +225.8% | +88.8% | +23.8% | |
AEIS | Revenue | +41.4% | +31.1% | +18.4% |
| EPS | +98.6% | +44.4% | +24.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
ASML's September quarter carried an admission capital-equipment vendors rarely make: it has sold more machines than it intends to build. The Dutch company, the only producer of extreme-ultraviolet lithography scanners, moved its order-book disclosure onto the balance sheet after discontinuing quarterly net bookings, and the substitute line moved violently — customer advances for tools due more than a year out rose €5.73bn in the quarter, reaching €9.30bn. "Given the dynamics of this quarter, we now anticipate that our current planned levels of output in 2027 and 2028 will not fully meet the demand of our customers," chief financial officer Roger J. Dassen told investors on October 14.
The thirteen listed suppliers of wafer-fabrication equipment fell between 20.6% and 48.9% in the month to 6 November. The drawdown has been read as a memory shortage failing to convert into tool orders: bits added by node migration and conversion inside cleanrooms that are already built consume far less equipment than new wafer starts, so record memory capital budgets need not become record tool sales. The last reported quarter at four of these vendors locates the constraint somewhere else entirely — in the cleanrooms, not in the willingness to order.
The prepayments arrive before the floor space does
ASML's record net sales of €11.7bn grew 55.2% year on year, with gross margin widening to 57.4% from 51.6% and operating income more than doubling. Of €8.4bn in system sales, €4.1bn was EUV. Low-NA EUV output is going to roughly 65 systems this year from 44 in 2025, with 30% growth planned for 2027 in both low-NA EUV and immersion deep-ultraviolet, and management is investigating going beyond that for 2028 because demand exceeds the plan. Prices on the most critical high-volume products rise from 2027, described as one-time rather than annual; existing backlog is not repriced.
Installed-base management revenue — upgrades and service paid on tools already running — was €3.3bn in the quarter and is guided to grow about 50% this year against roughly 36% for the group. That is the one piece of the bearish mechanism that holds: at ASML, the running fleet is earning faster than the new one. At 34.6x forward earnings, the shares are below the 40-48x forward recorded in May.
Lam capped its own December guide on parts
Lam Research, which sells the etch and deposition tools that cut and fill the high-aspect-ratio structures in 3D NAND and high-bandwidth memory stacks, grew revenue 54.4% to $8.219bn on a record 52.3% gross margin, its fifth consecutive revenue record. Deferred revenue rose $227m to $2.66bn. "Our preliminary 2027 WFE outlook is for more than $200 billion of spending, with percentage growth led by DRAM, followed by leading-edge foundry logic and NAND," chief financial officer Doug Bettinger said on October 21, a figure KLA independently corroborated alongside record quarterly revenue of $4.14bn and its first operating margin above 46%.
The shares fell as much as 11% on the day, because Bettinger said the $8.6bn December guide would have been higher but for near-term supply-chain constraints, with deferred shipments pushed into the first quarter of 2027. Lam also told the market that limited cleanroom space and parts shortages would stop the industry meeting demand into 2027. Service revenue of $2.5bn grew 40%, slower than the group. China rose to 35% of revenue from 26%. The forward earnings multiple is 20.8x against roughly 38x in May, while reported growth more than doubled.
What 100,000 wafer starts costs in implanters
Axcelis Technologies, which builds ion implanters, supplies the arithmetic the thesis needs. Roughly $150m to $200m of implant equipment serves 100,000 wafer starts a month, and its top three memory customers are adding more than 1m starts a month over four to five years. Memory is about 20% of system sales, nearly all DRAM and HBM. September-quarter bookings of $222m gave a 1.5x book-to-bill, the best since the fourth quarter of 2023, and chief executive Russell J. Low named the gate on November 5: "we are watching very, very carefully the availability of kind of greenfield clean room space because clearly, you know, today, our customers are often 4 wall constraints." Megafabs open "starting in 2027, but they are they are gonna be in phases." The stock trades at 24.2x forward earnings, with consensus 2026 earnings per share of $4.11 down 8.7%.
That capacity is being built. Samsung, SK Hynix and Micron are expected to spend $146bn in 2027, 3.4 times the $43bn of 2024, and SK Hynix has pulled completion of its Yongin cluster forward by twelve years. J.P. Morgan Global Research estimates DRAM prices will have risen more than 400% from the start of 2024 to the end of 2026.
Onto's leg is not reportable yet
Onto Innovation, which sells macro defect inspection and 3D bump metrology into advanced packaging, is the unverifiable case. Its June quarter grew 35.3% with operating income up 97.1%, off a 2025 that rose 1.8%. It raised its 2026 advanced-packaging growth outlook to roughly 80% from 50%, crossed $1bn of backlog, and closed a volume purchase agreement estimated above $240m with a leading HBM manufacturer. But 64.7x trailing earnings compresses to 21.4x forward only on consensus 2027 revenue of $1.44bn, up 43%, and the company guided the September quarter to $380-400m and reports between 9 and 12 November.
What the quarters explain, and what they do not
Nothing in these results explains the ordering of the selling. Onto, the purest HBM metrology name, fell 42.2%; Ultra Clean's gas-panel assembly fell 41.7%; ASML, the most lithography- and memory-levered name of all, fell least at 20.6%. The sequence tracks market value and liquidity. Roughly two-thirds of the damage was done in October, after Applied Materials declined to put a number on 2027 equipment spending at its 13 October investor day — Applied's own July quarter grew 24.8% and it now trades at 17.7x forward against 28.5x trailing — and the rest in the week to 6 November, when concern over tighter oversight of data-center construction hit the whole AI complex, a move Bank of America characterized as multiple compression rather than earnings cuts. Applied sits 54.0% below its 52-week high and Lam 53.7%. Of the names here, only ASML still holds the uptrend all thirteen held in May.
The bear case is not wholly empty. China's share of world equipment spending fell from 42.3% to 36.5% in 2025 with billings down about 11%, so the pull-forward is normalising at industry level even as it failed to appear sequentially at Lam or Axcelis. And a cycle whose gating item is construction phasing is a cycle whose revenue can slip a quarter at a time without any customer changing its mind.
Which is the live question for 2027, and it is a question about concrete and electrical capacity rather than about bits. The three memory makers' output for all of next year is already reported sold out. The tools to make more have been ordered and, at ASML, partly paid for. What nobody in this chain controls is when the doors open.