

Appian Charges for AI by Moving Customers to a Pricier Tier of the Same Contract
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Software metered by the seat has been marked down for a year on the belief that AI shrinks the invoice. Appian's September quarter points the other way: revenue growth accelerated to 25.5% and its cloud net revenue expansion rate reached 120%, the strongest in more than five years, because AI adoption arrives as an upgrade to a more expensive tier of a contract the customer already holds.
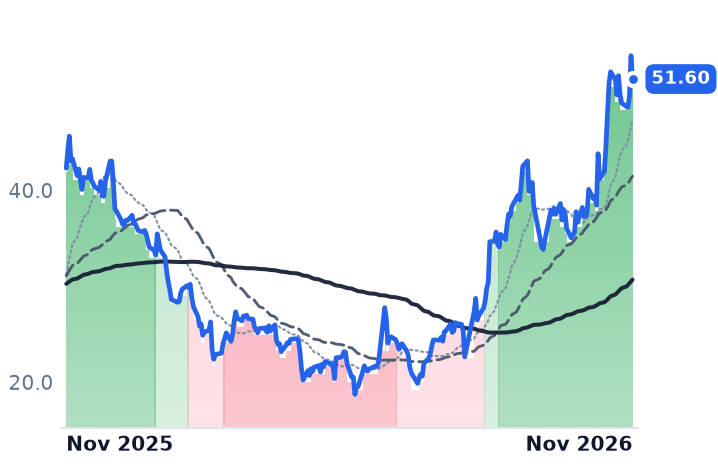
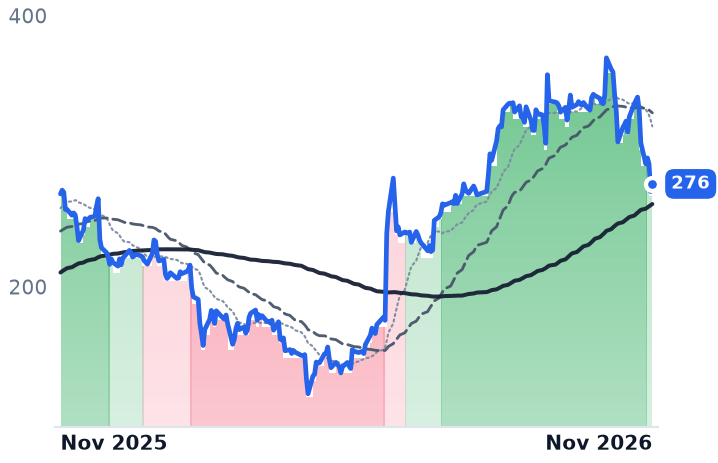
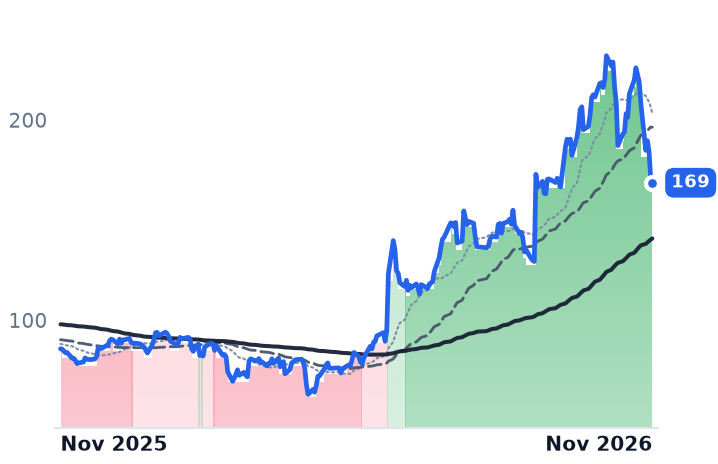
The business explains the share move. The uptrend began six sessions after the August beat-and-raise, well before the procedural win in Appian's trade-secrets retrial against Pegasystems. What the business does not yet cover is the price: gross profit grew 20.8% while price-to-gross-profit roughly doubled from early May, operating cash flow was minus $15m against positive $19m a year earlier, and consensus still models 2027 revenue growth at 10.8%.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
APPN | Appian | Developer Platforms & APIs | 🟢 Cont. Bull | +28.7% | +22.0% |
| Compared against · context, not the story | |||||
PEGA | Pegasystems | Sales, Service & Customer Management | 🔴 Cont. Bear | −9.1% | −45.8% |
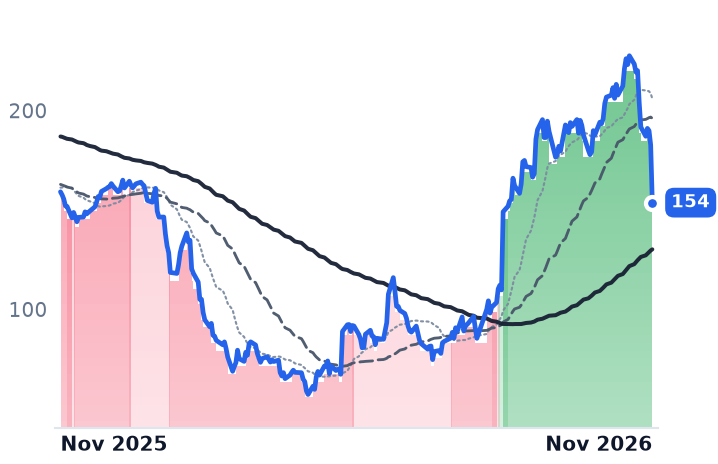
NOW | ServiceNow | Sales, Service & Customer Management | 🟢 Cont. Bull | −27.6% | −41.1% |
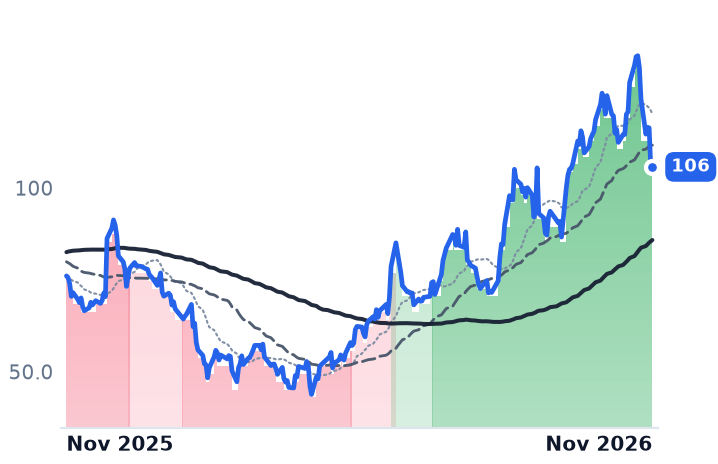
CRM | Salesforce | Sales, Service & Customer Management | 🌱 Emerging Bull | −6.8% | −11.0% |
SNOW | Snowflake | Data, Analytics & Intelligence | 🟢 Cont. Bull | −25.2% | +2.7% |
OKTA | Okta | Identity & Access Management | 🟢 Cont. Bull | −27.3% | +96.8% |
TEAM | Atlassian | Software Development & Design | 🟢 Cont. Bull | −25.7% | −3.4% |
RBRK | Rubrik | Storage, Backup & Data Management | 🟢 Cont. Bull | −15.5% | +39.0% |
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🟢 Cont. Bull | −25.1% | +44.9% |
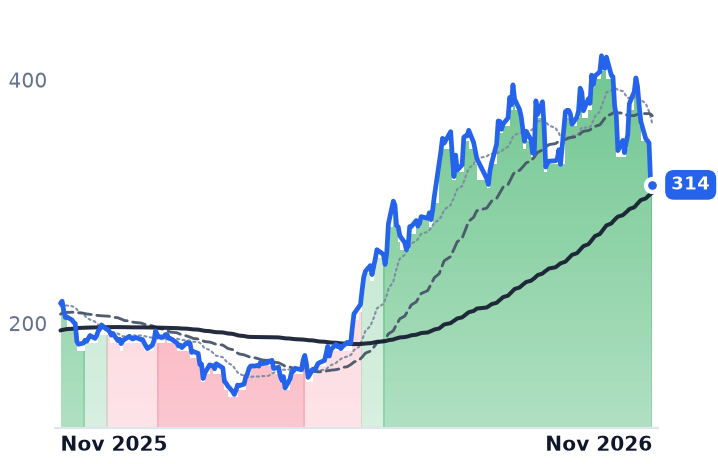
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPN | $3.7B | n/m | 47.7x | 4.4x | 4.3x | 6.1x | 6.0x | 158.1x | 1.0% |
PEGA | $5.3B | 18.6x | 15.6x | 3.0x | 3.0x | 4.0x | 3.9x | 25.4x | 8.5% |
NOW | $105.8B | 72.8x | 25.8x | 6.9x | 6.5x | 9.4x | 8.9x | 32.6x | 4.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRM | $175.8B | 19.4x | 12.8x | 4.0x | 3.8x | 5.2x | 4.9x | 12.5x | 8.6% |
SNOW | $97.3B | n/m | 124.4x | 17.9x | 15.4x | 26.7x | 23.0x | n/m | 1.2% |
OKTA | $28.2B | 99.8x | 42.9x | 9.2x | 8.7x | 11.7x | 11.2x | 66.7x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TEAM | $40.9B | 461.7x | 29.3x | 5.9x | 5.5x | 6.9x | 6.4x | 89.3x | 4.1% |
RBRK | $21.8B | n/m | 210.2x | 14.1x | 12.9x | 17.6x | 16.1x | n/m | 1.5% |
PANW | $256.9B | 682.3x | 75.0x | 22.4x | 18.1x | 31.8x | 25.8x | 166.8x | 1.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APPN | Revenue | +19.1% | +10.8% | +7.3% |
| EPS | +104.3% | +31.3% | +18.2% | |
PEGA | Revenue | +3.1% | +6.3% | +7.0% |
| EPS | −0.1% | +14.4% | +11.7% | |
NOW | Revenue | +22.6% | +18.5% | +18.1% |
| EPS | +13.5% | +21.6% | +22.2% | |
CRM | Revenue | +9.3% | +11.5% | +9.9% |
| EPS | +17.4% | +42.3% | −4.1% | |
SNOW | Revenue | +29.4% | +35.7% | +29.0% |
| EPS | +72.3% | +82.9% | +36.4% | |
OKTA | Revenue | +12.0% | +10.8% | +9.9% |
| EPS | +24.3% | +14.1% | +10.6% | |
TEAM | Revenue | +24.7% | +15.2% | +15.1% |
| EPS | +55.5% | +0.0% | +21.7% | |
RBRK | Revenue | +48.7% | +32.0% | +21.5% |
| EPS | −90.5% | −389.4% | +53.1% | |
PANW | Revenue | +24.3% | +24.0% | +14.3% |
| EPS | +15.5% | +10.7% | +16.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
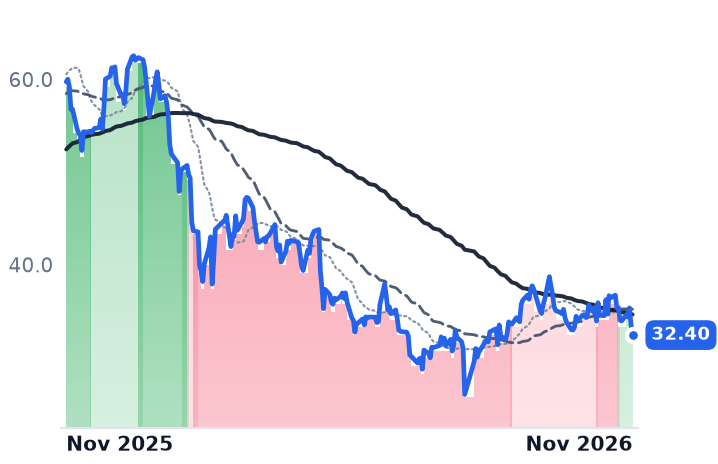
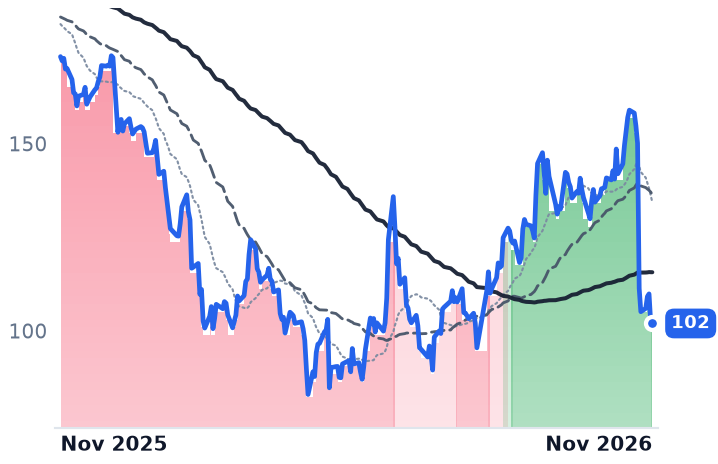
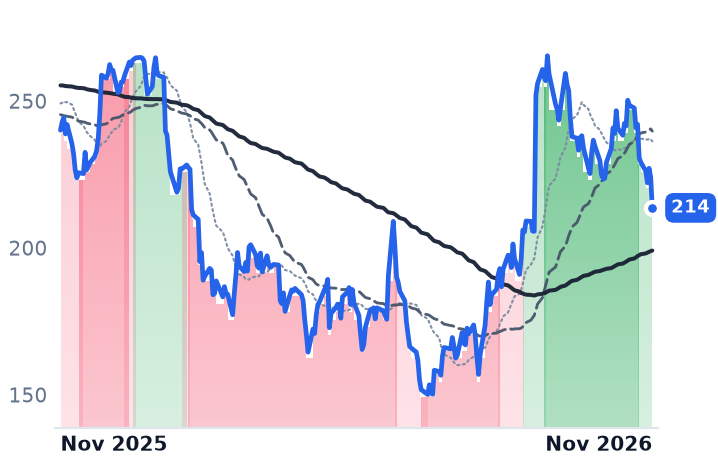
Appian raised its full-year guidance on 5 November after revenue growth accelerated in the September quarter, and its shares rose in a week when every large enterprise-software name around it fell. Between 4 and 6 November, ServiceNow lost 7.2%, Pegasystems 8.3%, Salesforce 5.9% and Snowflake 5.1%. Appian gained 3.7%.
The year-long mark-down of enterprise software rests on one mechanism: if an AI-assisted employee does the work of three, a per-seat invoice falls by up to two-thirds. Bain puts the cost of that repricing at roughly $2trn of market value over twelve months. Appian, which sells a low-code platform that generates workflows, forms, data models and interfaces instead of hand-coded applications to banks, insurers, life-sciences companies and government agencies, was read as an early casualty: a process-automation layer with no infrastructure underneath it, facing ServiceNow, Pegasystems and Microsoft's Power Platform. Over the year to 6 November, Pegasystems fell 45.0% and ServiceNow 40.6%. Appian rose 34.5%.
The upsell that reads as retention
Appian's AI money arrives as a price increase. Most of the quarter's uplift came from customers upgrading to the Advanced Tier, which carries a 25–35% premium to Standard, with AI usage up more than 50% from the prior quarter and consumption overages growing but not yet material. The effect lands in the company's disclosed retention meter: cloud net annual-recurring-revenue expansion hit 120%, against 115% in the prior quarter and 112% a year earlier, which management called the strongest in more than five years. Cloud subscription revenue of $136m grew 20%; total subscriptions, including self-managed software, grew 28% to $188m.
"Appian has claimed a distinctive and valuable place in the AI stack," chief executive Matthew Calkins told investors on 5 November. "We connect the world's most important technology to the world's most important work."
Four verticals — financial services, insurance, life sciences and the public sector — supply 80% of recurring revenue, and more than 70% of the business comes from customers spending over $1m a year, chief financial officer Serge Tanjga told the William Blair growth conference. That concentration is why one US Cabinet agency's seven-figure procurement deal moves a quarter.
Margin widened; the cash went the other way
GAAP operating income rose 62.4% to $21.3m, a 9.1% margin, and adjusted EBITDA of $43m beat a $30–33m guide. Full-year EBITDA guidance went to $116–119m, up about 53%, and revenue guidance to $873–877m. The base is low: 2025 was Appian's first positive GAAP operating year, at $0.6m on $726.9m of revenue.
Three things complicate the inflection. GAAP gross margin fell 2.9 points to 72.9%, while management described gross margin as 74% on a non-GAAP basis, flat year on year. Professional-services gross margin fell to 24% from 31% as implementations scale. And operating cash flow was minus $15m against positive $19m a year earlier, with cash and investments down to $89m from $187m at the end of 2025; $83m of that decline is cumulative buybacks under a $100m authorization. Management called the cash timing-driven and said October collections were among the strongest months on record.
The January retrial is not the engine
The shares have held an uptrend since 12 August, six sessions after the 6 August second-quarter beat-and-raise. The retrial of Appian's vacated $2.036bn trade-secrets award against Pegasystems opens on 11 January 2027, after the Supreme Court of Virginia threw out the 2022 verdict in January 2026; on 16 October the court let Appian present a reasonable-royalty damages theory it was barred from using at the original trial. Appian then rose 27.2% in a week. But Pegasystems rose 5.4% in the same window and ServiceNow 12.0%, so the likelier reading is a broad software rally that Appian led at roughly twice the move. Short interest of about 3.79m shares, some 5.3% of shares outstanding, is too small to be the cause.
Dearer than it was, cheaper than ServiceNow
Price-to-gross-profit has gone from 3.07x in early May to 6.05x, against gross profit that grew 20.8%: the price has roughly doubled relative to the profit it buys. On forward earnings, Appian's 47.7x is nearly twice ServiceNow's 25.8x.
Measured against forward gross profit the order inverts. Appian's 6.00x sits below ServiceNow's 8.92x, where 20.5% revenue growth came with GAAP operating income down 32.7%, and far below Snowflake's 22.97x, where 35.1% growth comes with a $263.0m quarterly operating loss.
Pegasystems, at 3.91x forward gross profit, is the cheapest of the four, and 3.1% revenue growth with 7% annual contract value growth says why. "Our technology is differentiated and very relevant to the times we are in. However, candidly, our execution this year has not kept up," founder-chief executive Alan Trefler said on 21 October. Salesforce, at 4.92x, grew 10.8%.
What the quarter can and cannot pay for
The operating results account for the direction and the timing of the advance, and for Appian being the one name in its neighborhood that gained in the week its peers gave up ground. They do not account for the full doubling of the valuation, because the acceleration is one quarter old. In the June quarter revenue growth slowed to 19.1%, GAAP gross margin compressed to 71.2%, and unsatisfied performance obligations of $625.3m grew 13%, slower than revenue. The raised fourth-quarter revenue guide of $233–237m implies about 16% growth, partly on a 2–3 point currency headwind, and consensus has 10.8% revenue growth in 2027 while earnings per share still rise 31%. What is being bought at 47.7x forward earnings is margin, and the sell side said so: William Blair upgraded to Outperform while DA Davidson lifted its target to $60 from $42 and TD Cowen to $58 from $50, both keeping their ratings.
Neither company's balance sheet carries the claim against Pegasystems, and nothing changes hands before a verdict. Until a jury meets in January, the invoice has to do the work on its own — and Tanjga, asked whether this quarter's expansion rate becomes the new baseline, declined to guide to the metric at all.