

Ouster's Record Sensor Quarter Came From Cameras as Lidar Units and Gross Profit Fell
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A sensor maker whose whole investment case rests on units deployed just shipped its biggest quarter ever and took home fewer gross-profit dollars for it. Ouster's third-quarter gross profit fell 5.3% sequentially to $25.3m on 59% more sensors shipped, because the extra volume was Stereolabs stereo cameras while lidar shipments dropped to over 7,000 from over 9,000.
Revenue still rose 50.1% to $59.3m, and the margin rate held once a one-time tariff refund is stripped out of the prior quarter. The erosion is in dollars per unit, not in the percentage.
Cognex, the machine-vision maker, is the opposite case: gross profit up 18.4% on revenue up 13.2%, guidance raised, and the shares at their lowest price-to-gross-profit of the year at 10.2x against 13.4x in May. Nothing about deployed-sensor economics links the two.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
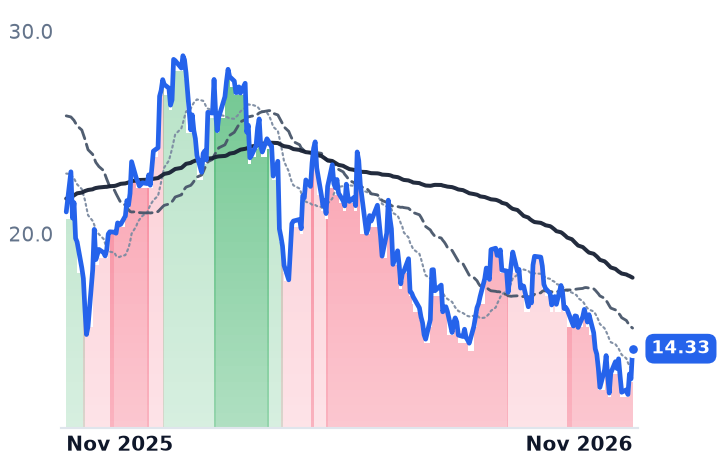
OUST | Ouster | Sensors & Specialized Semiconductors | 🔴 Cont. Bear | −13.9% | +35.3% |
CGNX | Cognex | Test & Measurement | ⚠️ Emerging Bear | −21.2% | +22.1% |
AMBA | Ambarella | Sensors & Specialized Semiconductors | 🔴 Cont. Bear | −9.2% | −34.7% |
| Compared against · context, not the story | |||||
CEVA | CEVA | Sensors & Specialized Semiconductors | 🔴 Cont. Bear | −22.2% | +3.6% |
ROK | Rockwell Automation | Industrial Automation & Motion Control | ⚠️ Emerging Bear | −12.7% | +1.4% |
TER | Teradyne | Test & Assembly Services | 🟢 Cont. Bull | −46.1% | +19.9% |
SYM | Symbotic | Industrial Automation & Motion Control | 🔴 Cont. Bear | −12.2% | −47.2% |
MBLY | Mobileye Global | Autonomous Driving & Electronics | 🔴 Cont. Bear | −17.4% | −54.6% |
HSAI | Hesai | Autonomous Driving & Electronics | 🔴 Cont. Bear | −8.4% | −32.0% |
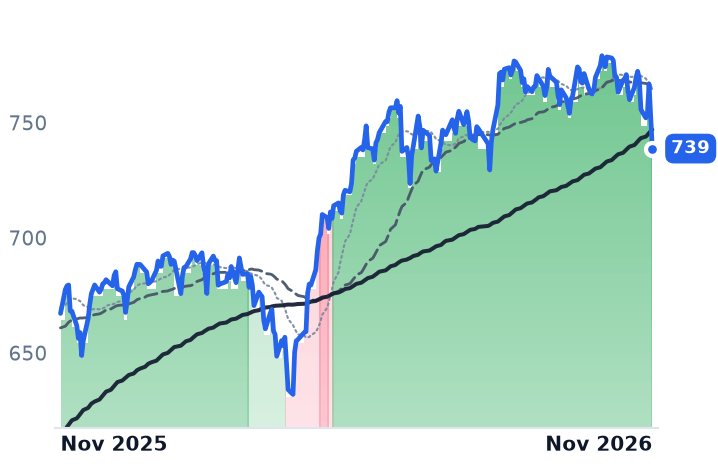
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −5.0% | +10.2% |
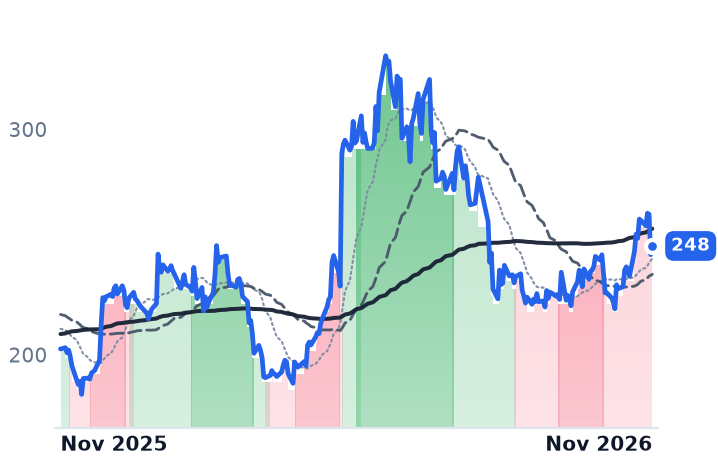
NXPI | NXP Semiconductors | Processors & Accelerators | ⚠️ Emerging Bear | +9.2% | +22.6% |
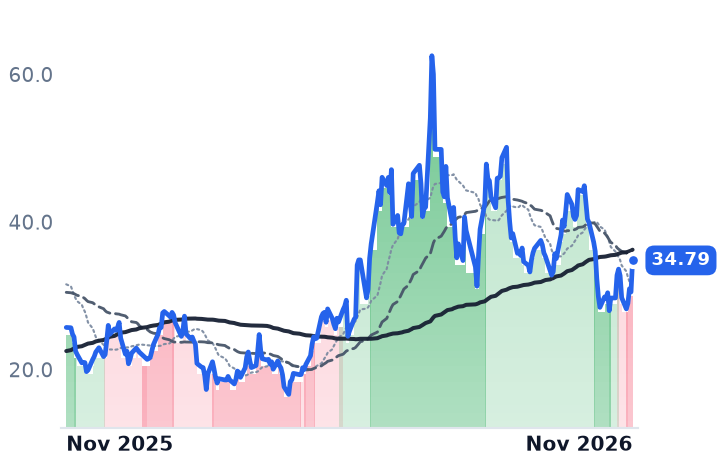
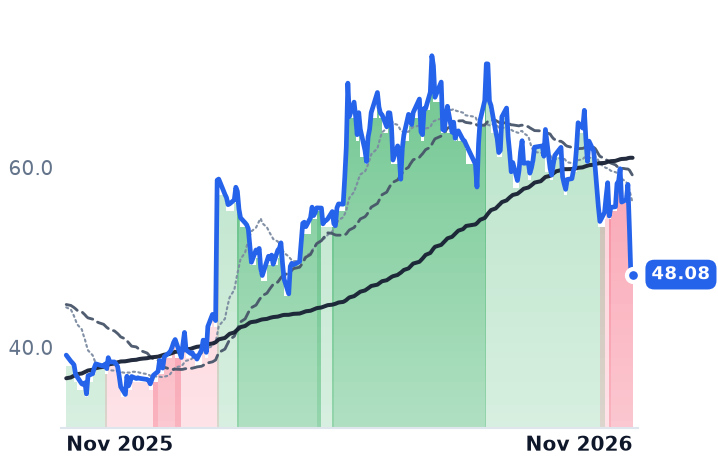
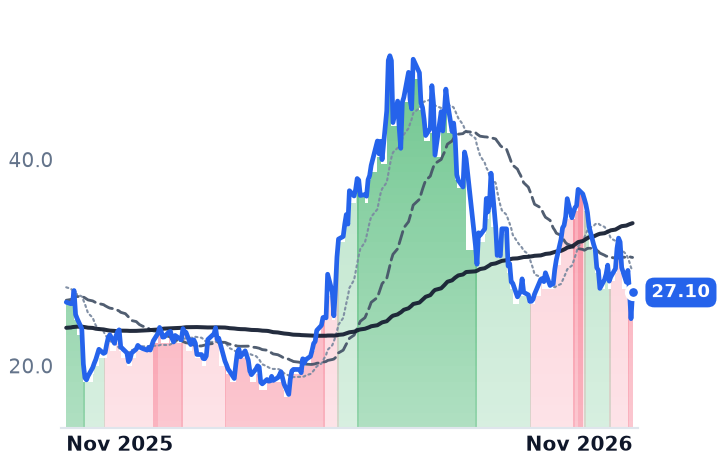
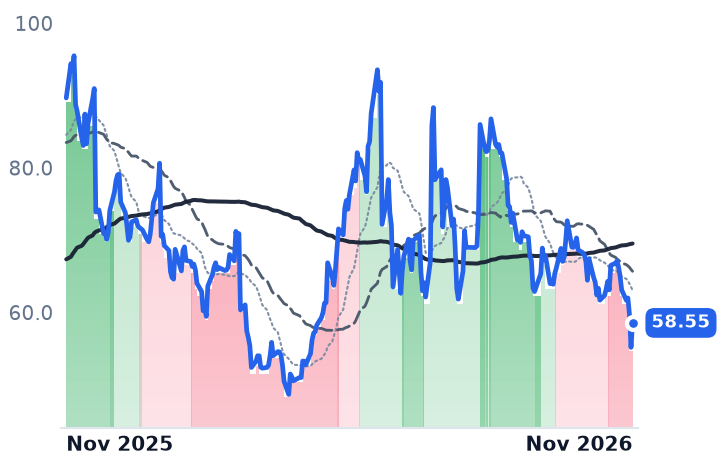
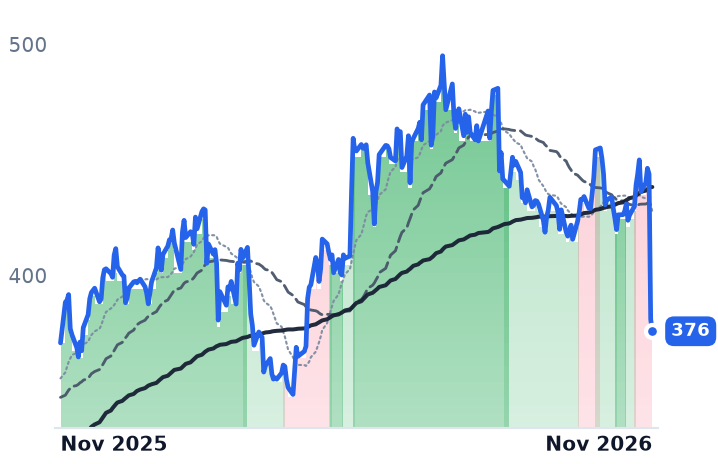
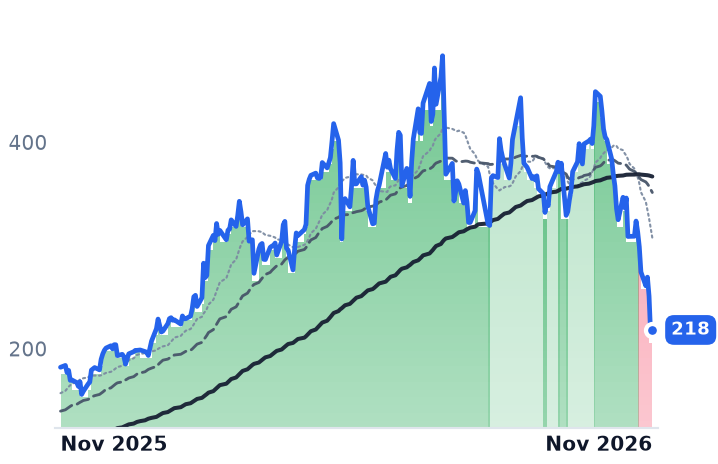
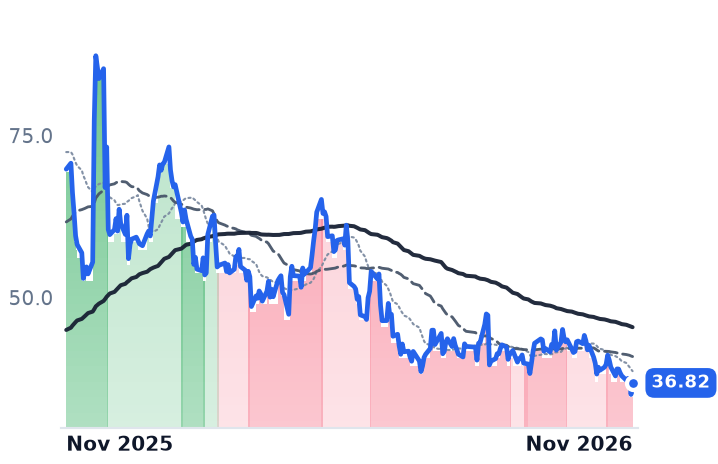
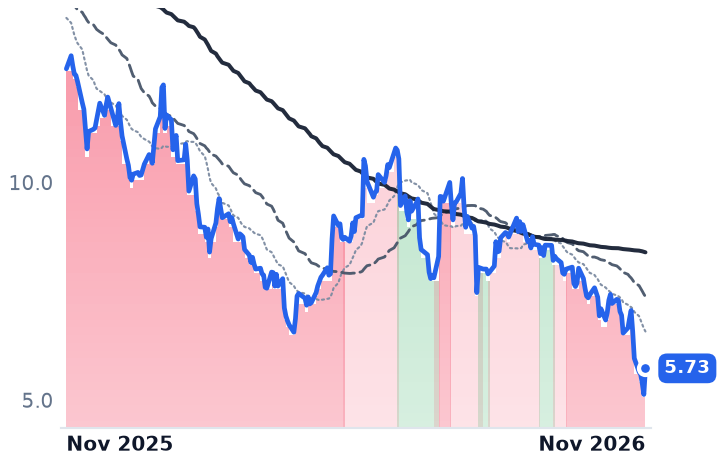
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OUST | $2.5B | n/m | — | 11.2x | 11.2x | 22.8x | 22.8x | n/m | -3.9% |
CGNX | $8.0B | 33.2x | 28.4x | 7.1x | 7.0x | 10.2x | 10.1x | 23.7x | 3.6% |
CEVA | $763.0M | n/m | 49.4x | 6.6x | 6.1x | 7.5x | 7.0x | n/m | -0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMBA | $2.6B | n/m | 72.9x | 6.2x | 5.9x | 10.6x | 10.1x | n/m | 0.4% |
ROK | $41.6B | 29.8x | 25.1x | 4.6x | 4.3x | 9.2x | 8.7x | 21.0x | 4.1% |
TER | $33.4B | 24.4x | 22.5x | 6.7x | 6.4x | 11.3x | 10.8x | 18.5x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SYM | $22.2B | 381.8x | 89.2x | 8.4x | 6.2x | 38.8x | 28.6x | 347.3x | 3.3% |
MBLY | $7.0B | n/m | 17.4x | 3.5x | 3.5x | 7.3x | 7.4x | n/m | 5.6% |
HSAI | $2.7B | 37.3x | — | 5.5x | — | 13.6x | — | 32.2x | 0.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
NXPI | $62.6B | 19.4x | 16.3x | 4.5x | 4.4x | 8.1x | 7.8x | 13.4x | 5.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
OUST | Revenue | +51.5% | +34.8% | +34.5% |
| EPS | −59.8% | −120.6% | +710.1% | |
CGNX | Revenue | +16.8% | +11.0% | +10.8% |
| EPS | +74.9% | +17.9% | +14.5% | |
CEVA | Revenue | +14.3% | +13.3% | +12.9% |
| EPS | +31.8% | +46.4% | +36.5% | |
AMBA | Revenue | +39.8% | +12.9% | +11.6% |
| EPS | −310.6% | +34.9% | +31.8% | |
ROK | Revenue | +10.2% | +5.8% | +6.2% |
| EPS | +31.8% | +12.5% | +11.4% | |
TER | Revenue | +69.7% | +24.6% | +22.3% |
| EPS | +167.0% | +30.0% | +30.9% | |
SYM | Revenue | +25.6% | +28.3% | +25.8% |
| EPS | −15.8% | +101.1% | +105.7% | |
MBLY | Revenue | +6.3% | +9.5% | +22.5% |
| EPS | +37.4% | +2.4% | +39.5% | |
HSAI | Revenue | +37.8% | +40.9% | +30.8% |
| EPS | −75.8% | +39.4% | +12.5% | |
NXPI | Revenue | +17.0% | +12.3% | +9.3% |
| EPS | +29.2% | +20.5% | +17.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ouster shipped more than 27,000 sensors in its third quarter, the most in its history, and collected less gross profit from them than from the 17,000 it shipped three months earlier. Gross profit fell 5.3% sequentially, to $25.3m from $26.7m, on 59% more units out the door.
The lidar maker's unit count has been the headline number in every quarterly release, and the "physical AI" case for sensor vendors is that deployment volume compounds into dollars. This quarter the count and the dollars came apart. Ouster disclosed over 7,000 lidar units against more than 9,000 in the prior quarter, while its Stereolabs ZED stereo cameras went to 20,000 from more than 8,000. Dividing reported revenue by those company-supplied counts gives roughly $2,197 of revenue per sensor, down about a third sequentially, and roughly $935 of gross profit per sensor, down about 40%.
The extra 10,000 units were the cheap ones
Revenue itself was fine: $59.3m, up 50.1% year on year and 9% sequentially, with product revenue a record $56m and a fifteenth consecutive quarter of growth. Gross margin printed 42.6% against 48.9% in the prior quarter, but that comparison is distorted by a one-time $5m tariff refund; excluding it, the earlier quarter was about 39.7%, so the underlying rate improved. The deterioration sits in the dollars each unit carries, which is a mix outcome rather than a pricing one.
The lidar line is where the company is placing its bet. "As the world's first native color LiDAR, REV8 is a paradigm shift that is proving to be an undeniable competitive differentiator," chief executive Angus Pacala told investors on November 3. Chief financial officer Kenneth Gianella said demand is "continuing to see that demand rotate more towards REV8." Against Hesai and RoboSense, which supply geometric lidar data and which held, in Hesai's case, 44% of China's long-range advanced driver-assistance lidar market in June 2026, Ouster's durable edge is regulatory: compliance with the National Defense Authorization Act and Buy-American rules bars its Chinese rivals from federally funded US projects. Third-quarter wins ran through the Utah, Washington, Florida and Ontario departments of transportation, plus defense customers Forterra, Seneca and GOQ.
Margin upside is going into tooling
Management holds a long-term gross-margin target of 35-40%, says it is currently beating that band, and is spending the difference on retooled lines and precision automation under a Benchmark partnership meant to support more than 100,000 lidar units of annual capacity by the end of 2027. No volume commitment underwrites that. The adjusted EBITDA loss narrowed about 60% year on year to roughly -$3m, the reported operating loss was $19.3m, and cash stood at $421m including about $191m raised in a July equity offering. The shares carry 22.8x trailing price-to-gross-profit, more than twice Cognex's 10.2x.
Cognex earned more per dollar of sales and got marked down
Cognex, which sells barcode readers and integrated vision systems to logistics, electronics and automotive manufacturers, ran the reverse arithmetic. Revenue of $313.4m rose 13.2% to a company record, gross margin expanded 312 basis points to 70.8%, gross profit rose 18.4% and operating income rose 74.5% to $100.8m. Full-year guidance went up, to revenue of $1.14-1.16bn and adjusted earnings of $1.68-1.72 a share. "At the midpoint of our guidance, we expect approximately 93% flow-through of incremental revenue to adjusted EBITDA, compared with roughly 70% in 2025," chief financial officer Dennis Fehr said on November 5.
The stock fell 18.3% across the two sessions into that print. Contemporaneous coverage put the company-specific reaction at about -6% on a slight revenue miss; the remainder landed in the November 5 washout, when the Philadelphia Semiconductor Index fell 12.2%, the session the paper has already described as repricing data-center demand expectations. Trailing price-to-gross-profit is now 10.2x against 13.4x in May, on a materially larger gross-profit base. The cautions are internal: automotive was flat year-to-date on European weakness, with Europe revenue down 15%, and management guided 2027 incremental flow-through down to about 60%.
A unit count has stopped predicting a gross-profit line
One quarter of results explains almost none of what happened to these shares, and the per-sensor mechanism that was supposed to bind them explains less. Ouster's dollars per unit fell because the marginal sensor is a camera rather than a lidar; Cognex does not disclose units at all and grew gross profit by price, mix and margin execution. Ceva, which licenses digital-signal-processor and connectivity designs and is paid a royalty on every device shipped, shows the same squeeze one layer down: licensee shipments of 567m units rose 16% in the June quarter while royalty revenue rose 1%, about 1.9 cents a device from 2.2 cents. It trades at 7.6x trailing gross profit, the cheapest of the three, and reports on November 9.
What survives is three separate businesses billing three different ways, all of them paid out of factory, logistics, infrastructure and defense budgets that have nothing to do with hyperscaler capital spending.
Ouster is building for a lidar volume nobody has promised it: lines sized for more than 100,000 units a year by the end of 2027. Until the orders arrive, the sensor it ships most often is the one that earns it least.