

Customer-Service Outsourcers Still Bill by the Agent-Hour as AI Shifts Work Between Them
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Every listed operator of outsourced customer contact and back-office work re-rated over the past month, and the quarters they reported pull in opposite directions. ExlService's revenue growth accelerated for a third straight quarter, to 19.7%; Concentrix guided its November quarter to a 3% to 5% constant-currency decline.
The advance was read as artificial-intelligence deflection finally paying through contracts billed per resolved problem. The filings show little of it: Concentrix's software platform carries about $120m of recurring revenue against $9.85bn of group sales, ExlService calls the timing of its outcome-based shift "unclear and unsettled", and TaskUs plans ordinary price increases.
ExlService and ibex earned their advances with growth and raised guidance. TaskUs sold a record quarter with 9.2% less gross profit, and Concentrix's re-rating is closing a valuation gap at 0.57x trailing gross profit.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
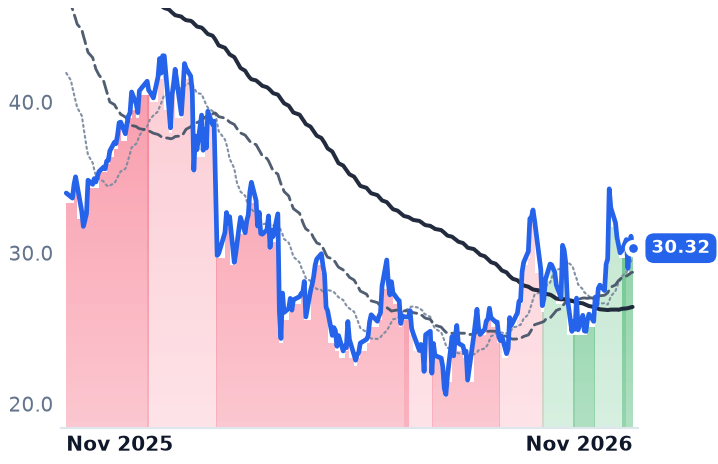
CNXC | Concentrix | Customer Experience & Operations | 🌱 Emerging Bull | +18.5% | −10.8% |
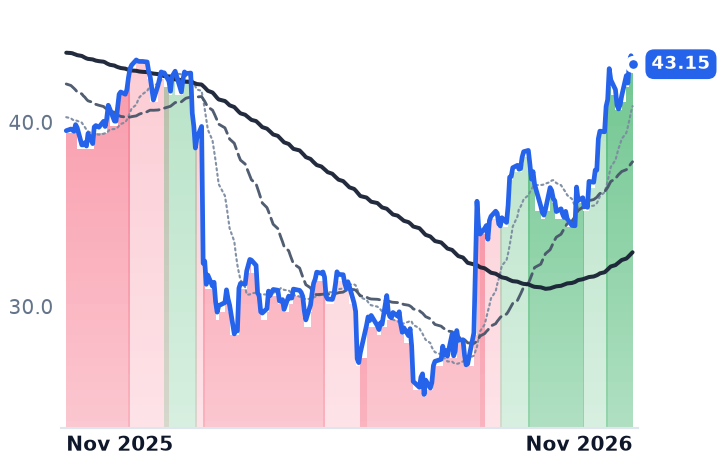
EXLS | ExlService | Customer Experience & Operations | 🌱 Emerging Bull | +22.0% | +9.1% |
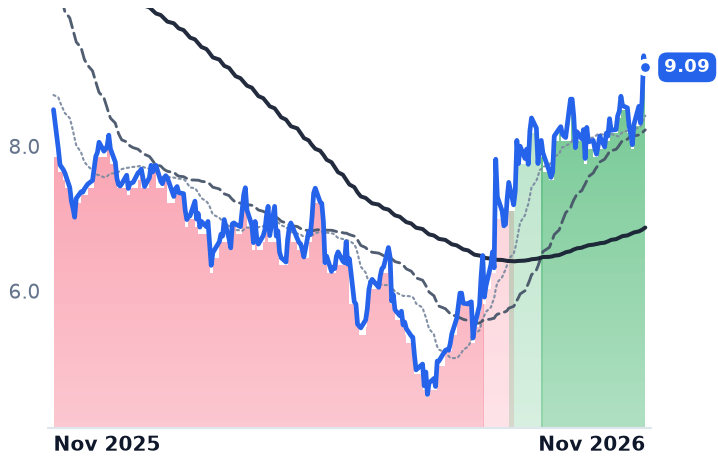
TASK | TaskUs | Customer Experience & Operations | 🌱 Emerging Bull | +13.5% | +6.9% |
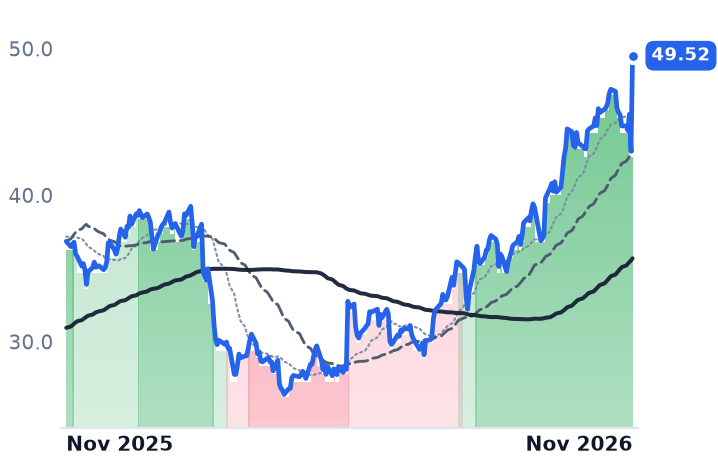
IBEX | IBEX | Customer Experience & Operations | 🟢 Cont. Bull | +11.5% | +34.4% |
| Compared against · context, not the story | |||||
G | Genpact | Consulting & Professional Services | 🌱 Emerging Bull | +26.7% | −4.5% |
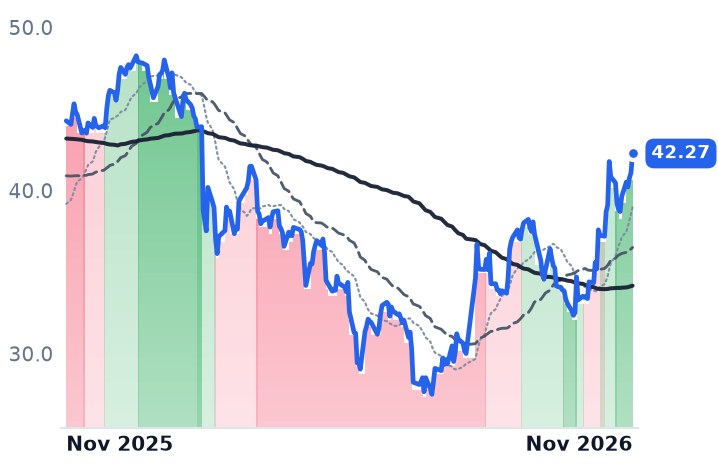
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CNXC | $1.9B | n/m | 2.7x | 0.2x | 0.2x | 0.6x | 0.6x | n/m | 31.0% |
EXLS | $6.5B | 25.7x | 18.3x | 2.8x | 2.7x | 7.2x | 7.0x | 15.9x | 4.2% |
TASK | $833.4M | 8.0x | 6.8x | 0.7x | 0.7x | 2.1x | 2.1x | 5.6x | 12.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IBEX | $660.8M | 13.5x | 13.4x | 1.0x | 0.9x | 4.6x | 4.3x | 9.2x | 4.9% |
G | $7.0B | 11.9x | 10.0x | 1.3x | 1.3x | 3.5x | 3.5x | 7.7x | 5.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CNXC | Revenue | +0.4% | −0.3% | +1.1% |
| EPS | −2.8% | +4.2% | +2.3% | |
EXLS | Revenue | +17.3% | +12.9% | +11.0% |
| EPS | +23.1% | +12.8% | +14.5% | |
TASK | Revenue | +5.8% | +6.4% | +7.1% |
| EPS | −15.3% | +11.3% | +9.6% | |
IBEX | Revenue | +17.6% | +11.3% | +6.8% |
| EPS | +36.4% | +5.1% | +10.4% | |
G | Revenue | +7.2% | +7.1% | +7.9% |
| EPS | +13.9% | +9.4% | +10.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Between late October and the first week of November the four listed operators of outsourced customer contact and back-office work all reported, and the quarters pulled them apart. ExlService raised full-year guidance for the second time this year. Concentrix, which staffs and runs customer-contact operations plus front- and back-office automation for consumer-electronics, e-commerce, health-insurance and banking clients, guided its November quarter down. All four shares are higher over the month, each by double digits.
For two years these companies have been read as the clearest casualties of agentic artificial intelligence, and the month's advance was read as the turn: deflection arriving as revenue through contracts that charge for a resolved problem instead of an agent's hour. The filings carry the first half of that and almost none of the second. Work is moving between providers. The unit they bill has barely changed.
A seat at ExlService bills near twice a contact seat
ExlService, which sells insurance and healthcare analytics, claims processing, premium audit and payment accuracy, grew September-quarter revenue 19.7% to $634.0m, a third consecutive acceleration, with gross profit up 18.2%. Organic headcount rose 11% against 17% organic revenue growth; employee cost falling as a share of revenue is the mechanism management names. Divide the quarter's revenue by its 65,000 staff and annualize and the result is roughly $39,000 per employee, a derived figure, against about $21,600 on the same arithmetic at Concentrix and its payroll of 455,000.
"Data and AI-led revenue grew 36% on a reported basis and 31% organically in the third quarter, now representing almost 2/3 of EXL's total revenue," chairman and chief executive Rohit Kapoor said on the 28 October call. Digital Operations revenue fell 1.7% by design as AI was embedded in work the company already ran. Guidance went to $2.430bn-$2.440bn with adjusted earnings of $2.34-$2.36 a share. It is also the dearest name here, at 7.24x trailing gross profit and 6.95x forward, against 3.52x for Genpact, the nearest listed peer.
Concentrix's shrinkage was ordered by two clients
Concentrix's revenue declined 1.2%, or 0.5% in constant currency, after 5.4% growth in the February quarter. The November quarter is guided to $2.41bn-$2.46bn, a 3% to 5% constant-currency fall, because two hyperscaler clients are completing a reduction in support coverage, pulled forward from 2027. Beneath that sits a roughly three-point annual headwind from clients moving seats to cheaper countries. Gross margin held at 34.6%, and non-GAAP operating margin widened 30 basis points to 12.6%.
The mix story is real and small. "This quarter, we crossed the mark that 50% of our revenue now comes from businesses that we generated in the last 3 years," chief executive Christopher Caldwell told investors on 29 September, putting that pool's growth near 30% for the year. The software meter inside it, iX Suite licensing, carries about $120m of annual recurring revenue, some 1.2% of the $9.85bn consensus expects for fiscal 2026. Retention across the whole client base is 98% and the top 25 clients average more than 16 years, so capability is not the problem; price is. The company also acquired CastleHill Managed Risk Solutions for governance, third-party risk and AI-governance work.
Its shares rose 15.7% in the 22 October session, the largest single day on the list, with no earnings in the window; a dividend raise and that acquisition were the only datable news, so positioning is the likelier reading. At 0.57x trailing gross profit, a 31% trailing free-cash-flow yield and 2.74x forward earnings, the advance is closing a valuation gap. Trailing price-to-earnings is unusable: a $1.05bn non-cash goodwill impairment, triggered by the share price's own trading range, followed a $1.48bn write-down a year earlier.
TaskUs grew the line that costs most to deliver
TaskUs, which provides digital customer support, trust-and-safety moderation and data labelling for model training, grew revenue 5.4% to a record $314.7m while gross profit fell 9.2% to $108.9m, costing it 553 basis points of margin. "The current growth that we are seeing in AI services seems to be heavy on the onshore side, which comes at lower margins than what we make in our offshore business," chief financial officer Rishabh Khemka said on 4 November. AI services reached $75.0m, up 27.7%; trust and safety fell 15.8%. The largest client dropped to 17% of revenue from 27% on its own automation. Management's answer to the cost line is conventional price increases. The stock trades at 6.8x forward earnings.
ibex was handed the calls it automated
ibex, which runs customer care and technical support across voice, chat and SMS for banking, healthtech, retail and travel clients, is the clean case. "By having all contacts immediately reaching an AI agent, we were able to reduce abandoned calls by more than 60% without the need for our client to add additional headcount," chief executive Robert Dechant said on 5 November. The fibre provider in question then awarded ibex its traditional call-centre work. Revenue was a record $175.2m, up 16%, adjusted EBITDA rose 29%, and guidance went to $720m-$735m. Onshore revenue, the high-margin end, grew 37% and reached 29% of the mix. The shares cost 13.4x forward earnings against 13.5x trailing, which is no growth premium at all.
Only Genpact has moved off the headcount meter
Two of the four earned their re-ratings with results. ExlService because analytics and data engineering bill at nearly twice a contact seat, ibex because a six-week deployment bought it an incumbent's volume. TaskUs's advance rests on a guidance raise and a cheap multiple while the income statement deteriorates. Concentrix's rests on cash: $218m of adjusted free cash flow in the quarter and $550m or more of annual gross debt paydown targeted through 2027, against a top line consensus has flat to 2029.
The pricing migration the whole thesis needs has one listed example on the shelf's edge. "Non-FTE revenue exceeded 55% of total revenue in Q3, and our revenue growth continues to decouple from headcount," Genpact chief executive BK Kalra said on 5 November, with gross margin at 38.0% against 36.4% a year earlier. Everest Group describes the new billing units, per journey, per bot-hour, customer-experience-as-a-service, as beginning to emerge. Emerging is the right word: ExlService puts its own payment-integrity shift a couple of years out and calls the timing "unclear and unsettled".
So in this corner of services AI has become a question of which provider holds the account when volumes move, while the hour remains the thing counted on the invoice. The companies whose revenue per employee has pulled away are the ones that found something else to sell, and the next three quarters will show whether anyone can charge for a resolved problem at scale.