

Keysight's Orders Grew 56% on AI Test Demand, and That Exposure Is Why Its Shares Fell
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Keysight booked more orders than it shipped last quarter and has since lost more than a quarter of its market value, with no guidance change, no export-control action and no contract loss to explain it. Orders reached $2,091m against $1,846m of revenue, and reported revenue growth accelerated through the fiscal year to 36.5%.
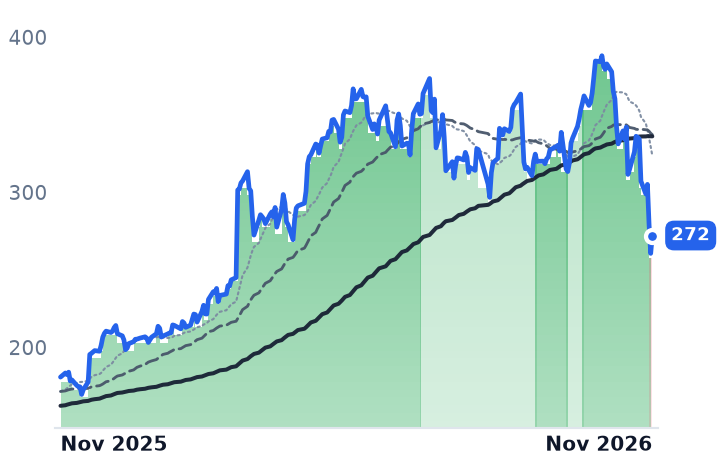
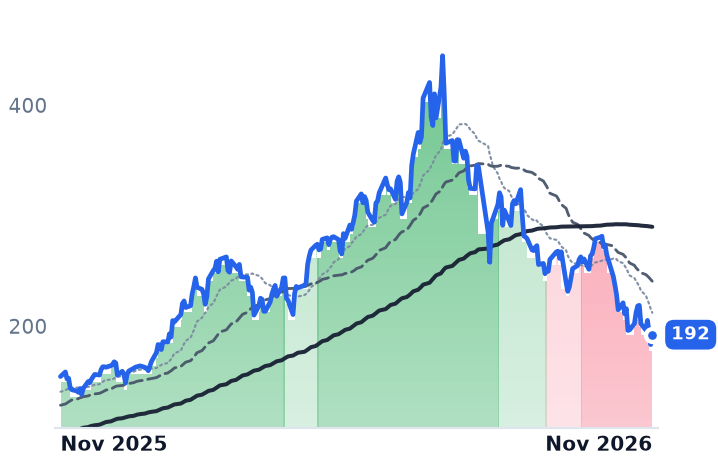
Inside the same test-instrument group, the markdown sorted by how much artificial-intelligence revenue each name carries. Fortive, whose Fluke franchise management puts at low single digits of sales for data centers, rose 14% over the 30 days to 6 November; Keysight, whose AI business ran at $500m-$600m in the first half, fell 28.6%. Ralliant and Teledyne both raised full-year guidance inside the window.
Keysight's forward earnings multiple compressed to 19.7x from roughly 27.7x a month earlier. The business explains none of the move; the AI label explains most of it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
KEYS | Keysight Technologies | Test & Measurement | 🟢 Cont. Bull | −28.2% | +50.5% |
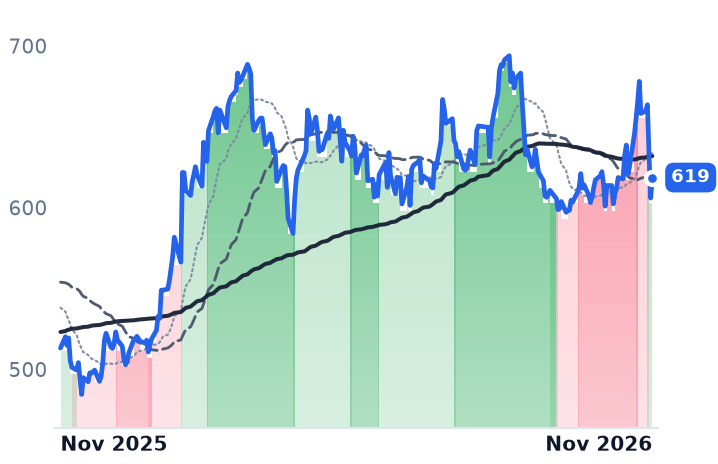
TDY | Teledyne Technologies Incorporated | Test & Measurement | ⚠️ Emerging Bear | +2.9% | +20.5% |
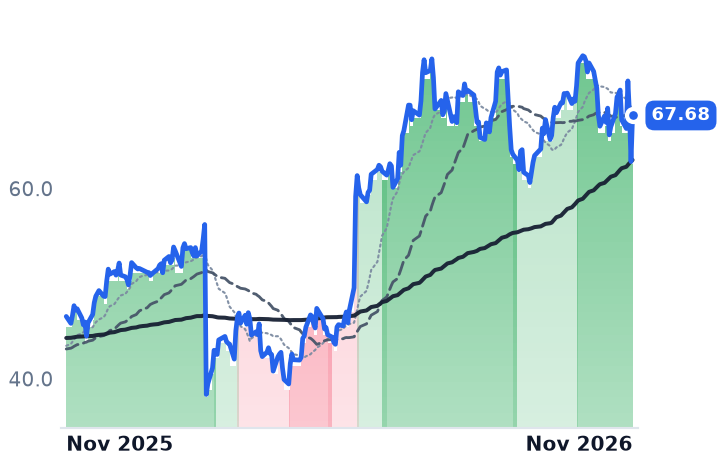
RAL | Ralliant | Test & Measurement | 🟢 Cont. Bull | −6.3% | +45.4% |
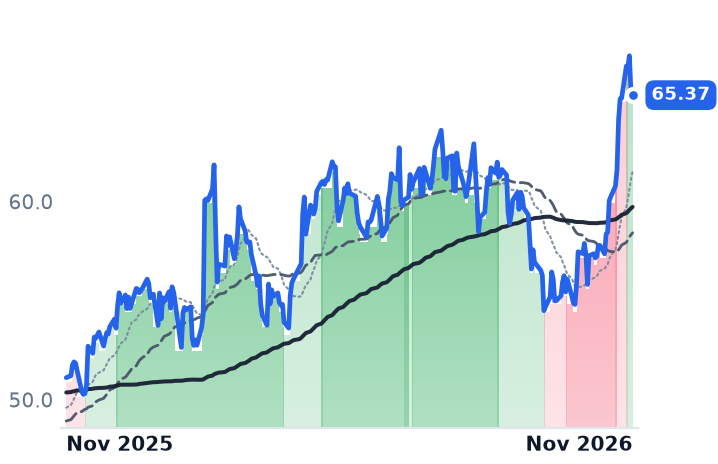
FTV | Fortive | Test & Measurement | 🟢 Cont. Bull | +17.1% | +27.9% |
MKSI | MKS | Test & Measurement | ⚠️ Emerging Bear | −29.6% | +24.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KEYS | $46.3B | 37.4x | 19.7x | 7.0x | 5.7x | 10.9x | 8.8x | 25.0x | 3.2% |
TDY | $28.7B | 28.3x | 24.2x | 4.4x | 4.3x | 11.4x | 11.2x | 18.3x | 4.0% |
RAL | $7.5B | n/m | 22.5x | 3.3x | 3.2x | 6.5x | 6.4x | n/m | 4.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FTV | $19.5B | 30.8x | 21.2x | 4.4x | 4.4x | 7.0x | 6.9x | 17.1x | 5.6% |
MKSI | $13.0B | 21.5x | 14.6x | 2.7x | 2.6x | 6.1x | 5.7x | 13.5x | 4.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
KEYS | Revenue | +33.3% | +14.7% | +8.3% |
| EPS | +61.9% | +20.2% | +11.8% | |
TDY | Revenue | +9.2% | +6.1% | +4.5% |
| EPS | +18.5% | +8.6% | +6.4% | |
RAL | Revenue | +12.7% | +7.6% | +4.9% |
| EPS | +12.6% | +18.1% | +16.0% | |
FTV | Revenue | +7.0% | +3.8% | +4.1% |
| EPS | +16.8% | +7.3% | +7.9% | |
MKSI | Revenue | +29.7% | +20.5% | +10.3% |
| EPS | +67.2% | +33.9% | +14.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Keysight Technologies took in more orders last quarter than it shipped: roughly $2.1bn against $1.8bn of revenue. The orders were up 56% from a year earlier and were the second consecutive quarter above $2bn for the company, which sells oscilloscopes, radio-frequency and optical test systems and design software to communications, defense, automotive and semiconductor engineers. Since early October the shares have lost more than a quarter of their value, with no guidance change, no contract loss and no regulatory action attached to the company.
General-purpose instruments are supposed to be the insulated corner of the electronics complex: they are paid for out of engineering and research budgets at design time, well before anyone pours concrete for a data center. The past month tested that belief inside a single group of vendors, and the result was not flattering to it. What determined whether a test-instrument maker was marked down was how much AI revenue its name carried, not how its order book was running.
The half of Keysight nearest the buildout is the half growing
Keysight's Communications Solutions Group did $1,345m of revenue in the quarter ended 31 July, up 43%, on 56% growth in commercial communications and 14% in aerospace, defense and government. The Electronic Industrial Solutions Group did a record $501m, up 21%. Gross margin reached 65.9% against 61.7% a year earlier, and operating margin 25.0%.
"The scaling challenges associated with AI data center deployments are driving a multiyear industry road map for new architectures, evolving technologies and new standards," chief executive Satish Dhanasekaran said on the August 18 earnings call. On the same call he sized the AI business at the "$500 million-$600 million range" for the first half of the fiscal year and said it was "largely in the wireline segment," where orders more than doubled.
Two things complicate the growth. Reported revenue is flattered by the $1,415m purchase of Spirent Communications, net of cash acquired, closed in the prior fiscal year's fourth quarter. And the recurring mix thinned: software and services were about 33% of revenue against 36% a quarter earlier, with annual recurring revenue at 24% against 27%, diluted by hardware growing faster than either.
The de-rating is wide. Keysight trades at 19.7x the $13.77 of fiscal-2027 consensus earnings per share, against roughly 27.7x on the same estimate at the October 7 close, and 37.4x trailing against 59.2x in May 2026.
Fluke's owner went up through the same sessions
Fortive, which owns the Fluke handheld-instrument and calibration business, is the counter-case within the group. Core growth at its Intelligent Operating Solutions segment accelerated to 9% in the third quarter, Fluke orders accelerated and book-to-bill held above 1.0 on data-center, defense and technician demand. Management put data-center revenue at only low single digits of sales. "We are supply constrained, frankly, at this point in terms of the talent and the capacity we want to build, because the market is certainly there for us," chief executive Olumide Soroye told investors on October 28, describing a specialized data-center sales team for Fluke. Fortive raised full-year earnings guidance to $3.10-$3.14 and rose 14.0% over the 30 days to November 6. It trades at 21.2x forward earnings against 30.8x trailing.
Ralliant raised guidance and was sold twice
Ralliant, the Tektronix and Keithley owner spun out of Fortive this year, grew its Test and Measurement segment 21% organically to $244m with segment margin up 670 basis points to 19.3%. The composition matters: diversified electronics up 48%, communications up 4%, semiconductor down 7%. Book-to-bill ran above 1.1 in both segments, and management reported channel inventory clearing on sell-through. In September Tektronix launched a fully regenerative dynamic test rig scaling to 1.92 megawatts to validate the 800-volt direct-current power architectures appearing in AI data centers by emulating graphics-processor load swings.
Ralliant raised 2026 guidance on November 4 to $2.34bn-$2.36bn of revenue and $3.10-$3.16 of earnings per share, with net leverage at 1.5x. The shares fell 4.8% that day and 7.5% the next. On the raised midpoint the forward multiple is about 21.6x. One caveat belongs beside the margin: a $7m tariff refund was worth 115 basis points of the reported gross-margin gain, and management said roughly $14m of such refunds will not repeat next year.
Teledyne's instruments line disagrees with its own order book
Teledyne held its price, and its results undercut any claim that these four businesses move for a single reason. Its electronic test and measurement revenue declined 6.3% in the September quarter on order timing, even as orders there rose 18% to a record 1.23 times billings. The growth carrying the company comes from elsewhere: Digital Imaging up 14.3% organically, with infrared detectors for space imaging up more than 25%, and defense electronics up 7.4%. "Our third quarter sales and operating earnings were the strongest in Teledyne's history," executive chairman Robert Mehrabian said on October 21, raising full-year guidance for the third consecutive quarter. The stock rose 0.7% over the 30 days and sits at 24.2x forward earnings against 28.3x trailing; it never got expensive and it never fell.
What the results account for, and what they do not
Nothing in the reported numbers accounts for Keysight's drawdown. Two of these four companies raised full-year guidance inside the window, the third set its guidance in August and has not touched it, and nobody disclosed a channel inventory build. The drawdown instead lands on a handful of sessions with named market-wide causes: October 22, when Lam Research's warning about 2027 supply-chain constraints pulled the Nasdaq Composite down 2.18%, and November 5, when that index fell 5.5% and roughly $3tn of S&P 500 market value was erased on doubts that hyperscaler capital spending converts to cash flow.
So a pricing event in the AI complex passed through a group of instrument vendors in proportion to their AI labels. The open question sits on the other side of the ledger: consensus has Keysight growing revenue 14.7% next fiscal year after 33.3% this one, which already assumes the order surge fades, and the wireline AI business carrying that surge is concentrated among a handful of hyperscale customers. An order book running 1.13 times billings is a claim about the next two quarters, not the next five years.
Keysight reports again on November 19. The order line, which has now run ahead of revenue for two consecutive quarters, is where a reader will learn whether the past month was ever about instruments.