

Okta Doubled on Margins, Not Growth; Rubrik's Meter Is the One Accelerating
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
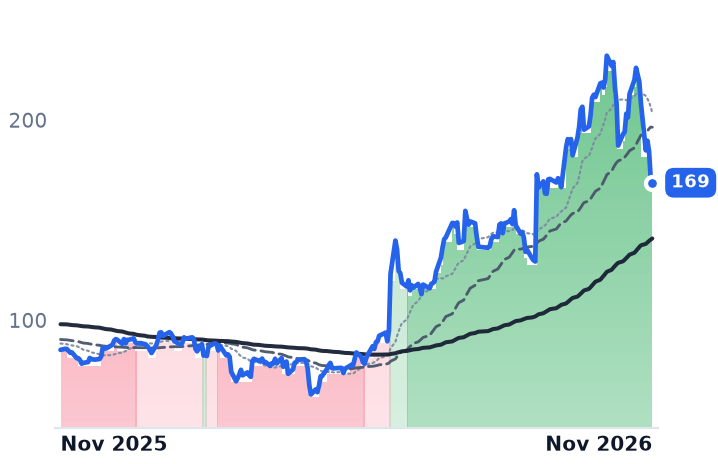
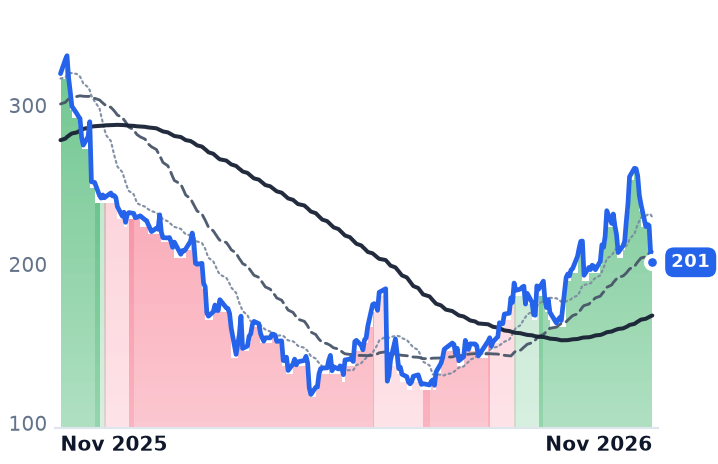
Two security-software names held their uptrends through a brutal week for infrastructure software, and the market has paid up for the weaker contracted book. Okta's revenue growth slowed for a fourth consecutive quarter, to 10.6%, while its shares more than doubled over six months; the confirming line is margin, with operating income up 161% and free cash flow at a 28% margin.
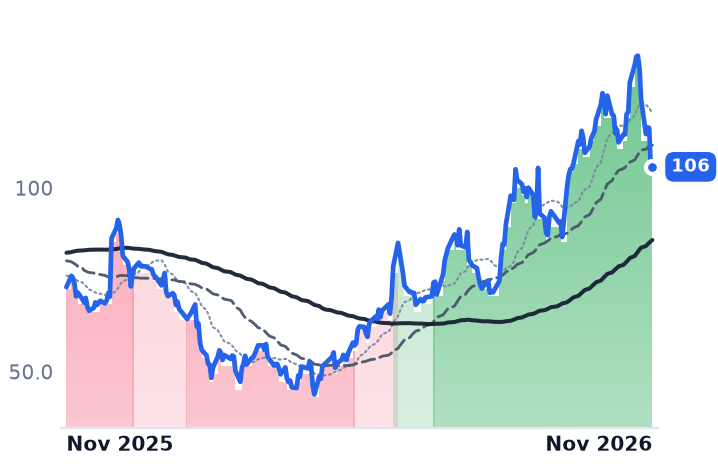
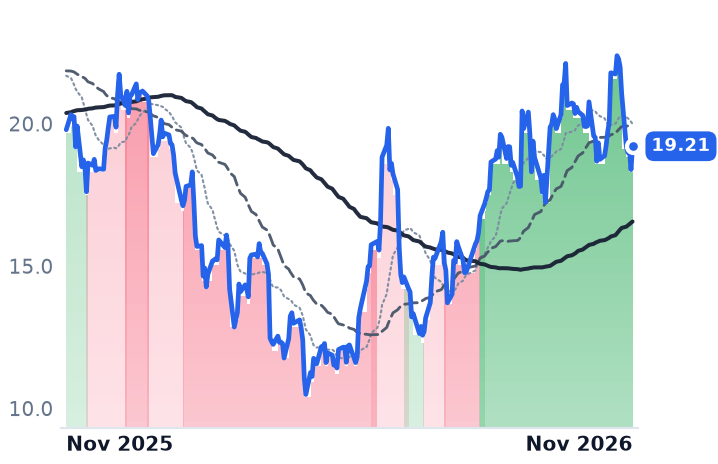
Rubrik, billed on data under management rather than per user, grew subscription annual recurring revenue 33% to $1.66bn with net retention above 119%, against flat 107% retention and 14% contracted-revenue growth at Okta, guided back down to 11-12%. The agentic story both rallied on sits in neither revenue line: Okta's finance chief called agent revenue immaterial for this fiscal year.
Rubrik has the better meter and the dearer price, at 17.60x trailing gross profit against Okta's 11.74x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
OKTA | Okta | Identity & Access Management | 🟢 Cont. Bull | −23.4% | +98.0% |
RBRK | Rubrik | Storage, Backup & Data Management | 🟢 Cont. Bull | −11.9% | +44.8% |
| Compared against · context, not the story | |||||
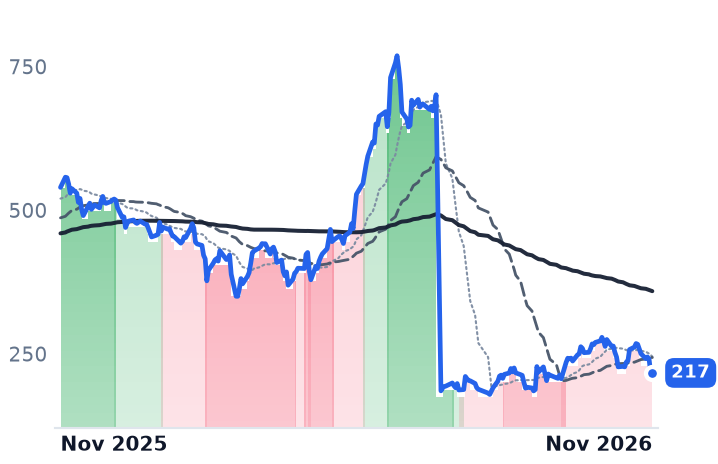
CRWD | CrowdStrike | Cybersecurity & Threat Protection | 🔴 Cont. Bear | −17.5% | −59.8% |
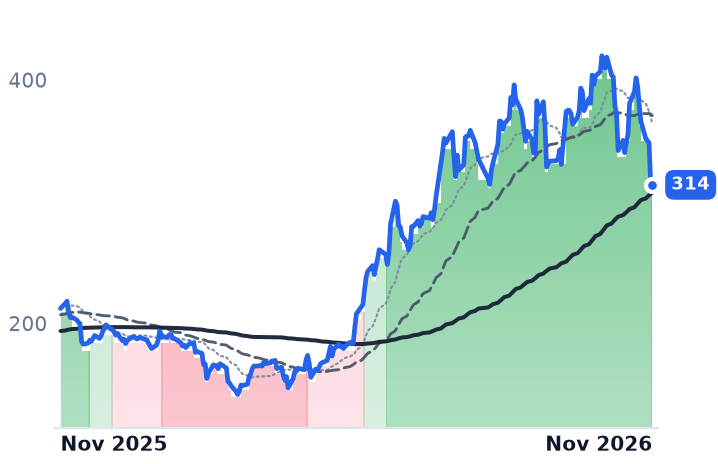
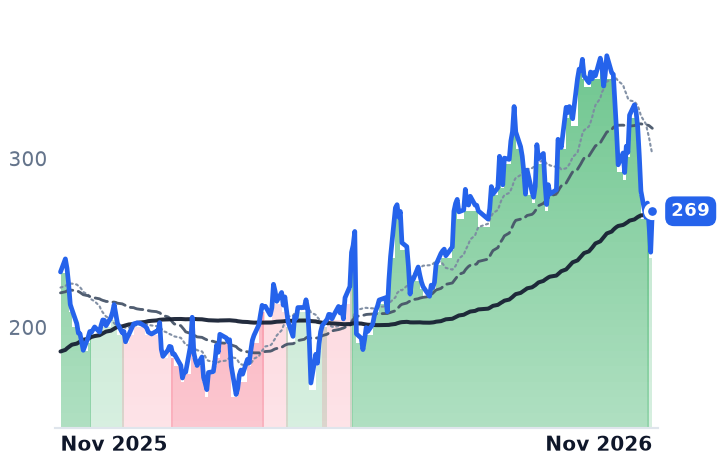
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🟢 Cont. Bull | −23.4% | +47.8% |
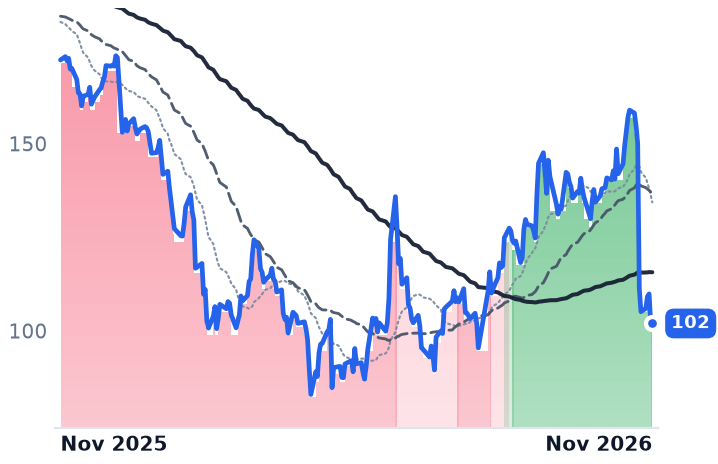
ZS | Zscaler | Cybersecurity & Threat Protection | 🌱 Emerging Bull | −7.6% | −37.1% |
SAIL | SailPoint | Identity & Access Management | 🟢 Cont. Bull | −3.6% | −2.9% |
NET | Cloudflare | Cybersecurity & Threat Protection | 🟢 Cont. Bull | −23.1% | +15.4% |
NOW | ServiceNow | Sales, Service & Customer Management | 🟢 Cont. Bull | −26.3% | −40.8% |
SNOW | Snowflake | Data, Analytics & Intelligence | 🟢 Cont. Bull | −20.6% | +3.1% |
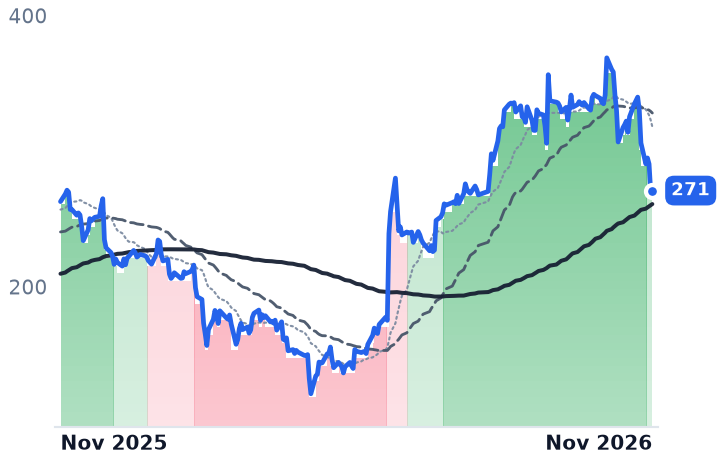
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKTA | $28.2B | 99.8x | 42.9x | 9.2x | 8.7x | 11.7x | 11.2x | 66.7x | 3.4% |
RBRK | $21.8B | n/m | 210.2x | 14.1x | 12.9x | 17.6x | 16.1x | n/m | 1.5% |
CRWD | $222.1B | — | 173.0x | 41.2x | 37.0x | 54.7x | 49.1x | 498.8x | 0.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PANW | $256.9B | 682.3x | 75.0x | 22.4x | 18.1x | 31.8x | 25.8x | 166.8x | 1.6% |
ZS | $31.9B | n/m | 40.4x | 9.5x | 8.1x | 12.4x | 10.6x | 176.0x | 2.7% |
SAIL | $11.5B | n/m | — | 9.9x | — | 14.9x | — | n/m | 1.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NET | $128.1B | n/m | 286.2x | 51.0x | 44.7x | 70.3x | 61.5x | — | 0.3% |
NOW | $105.8B | 72.8x | 25.8x | 6.9x | 6.5x | 9.4x | 8.9x | 32.6x | 4.5% |
SNOW | $114.0B | n/m | 148.5x | 21.0x | 18.0x | 31.3x | 26.9x | n/m | 1.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
OKTA | Revenue | +12.0% | +10.8% | +9.9% |
| EPS | +24.3% | +14.1% | +10.6% | |
RBRK | Revenue | +48.7% | +32.0% | +21.5% |
| EPS | −90.5% | −389.4% | +53.1% | |
CRWD | Revenue | +22.2% | +25.0% | +22.9% |
| EPS | −1.2% | +35.0% | +27.9% | |
PANW | Revenue | +24.3% | +24.0% | +14.3% |
| EPS | +15.5% | +10.7% | +16.1% | |
ZS | Revenue | +25.2% | +17.9% | +16.3% |
| EPS | +29.2% | +18.3% | +14.7% | |
NET | Revenue | +33.7% | +28.4% | +27.0% |
| EPS | +38.1% | +32.6% | +34.3% | |
NOW | Revenue | +22.6% | +18.5% | +18.1% |
| EPS | +13.5% | +21.6% | +22.2% | |
SNOW | Revenue | +29.4% | +35.7% | +28.9% |
| EPS | +72.3% | +82.7% | +36.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Okta's revenue growth has decelerated for four consecutive quarters, and the shares still more than doubled in the six months to 6 November. Revenue at the identity company, which sells single sign-on, multi-factor authentication and the acquired Auth0 developer portfolio to enterprises and governments on annual subscriptions, rose 10.6% year over year in the July quarter, the slowest of the four. What moved was margin: gross margin reached 79.6% against 76.9% a year earlier, operating margin 13.3% against 5.6%, and operating income grew 161%.
The advance in Okta and in Rubrik, which sells cyber-recovery software priced on the volume of data under management rather than per user, has been read as proof that identity and backup are the meters agentic AI feeds: every autonomous agent has to authenticate like an employee, and everything it writes has to be recoverable, while workflow software loses human seats. Neither income statement carries that revenue yet. Asked about agent-identity revenue on the 26 August call, Okta chief financial officer Brett Tighe answered "Still immaterial," and said AI-related revenue stays immaterial through fiscal 2027 with a meaningful contribution possible only in fiscal 2028 and beyond, according to the company's transcript. Okta for AI Agents went generally available on 30 April and has closed dozens of deals, several of them worth more than $1m.
Okta's order book is being guided down, not up
Current remaining performance obligation, the contracted revenue Okta expects to recognize within a year and the closest thing it prints to a forward order book, reached $2.585bn, up 14%, ahead of billed revenue. Management guided that growth back to 11-12% for the following quarter. Trailing net retention was flat at 107%. Customers paying more than $100,000 a year grew 6%, to 5,255, while those above $1m grew 22% to more than 600, so the base is concentrating rather than widening. Free cash flow was $227m, a 28% margin against 22% a year earlier. Consensus carries 9.9% revenue growth for the year to January 2028.
The fast-growing bookings line Okta does disclose is a different product set: governance, privileged access and threat protection were 30% of bookings in the quarter at roughly 40% average uplift per deal, up from about 25% in the April quarter. Agent sign-on was folded into the core product at the Oktane conference in September rather than sold as a separate machine-identity line, and chief executive Todd McKinnon told that audience on 23 September that in agent identity "there is going to be massive growth and the market share is going to be set probably in three years."
Rubrik's contracted book accelerated in the same quarter
Rubrik's subscription annual recurring revenue grew 33% to $1.66bn at 31 July, with net new subscription ARR up 35% and subscription net retention above 119%. Customers paying $100,000 or more rose 23% to 3,084 and supply 88% of subscription ARR; cloud is 89% of the mix and grew 39%. Dividing those disclosures gives roughly $474,000 of ARR per large customer against about $438,000 a year earlier, so most of the 33% is landing and graduating big accounts and about a quarter of it is deeper spend inside them.
The income statement is the weaker half. Revenue growth decelerated to 37.9%, gross margin slipped to 78.4% from 79.5% so gross profit grew more slowly than revenue, and the GAAP operating margin was still minus 16.8% on a $61.8m quarterly loss. Rubrik is also not the share leader in backup: Gartner's 2026 Magic Quadrant places Veeam, Rubrik, Commvault and Cohesity in the Leaders quadrant with Veeam ahead, and Veeam reported over $2.1bn of ARR for 2025. Its own agentic product, Code Guardian, which runs Anthropic's Claude through a security harness against cloned copies of customer code repositories, was expanded on 9 October and remains in private preview.
The faster meter carries the dearer price
Rubrik trades at 17.60x trailing gross profit, against 10.48x in early May and 15.59x in early September. It is the one multiple in the pair that kept expanding through the autumn drawdown, and it expanded faster than the 36% growth in gross profit underneath it. Okta's equivalent is 11.74x, more than double its early-May level near 5x but below 13.50x on 25 September. On forward revenue Okta stands at 8.75x against roughly 6.9x in mid-July, when the shares were $139.53.
Both gave back a fifth or more of the advance in October and November. Okta closed 27.3% below its 9 October high of $232.13 and Rubrik 22.2% below its 28 October high of $136.00, with the sharpest session on 5 November, when the Nasdaq Composite fell 5.52% on doubts about AI data-center spending and the whole security complex sold together. No company news for either name was discoverable in that window. Okta fell 11.2% on 2 November, three days after S&P Dow Jones Indices said it would join the S&P 500. Both have held uptrends since June, which Palo Alto Networks and ServiceNow lost in that single November session; Zscaler, billed per user per year, held one too, so survival does not sort by pricing basis. CrowdStrike, billed per endpoint, grew revenue 25.8% with record net new ARR up 51% in its July quarter, faster than either protagonist's contracted book.
Strip the agent premium out of both and what is left is one accelerating meter and one fading one. Okta's margins account for the profitability half of its doubling and nothing of the growth half, because its base is human seats sold against Microsoft's bundled Entra, where 107% retention is what a mature directory earns. Rubrik's 119% retention compounds instead, because protected capacity inside an account grows whether or not the headcount does, and that is the business the market has priced the more expensively of the two.
The test arrives in the same week for both. Okta reports third-quarter results on 1 December and Rubrik on 3 December, which settles the question of whose quarter had merely printed first.