

Modine's First $1bn Order Quarter for Data-Center Cooling Cost It a Third of Its Profit
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Modine has never taken in as many orders as it did last quarter, and it has never converted them so poorly. Data-center revenue grew 95% year-over-year, the Americas business 132%, and net income still fell to $30.0m on revenue up 35%.
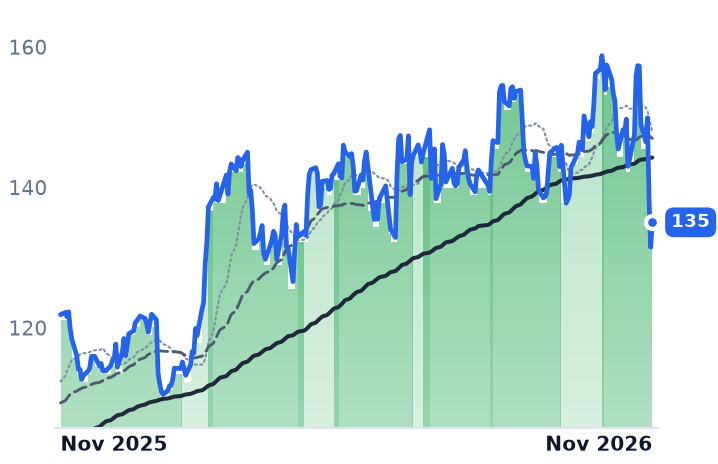
That is the test of the belief that cooling vendors are AI infrastructure companies rather than construction cyclicals. The demand half holds: Trane's commercial HVAC backlog reached $12.5bn, up more than 70%. The profit half does not. Modine, Trane and AAON each lost gross margin in their most recent reported quarter, and Modine's shares now fetch 6.5x trailing gross profit against 12.9x in mid-October. Watts Water is the exception, expanding operating margin by 240 basis points on the same end market.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
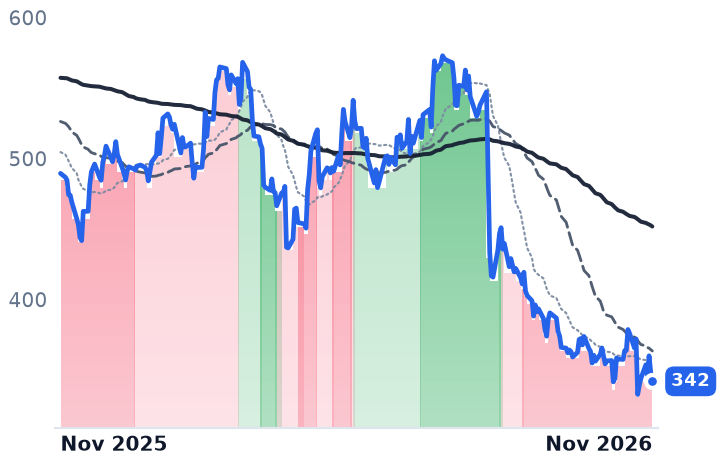
MOD | Modine Manufacturing | HVAC & Refrigeration Systems | 🔴 Cont. Bear | −46.8% | −38.2% |
TT | Trane Technologies | HVAC & Refrigeration Systems | ⚠️ Emerging Bear | −14.5% | −7.3% |
AAON | AAON | HVAC & Refrigeration Systems | 🔴 Cont. Bear | −34.3% | −45.7% |
WTS | Watts Water Technologies | HVAC & Refrigeration Systems | 🟢 Cont. Bull | +1.2% | +27.1% |
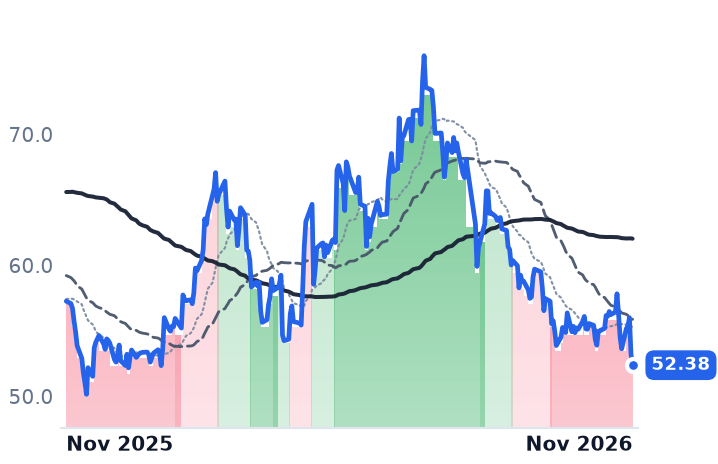
XYL | Xylem | Pumps, Valves & Filtration | 🔴 Cont. Bear | −3.1% | −34.9% |
ROP | Roper Technologies | Enterprise Resource Planning | 🟢 Cont. Bull | +34.0% | +7.4% |
SPXC | SPX Technologies | HVAC & Building Systems | 🔴 Cont. Bear | −15.5% | −35.7% |
JCI | Johnson Controls International | HVAC & Building Systems | 🟢 Cont. Bull | −12.3% | +10.8% |
CARR | Carrier Global | HVAC & Refrigeration Systems | 🔴 Cont. Bear | −5.0% | −8.5% |
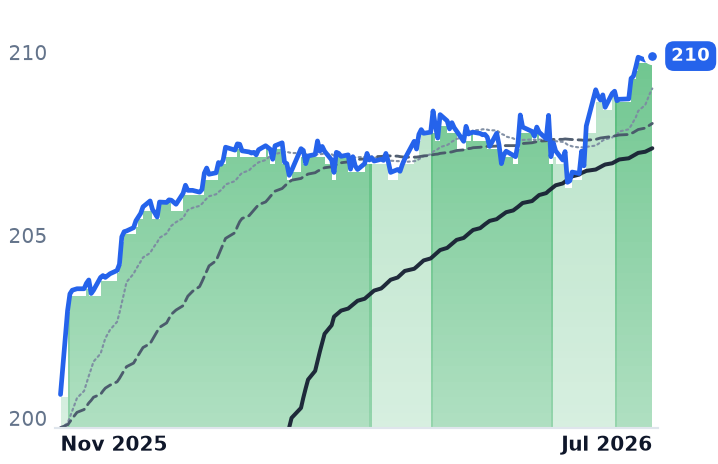
GTLS | Chart Industries | Filtration & Separation | 🟢 Cont. Bull | — | +4.6% |
| Compared against · context, not the story | |||||
VRT | Vertiv | Advanced Power Systems | ⚠️ Emerging Bear | −26.4% | +1.8% |
LII | Lennox International | HVAC & Refrigeration Systems | 🔴 Cont. Bear | −3.5% | −30.1% |
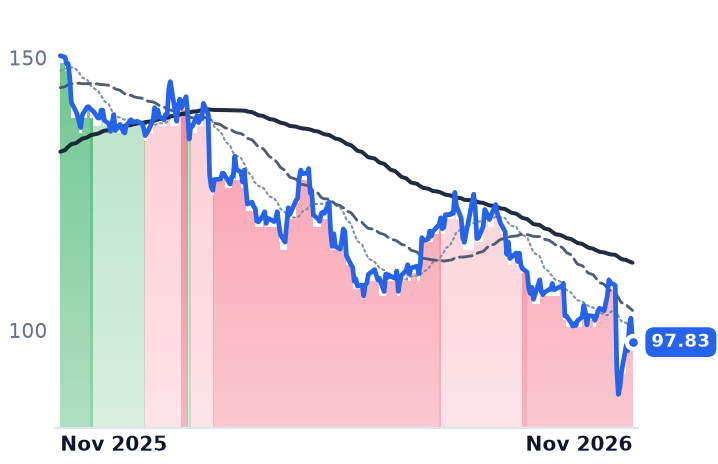
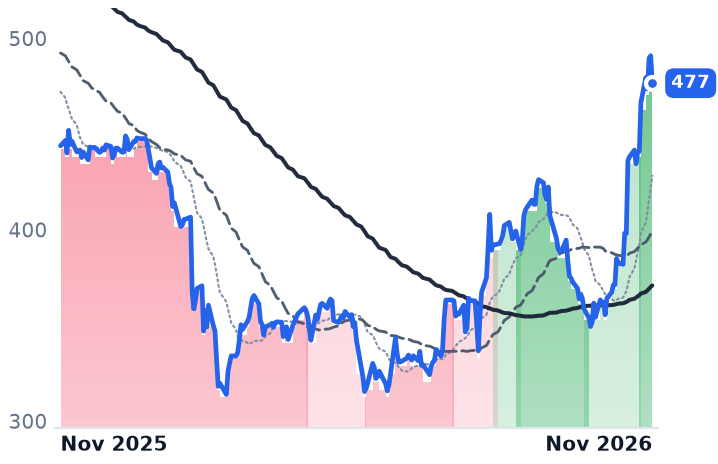
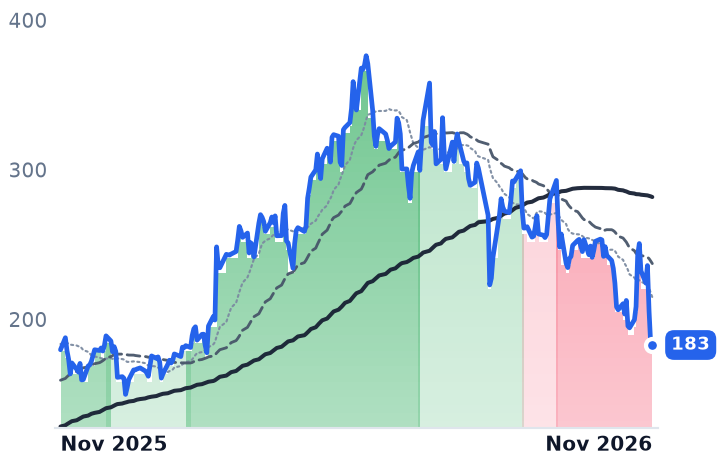
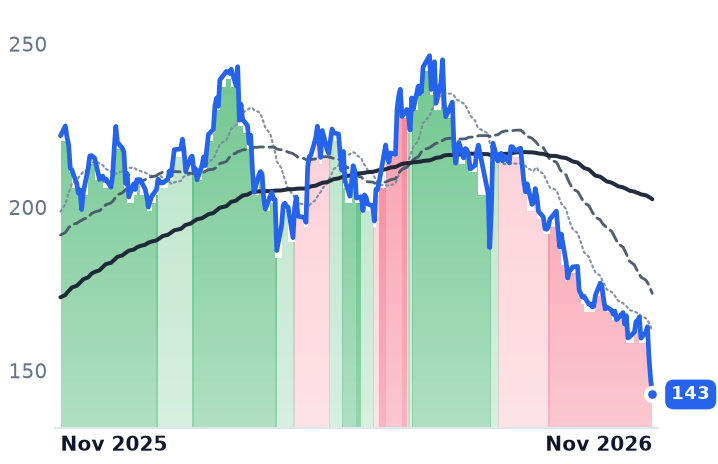
12-month price & trend
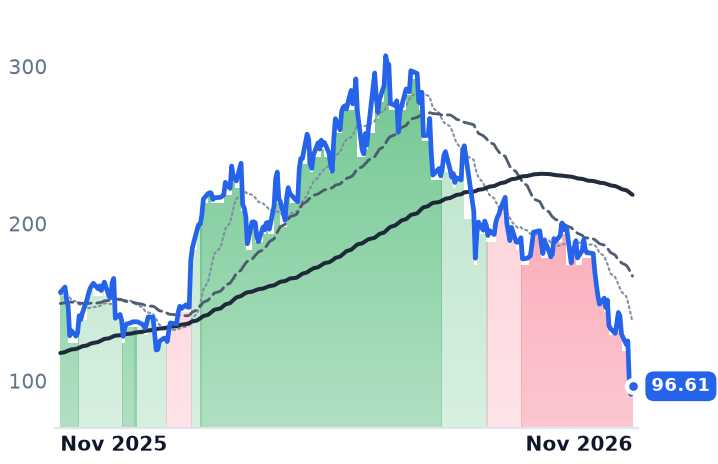
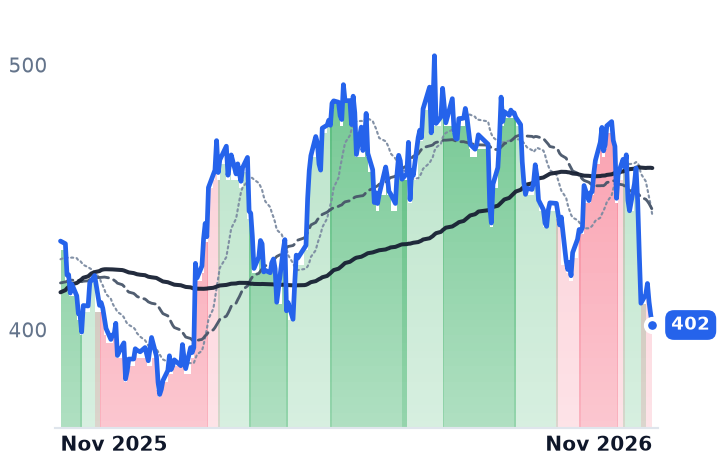
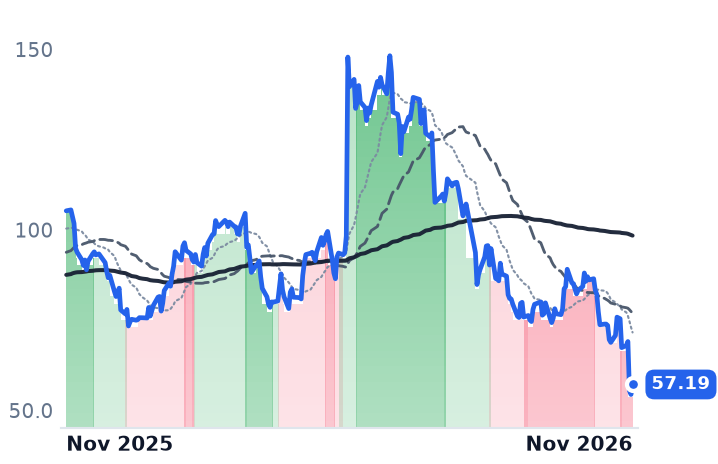
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MOD | $5.1B | 40.4x | 13.4x | 1.4x | 1.6x | 6.5x | 7.2x | 17.8x | -0.7% |
TT | $87.9B | 28.3x | 26.3x | 3.8x | 3.6x | 10.8x | 10.4x | 20.5x | 4.3% |
AAON | $4.7B | 29.5x | 24.1x | 2.4x | 2.0x | 9.5x | 8.0x | 17.3x | -2.5% |
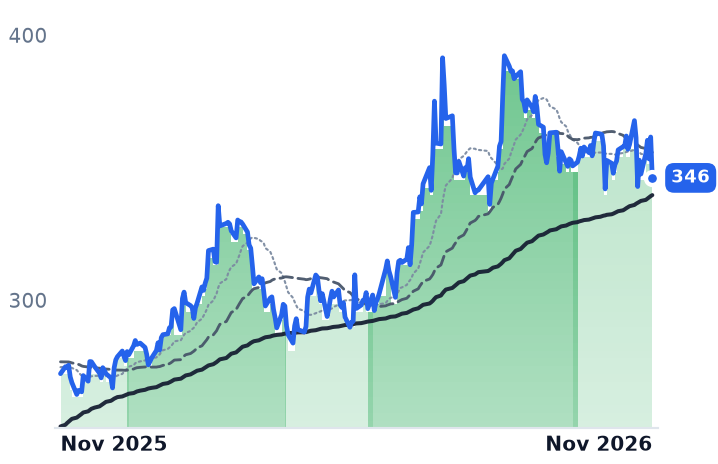
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WTS | $11.6B | 25.9x | 26.8x | 4.1x | 4.1x | 8.2x | 8.1x | 17.0x | 3.2% |
XYL | $22.4B | 21.6x | 18.0x | 2.5x | 2.5x | 6.2x | 6.3x | 12.7x | 4.1% |
ROP | $47.2B | 18.8x | 21.3x | 5.6x | 5.5x | 8.0x | 7.9x | 12.9x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
SPXC | $7.2B | 23.9x | 17.0x | 2.8x | 2.6x | 6.9x | 6.5x | 14.8x | 3.2% |
JCI | $81.8B | 28.8x | 21.5x | 3.2x | 2.9x | 8.6x | 7.8x | 21.9x | 4.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CARR | $42.9B | n/m | 18.3x | 1.9x | 1.8x | 7.6x | 7.3x | 223.3x | 5.5% |
LII | $11.8B | 15.9x | 15.9x | 2.2x | 2.1x | 6.6x | 6.6x | 12.0x | 7.1% |
GTLS | $10.0B | n/m | 30.1x | 2.4x | 2.5x | 7.7x | 7.8x | 26.0x | 0.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MOD | Revenue | +22.6% | +4.9% | +34.9% |
| EPS | +33.4% | +51.0% | +36.1% | |
TT | Revenue | +13.5% | +10.5% | +8.8% |
| EPS | +17.4% | +16.1% | +15.0% | |
AAON | Revenue | +65.9% | +17.6% | +16.0% |
| EPS | +68.5% | +51.5% | +26.4% | |
WTS | Revenue | +17.0% | +5.8% | +5.0% |
| EPS | +25.2% | +9.3% | +9.1% | |
XYL | Revenue | −0.5% | +3.5% | +5.2% |
| EPS | +7.6% | +7.6% | +10.8% | |
ROP | Revenue | +8.1% | +6.1% | +5.7% |
| EPS | +12.3% | +9.9% | +8.2% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
SPXC | Revenue | +23.3% | +15.6% | +9.4% |
| EPS | +24.7% | +16.3% | +12.8% | |
JCI | Revenue | +9.0% | +10.3% | +9.0% |
| EPS | +36.9% | +23.4% | +18.3% | |
CARR | Revenue | +8.7% | +6.0% | +6.1% |
| EPS | +10.2% | +11.0% | +13.7% | |
LII | Revenue | +4.4% | +5.3% | +4.5% |
| EPS | −5.7% | +7.9% | +9.1% | |
GTLS | Revenue | −6.0% | +4.7% | +3.9% |
| EPS | −37.2% | +13.9% | +19.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Modine Manufacturing, the Racine, Wisconsin maker of chillers, coils, air handlers and precision cooling equipment for data centers, told investors on November 4 that it had taken in more than $1bn of orders in a single quarter for the first time in its history. Data-center revenue grew 95% year-over-year, the Americas business 132%, and backlog reached a record. Net income for the quarter was $30.0m, down 32% from a year earlier on revenue up 35% to $994.4m.
"We achieved our fourth consecutive quarter of record orders, exceeding $1 billion in quarterly order intake for the first time in our history," chief executive Neil Brinker said on the call. Demand, he added, "far exceeds our capacity." That combination is the whole argument over this group of companies. They were bought as derivatives of the artificial-intelligence buildout, on the premise that each megawatt of installed cooling carries more equipment content than the last. The orders vindicate that premise. What they have not done is arrive as profit, and the market has stopped paying for the first in advance of the second.
The content is real; the conversion is not
Modine's gross margin fell to 20.7% in the September quarter, roughly 160 basis points below the prior year, on material cost inflation, tariff-related logistics and operating inefficiencies tied to the rapid expansion of data-center cooling capacity. Chief financial officer Mick Lucareli sized the input problem at "about 375 basis points" in the quarter, against "at least, call it 250 basis points catch-up right now that we've gone" in agreed customer pricing, subject to contract-approval lags.
The segment itself is not the problem. Modine's data-center business earned a 15.4% adjusted margin on earnings before interest, taxes, depreciation and amortization, above the 13.7% group figure and above Commercial HVAC's 15.1%. The dollars per megawatt are accretive where they land. They are simply landing through thirteen operational chiller lines on the way to a target of twenty, a third dedicated plant launching in Calgary, and capital spending guided to $150-200m this fiscal year with more than $100m a year expected to persist into 2028.
Management raised full-year guidance to $3.1-3.2bn of sales and $470-500m of adjusted EBITDA, more than 50% growth, with data-center sales up 80-90%. Consensus sat at $3.302bn and $7.20 of earnings per share, above the top of the range management called a raise. That reconciles the two readings of the print circulating afterward.
Where the megawatt dollar actually goes
Mechanical and cooling equipment is 15% to 20% of total data-center capital expenditure, and rising. Liquid roughly doubles the bill: $8m to $14m per critical information-technology megawatt for a standard air-cooled facility against $17m to $25m fully fitted for direct-to-chip.
But the split inside that number matters more than its size. The rack-side coolant distribution unit, the pump-and-manifold skid that moves fluid to the processor, goes elsewhere: Vertiv took 29.4% of global liquid-cooled distribution-unit revenue in 2025 and holds agreements with Nvidia and six hyperscale cloud providers covering more than 50,000 units through 2028. Modine, Trane and AAON sell the facility-side heat-rejection loop around it. Modine's own direct-to-chip position remains prospective: it is producing sub-assemblies for data-center chillers and discussing a coils supply opportunity for liquid cooling and radiator systems, described on the call as future revenue.
Lennox rose on the day Modine fell a fifth
One reading of the selloff is that these are construction cyclicals that were mistaken for technology names. The November 4 session, when Democrats swept the midterms and Texas elected a governor who had campaigned for tougher limits on data-center development, says the opposite. Modine fell 21%, AAON 20%, Vertiv 13%, Johnson Controls 8% and cooling-tower maker SPX Technologies 6%. Lennox, a residential heating and cooling pure-play, rose 3.9%; Carrier rose 1.2%. What was sold was data-center exposure. The same pattern had appeared on October 30.
Trane Technologies, the $88bn Irish-domiciled maker of chillers, rooftop units and Thermo King transport refrigeration, shows the fundamental version of the same squeeze. Commercial HVAC backlog hit $12.5bn, up more than 70%, with Americas applied bookings up 40% across 1,700 tracked mega-projects, predominantly data centers. "With backlog up more than 70% from the prior year, we are well-positioned for strong growth in 2027," chair and chief executive David Regnery said on October 29. The shares fell as much as 11% intraday to a seven-month low on an earnings beat, because the company cut its full-year pricing assumption to about one point from 1.5 and guided organic leverage down to the low twenties from 25%-plus. Its Stellar modular-chiller data-center line is tracking $500m of revenue this year at neutral earnings per share, targeting $1bn by 2028 at a mid-teens EBITDA margin, below the roughly 20% the enterprise earns. At 26.3x forward earnings against the 32x recorded in May, Trane's de-rating has a cause on the income statement.
AAON, the Tulsa maker of semi-custom rooftop units and purpose-built data-center cooling, has the starkest version. Annual gross margin was 34.1% in 2023 and 26.7% in 2025, and 24.3% in the June quarter, as data-center work displaced rooftop units; that quarter's revenue doubled and backlog rose 98% to $2.0bn. It has fallen 33% in thirty days without reporting anything: third-quarter results are scheduled for November 9. At 24.1x forward earnings it is the dearest of the three on that measure.
Watts Water Technologies, which sells backflow preventers, mixing valves and hydronic heating into buildings, is the one that kept what the others gave up. Data centers are now a high-single-digit percentage of revenue, mix is shifting toward liquid cooling, and September-quarter operating margin expanded 240 basis points to 20.9% with adjusted earnings per share up 36%. Its residential exposure is 25% of sales against 40% in 2022. "Regarding near-term demand, we're talking to our contractors and installers, and their book of business is solid for the next couple of years for sure," chief executive Robert Pagano said on November 5. Watts fell 3.4% over the same thirty days in which Modine fell 47%.
What 6.5 times gross profit assumes
The results explain the direction and not the distance. Modine trades at 6.5x trailing gross profit against 12.9x in mid-October, and at 13.4x forward earnings against 40.4x trailing, a spread that only resolves if something close to the guided EBITDA growth of more than 50% actually arrives. The margin shortfall behind the fall is genuine deterioration, not atmosphere: inputs rose faster than contracts could be repriced, and three plants were ramping at once.
What separates the names is who sets the price. Watts expanded margin because its mix moved toward higher-value product; Trane lost pricing power in short-cycle equipment and said so; Modine is carrying a two-quarter lag between cost and contract, with management guiding data-center margins up 100 to 200 basis points sequentially and above 20% in the fourth quarter. Those are three different mechanisms producing one chart. Vertiv, which owns the rack-side dollar these mid-caps are supposedly scaling past, fell 24.5% over the same thirty days, which weakens any account in which the air-side vendors were singled out.
Brinker noted something on the call that will matter more than the quarter: September was the first month every Modine chiller plant delivered on time, and October was the second. The orders were never the question.