

Vertex's Growth Now Comes From Tax Mandates Rather Than New Customers
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Three vendors of financial-services software reported inside four days, and the one with the least control over its own pricing was the only one to raise guidance. Vertex, which sells indirect-tax calculation software, lifted average revenue per customer 9.2% to $145,793 while total annual recurring revenue rose 11.7% — roughly four-fifths of the growth came from accounts already on the books pushing more invoices through, after France's e-invoicing mandate went live on 1 September.
Fair Isaac's full-year Scores revenue rose 41% on a mortgage price it has now frozen at $10 and a fiscal 2027 it declined to guide at all. BlackLine cut its revenue outlook and pushed paid agentic artificial intelligence to mid-to-end 2027.
The segment's one-month turn is narrow: four of nine names carried nearly all of it, and the median member moved a quarter of a percent.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
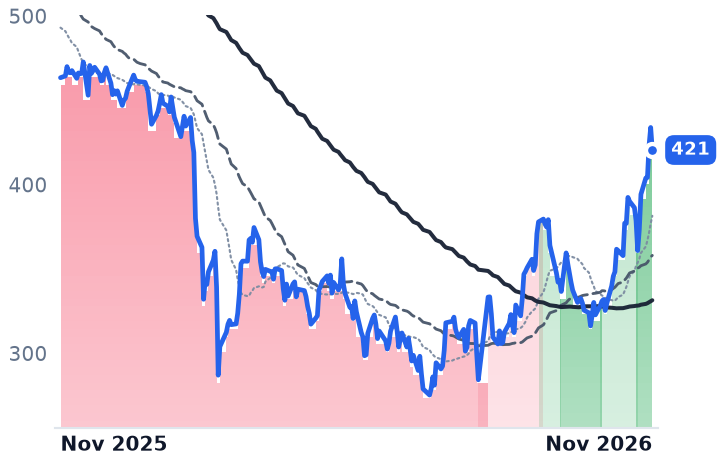
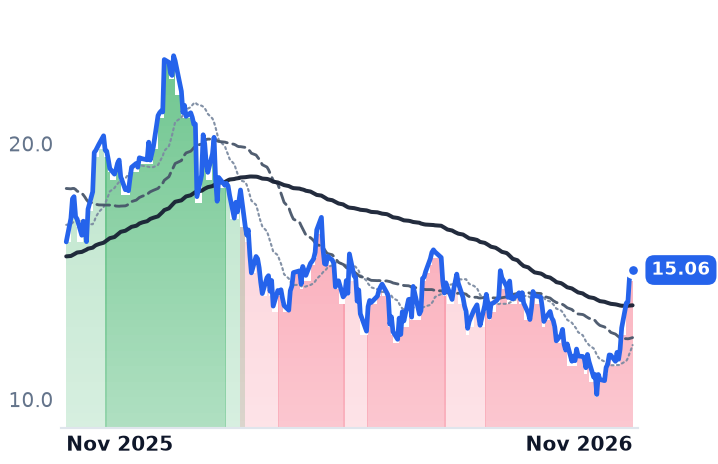
VERX | Vertex | Commerce & Digital Payments | 🌱 Emerging Bull | +38.5% | −12.5% |
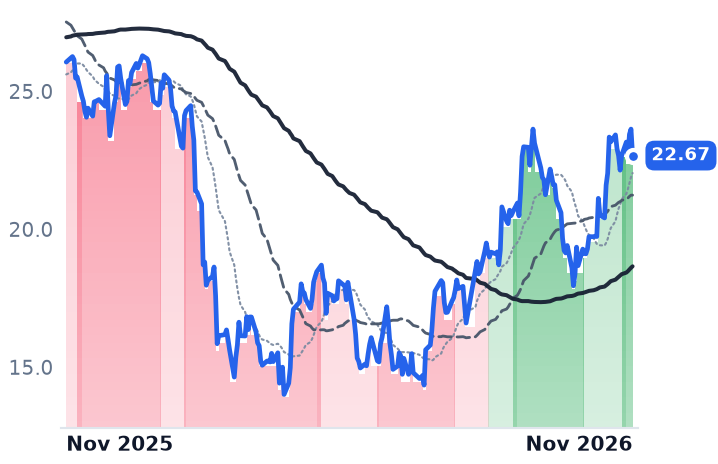
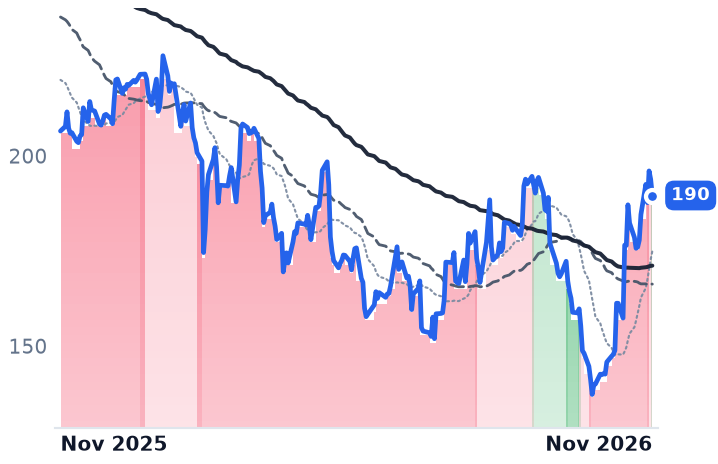
FICO | Fair Isaac | Data, Analytics & Intelligence | 🔴 Cont. Bear | +0.3% | −59.5% |
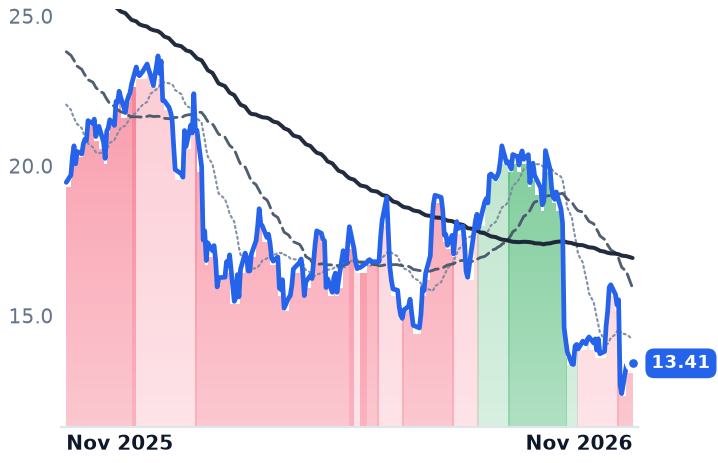
BL | BlackLine | Other | 🔴 Cont. Bear | −8.6% | −51.7% |
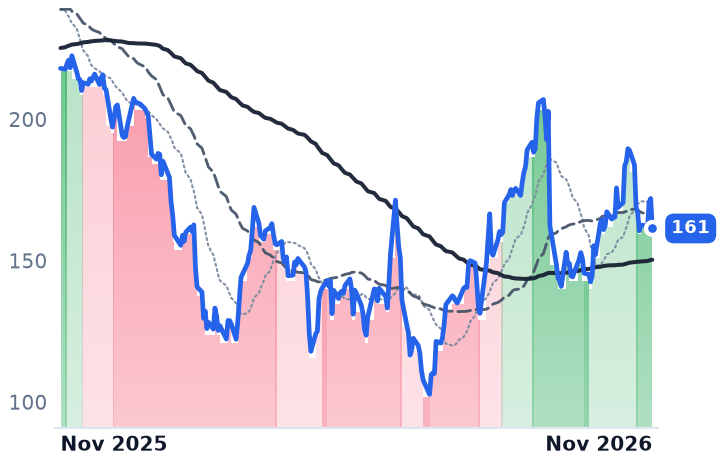
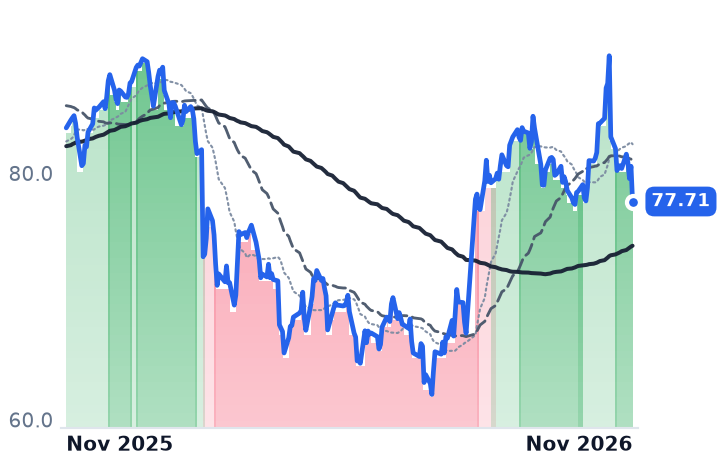
QTWO | Q2 | Commerce & Digital Payments | 🟢 Cont. Bull | +28.0% | +2.7% |
TYL | Tyler Technologies | Industry-Specific Platforms | 🌱 Emerging Bull | +29.2% | −9.3% |
NCNO | nCino | Commerce & Digital Payments | 🟢 Cont. Bull | +17.5% | −13.0% |
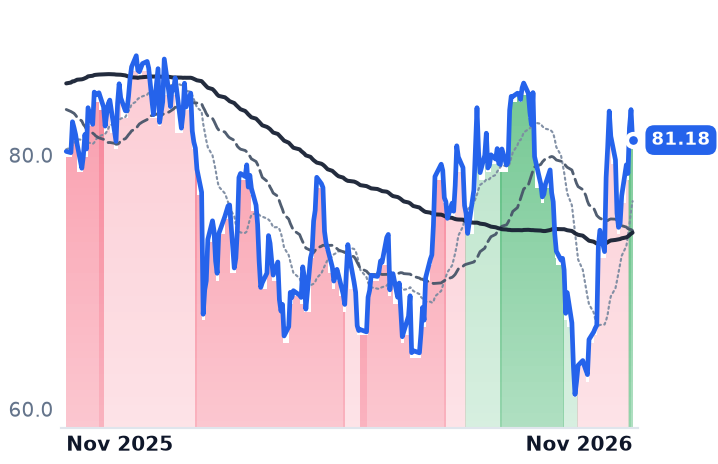
ALKT | Alkami Technology | Commerce & Digital Payments | 🔴 Cont. Bear | −5.7% | −31.1% |
GWRE | Guidewire Software | Industry-Specific Platforms | 🟢 Cont. Bull | −0.6% | −26.0% |
SSNC | SS&C Technologies | Enterprise Resource Planning | 🟢 Cont. Bull | −1.4% | −7.1% |
| Compared against · context, not the story | |||||
TRU | TransUnion | Consumer Credit Reporting | 🌱 Emerging Bull | +29.4% | +1.1% |
EFX | Equifax | Workforce Data & Analytics | 🔴 Cont. Bear | +32.9% | −8.2% |
RKT | Rocket Companies | Residential Loan Originators | 🔴 Cont. Bear | +28.1% | −6.8% |
12-month price & trend
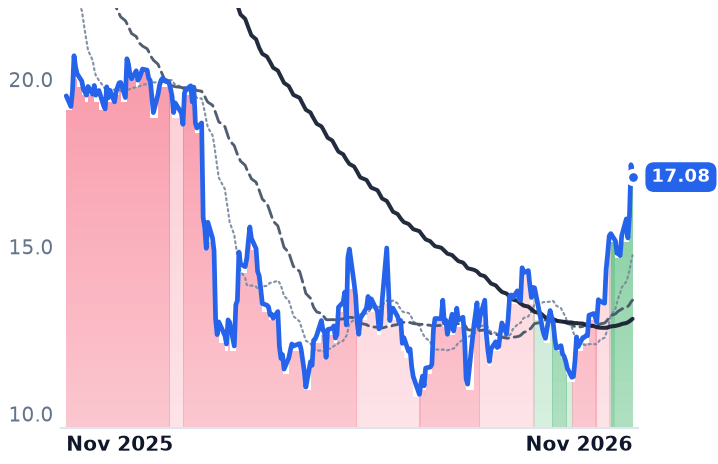
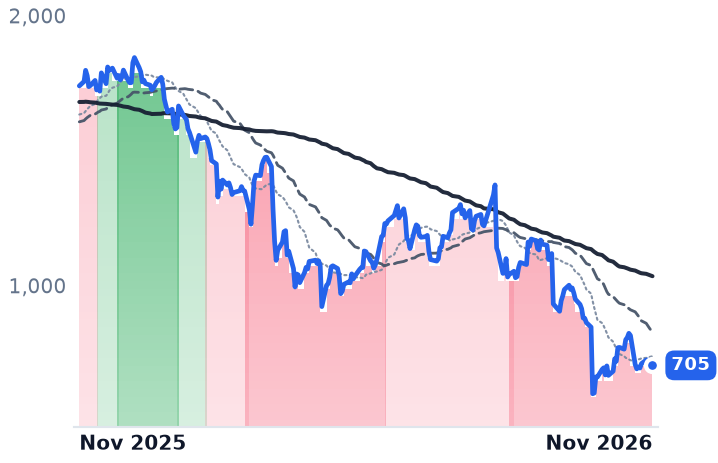
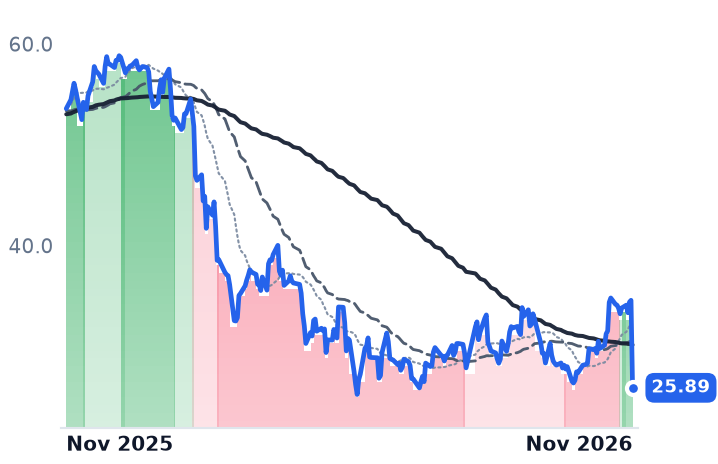
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VERX | $2.8B | n/m | 20.4x | 3.4x | 3.3x | 5.5x | 5.3x | 53.5x | 1.0% |
FICO | $15.2B | 19.3x | 15.6x | 6.0x | 5.8x | 7.0x | 6.7x | 16.1x | 7.0% |
BL | $1.5B | 38.0x | 10.4x | 2.0x | 2.0x | 2.7x | 2.6x | 18.5x | 11.4% |
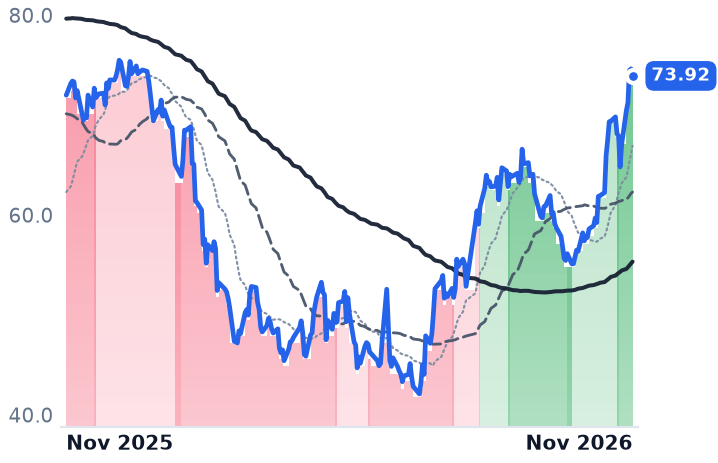
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QTWO | $4.6B | 41.8x | 26.4x | 5.2x | 5.1x | 9.0x | 8.8x | 27.0x | 5.0% |
TYL | $16.7B | 52.4x | 32.1x | 6.7x | 6.6x | 14.3x | 13.9x | 29.9x | 4.4% |
NCNO | $2.4B | 73.1x | 17.2x | 3.9x | 3.7x | 6.3x | 6.0x | 28.7x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALKT | $1.4B | n/m | 16.2x | 2.8x | 2.7x | 4.9x | 4.7x | 273.4x | 3.8% |
GWRE | $13.3B | 97.8x | 38.8x | 9.0x | 7.8x | 14.1x | 12.1x | 63.9x | 2.2% |
SSNC | $18.2B | 21.8x | 10.9x | 2.7x | 2.7x | 5.7x | 5.6x | 11.3x | 9.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TRU | $12.8B | 17.5x | 13.8x | 2.6x | 2.5x | 4.7x | 4.5x | 9.6x | 6.1% |
EFX | $17.7B | 26.2x | 17.6x | 2.7x | 2.6x | 4.9x | 4.7x | 12.1x | 6.3% |
RKT | $29.7B | 67.3x | 17.7x | 3.1x | 2.7x | 3.4x | 3.0x | 24.1x | -2.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VERX | Revenue | +10.7% | +10.4% | +11.3% |
| EPS | +30.8% | +22.3% | +23.5% | |
FICO | Revenue | +27.2% | +3.7% | +4.6% |
| EPS | +44.6% | +6.1% | +8.6% | |
BL | Revenue | +9.5% | +10.4% | +10.3% |
| EPS | +19.7% | +10.9% | +18.0% | |
QTWO | Revenue | +12.5% | +10.2% | +10.0% |
| EPS | +17.9% | +23.8% | +17.2% | |
TYL | Revenue | +8.7% | +9.9% | +9.8% |
| EPS | +14.8% | +18.9% | +14.1% | |
NCNO | Revenue | +9.8% | +8.9% | +8.6% |
| EPS | +25.2% | +45.3% | +19.9% | |
ALKT | Revenue | +19.9% | +14.4% | +14.4% |
| EPS | +59.0% | +30.1% | +26.1% | |
GWRE | Revenue | +23.8% | +17.2% | +15.6% |
| EPS | +41.5% | +20.0% | +27.5% | |
SSNC | Revenue | +8.4% | +5.1% | +4.9% |
| EPS | +17.7% | +8.6% | +8.4% | |
TRU | Revenue | +13.8% | +8.2% | +8.1% |
| EPS | +13.5% | +15.0% | +15.8% | |
EFX | Revenue | +11.2% | +8.3% | +9.7% |
| EPS | +11.8% | +17.4% | +21.0% | |
RKT | Revenue | +72.1% | +5.7% | +7.9% |
| EPS | +146.1% | +34.6% | +21.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vertex, which sells indirect-tax determination and compliance software to corporations in retail, communications, leasing and manufacturing, added barely any customers last quarter and still raised its full-year guidance. Annual recurring revenue grew 11.7% to $724.3m while average revenue per customer rose 9.2% to $145,793 — arithmetic that leaves implied customer growth near 2.3%. Almost all of the growth came from accounts already signed, putting more invoices through the meter.
Three vendors on the same financial-services software shelf reported inside four days: Vertex and Fair Isaac on 4 November, BlackLine on 5 November. They did so after twelve months in which the nine-name group lost 23% equal-weighted, a de-rating widely read as artificial intelligence hollowing out software priced by the seat. The prints point somewhere else. What decided these three quarters was who sets the billable unit — Vertex's is set by European legislatures, Fair Isaac's was set by Fair Isaac until a federal housing regulator intervened, and BlackLine's seat meter was dismantled by BlackLine.
A legislature sets the invoice count
Vertex's revenue reached $213.3m in the quarter, up 11.0%, with cloud revenue growth re-accelerating above 20% against a full-year cloud guide that had been cut to 18% in August. Net revenue retention improved a point sequentially to 106%, gross retention held at 95%, and full-year guidance went up to revenue of $828.9–830.9m with the adjusted EBITDA midpoint lifted $10.9m.
The driver is statutory. "E-invoicing ARR up over 100% year-on-year," chief executive Christopher Young told investors on 4 November. "Growth in e-invoicing contributed meaningfully to the re-acceleration in cloud revenue… This reflects strong execution, the successful launch of the French mandate and the contribution from Brinta." Germany, Norway and Slovakia begin mandates in January 2027, with Spain and phased UK obligations running into 2029. One offset was disclosed: the loss of a payroll original-equipment customer worth about $1m a quarter, enough on its own to take retention down a point in the fourth quarter.
GAAP profit is still nominal — operating income of $0.3m and a net loss of $46.6m — so the stock is judged on gross profit, at 5.46x trailing against roughly 5.09x on 30 October and 3.85x at the end of September. The re-rating is largely done.
The price Fair Isaac can no longer raise
Fair Isaac's fiscal year, ended 30 September, was the better of the two reported records: revenue of $2.535bn, up 27.3%, and Scores revenue of $1.652bn, up 41%, with business-to-business Scores up 39% in the fourth quarter. That came almost entirely from lifting the mortgage score price from $4.95 to $10 while score-pull volumes fell high single digits.
That lever is now pinned. Fair Isaac has held the wholesale tri-merge bundle at $10 for 2027 for resellers whose lenders commit to pulling a FICO score on every mortgage application. The substitute costs about a tenth as much: VantageScore 4.0 sells near $0.99, with TransUnion's pricing extended through 2028, and Rocket Mortgage has made VantageScore its preferred provider on eligible loans. Management says it has seen no meaningful volume loss to competition. It also withheld fiscal 2027 guidance entirely, with mortgage programs unsettled and the pricing year resetting on 1 January while the fiscal year began 1 October.
"Transparency and detail on our programs and pricing have not been particularly helpful for FICO," chief executive William Lansing said on 4 November. "We're not going to share every pricing program. We're not going to share what the prices are."
The shares fell 29% on 29 September, the day after the Federal Housing Finance Agency's director, Bill Pulte, said Fannie Mae and Freddie Mac would adopt a pricing grid incorporating VantageScore, and more than 13% on 26 October when Pulte pledged further action and the flat $10 price was read as defensive. Twelve-month decline: 59.5%. The stock sits at 19.3x trailing and 15.6x forward earnings, and that forward figure rests on a $45.25 consensus the company declined to endorse. The part growing independently is software: platform annual recurring revenue of $453m, up 72%, now 53% of total.
BlackLine swapped meters and the new one is late
BlackLine, whose software automates the corporate accounting close, cut full-year revenue guidance to $759.5–761.5m from $765–769m, guided the fourth quarter about 5.7% below consensus, and lost 25.1% on 6 November. Growth has stepped down three quarters running, 9.7% to 9.2% to 8.5%. Retention rose to 103.5% on platform conversions carrying 10–40% pricing uplift, which the company said was offset by lower user expansion. Paid agentic artificial intelligence moved from the first half of 2027 to mid-to-end 2027, waiting on customers' auditors and governance committees.
The cash went the other way: non-GAAP operating margin expanded 450 basis points to 25.9% on under 1% headcount growth, the trailing free-cash-flow yield is 11.4%, all of it going to buybacks, and at 2.66x trailing gross profit it is the cheapest of these names. "If customers were replacing us, it would show up first in our largest accounts as churn, smaller contracts and/or shorter commitments," chief executive Owen Ryan said on 5 November. "We are seeing the opposite, larger deals, longer commitments and strong enterprise renewals."
Four names made a nine-name turn
The shelf's 11.6% equal-weighted gain over the month to 6 November came from Vertex at 38.4%, Q2 Holdings at 27.8%, Tyler Technologies at 26.7% — a vendor of court and municipal software to state and local governments, not a financial-services meter at all — and nCino at 18.6%. The median member moved 0.25%; BlackLine fell 8.2%. The window opens almost exactly at the 5 October peak in the 10-year Treasury yield, which eased back below 5% by 30 October.
Only one of those gains traces to a change in the company's own unit economics. Q2 Holdings, which sells digital-banking platforms to regional banks and credit unions, rose on cost: its first 30% adjusted EBITDA margin, up 580 basis points, on revenue growth of 11.9% — and at 8.99x trailing gross profit it is the dearest name measured here. Fair Isaac's reported economics accelerated while its equity halved, because the market is pricing the lever that is frozen rather than the year that was banked. BlackLine's growth and its cash generation now disagree, and the thing meant to reconcile them has slipped a year.
Fair Isaac's lender clients have until 31 January to choose which 2027 pricing path they take. The company has already said it will not tell them, or anyone else, what the prices are.