

Only Wolfspeed Among Five Power-Chip Makers Has Numbers That Explain Its Markdown
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The shelf of chipmakers sold as the supply chain for Nvidia's 800-volt rack reported inside six days and then fell together — and the revenue the three biggest just billed has almost nothing to do with 800 volts. Monolithic Power's first $1bn quarter came from power-management parts already in production; its 800-volt gallium-nitride devices are only sampling, with revenue its own management dates to late 2027.
Four of the five beat. Monolithic Power grew 63.1% with Enterprise Data revenue up 164.6% to $506.7m, onsemi expanded gross margin for a fifth straight quarter to 41.2% with fab utilization at 83%, Navitas grew for the first time since 2024, Vishay printed a record book. Only Wolfspeed's shipped numbers deteriorated, on a negative gross margin.
So the markdown tracked how far each name had run rather than its 800-volt content: Vishay, which has no power stage at all, fell harder than onsemi or Monolithic Power.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
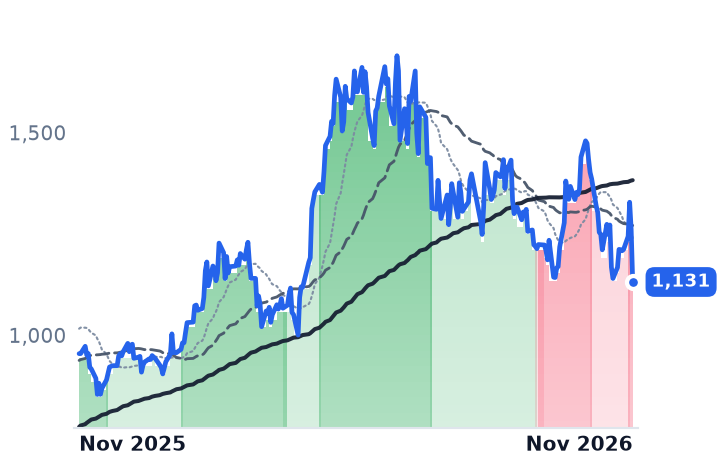
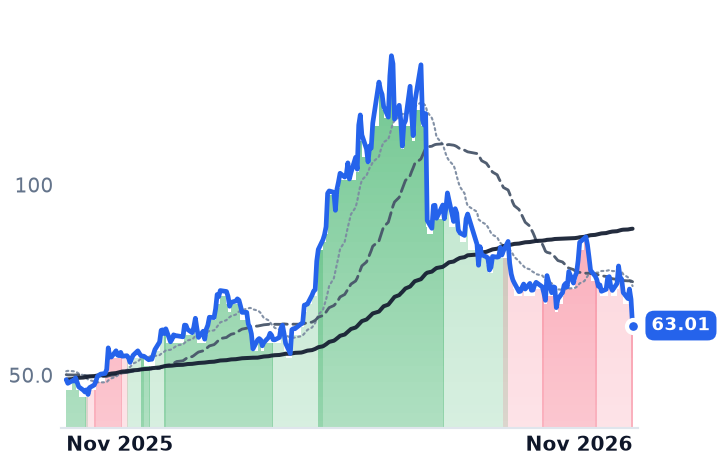
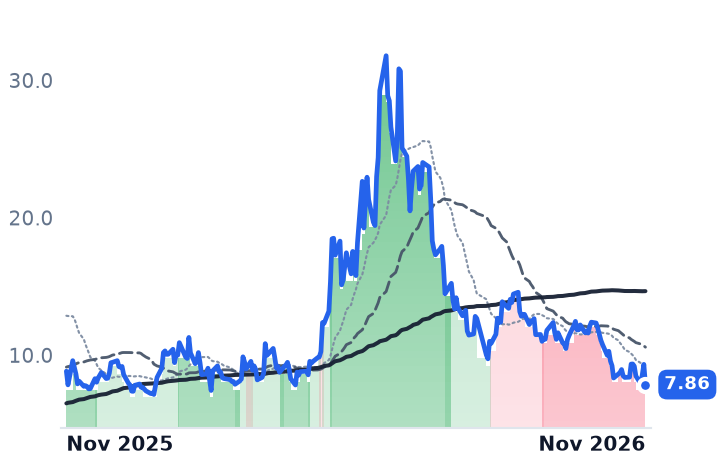
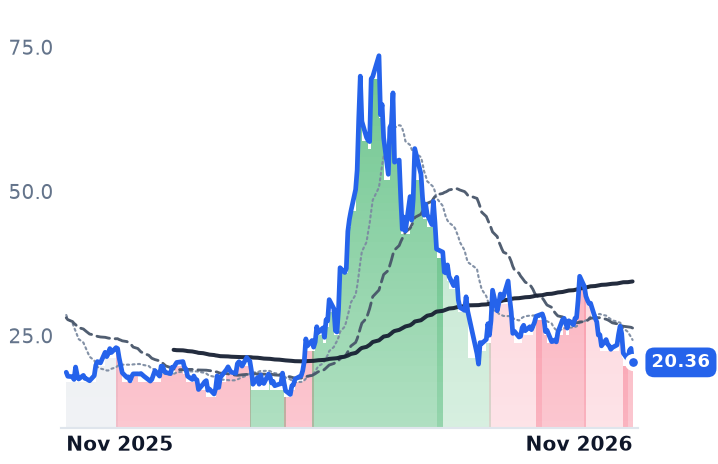
MPWR | Monolithic Power Systems | Analog & Power Management | ⚠️ Emerging Bear | −21.1% | +18.5% |
ON | ON Semiconductor | Analog & Power Management | ⚠️ Emerging Bear | −25.2% | +29.1% |
NVTS | Navitas Semiconductor | Analog & Power Management | 🔴 Cont. Bear | −31.7% | −11.0% |
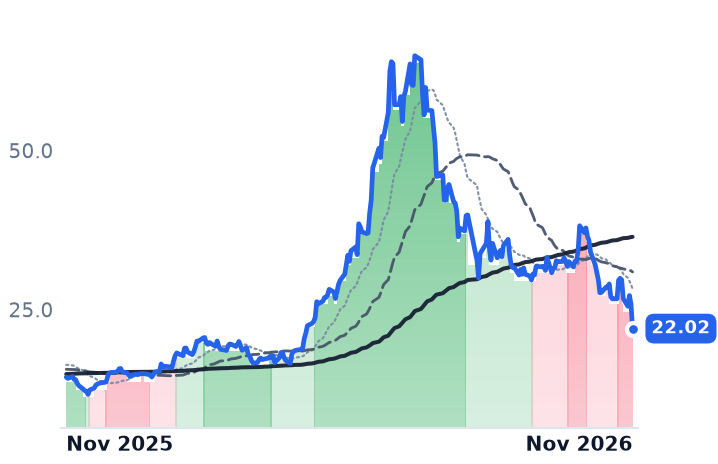
VSH | Vishay Intertechnology | Analog & Power Management | ⚠️ Emerging Bear | −39.7% | +53.0% |
WOLF | Wolfspeed | Analog & Power Management | 🔴 Cont. Bear | −34.6% | +9.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $55.2B | 62.1x | 38.8x | 14.8x | 12.7x | 26.7x | 23.1x | 45.9x | 1.1% |
ON | $24.5B | 35.8x | 19.2x | 3.9x | 3.7x | 10.0x | 9.7x | 15.2x | 6.6% |
NVTS | $2.1B | n/m | — | 50.8x | 41.9x | 354.5x | 292.7x | n/m | -3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VSH | $3.1B | 31.6x | 23.6x | 0.7x | 0.8x | 3.2x | 3.8x | 6.4x | 3.7% |
WOLF | $1.1B | n/m | — | 1.7x | 1.7x | — | — | n/m | -32.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MPWR | Revenue | +55.8% | +51.2% | +24.7% |
| EPS | +64.5% | +58.9% | +25.5% | |
ON | Revenue | +10.1% | +14.9% | +12.4% |
| EPS | +40.9% | +44.3% | +27.1% | |
NVTS | Revenue | +7.5% | +65.0% | +66.1% |
| EPS | −16.4% | +25.7% | −32.2% | |
VSH | Revenue | +21.5% | +15.4% | +11.1% |
| EPS | −3039.4% | +101.6% | +52.6% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Five makers of power semiconductors reported quarters between 29 October and 4 November, and four of them billed more than they had guided to, on margins that widened. Monolithic Power Systems, which designs the DC-to-DC conversion chips that step voltage down for processors, passed $1bn of quarterly revenue for the first time. By the close on 5 November every one of the five had been marked down by a tenth or more in a single session.
The shelf had been bought as the parts list for Nvidia's 800-volt direct-current rack, which converts utility alternating current straight to 800 volts and removes the 54-volt distribution inside the rack. The quarters just filed say something narrower. The AI money these companies collected came from parts already in production; the 800-volt stages are dated by the people selling them to late 2027 and 2028.
The 800-volt money is dated by its own makers
Monolithic Power's September quarter was $1.202bn, up 63.1% year on year, the fourth straight quarter of accelerating growth. Enterprise Data revenue was $506.7m, 42.1% of the total and up 164.6%. Gross margin was 55.35%, inside half a point of where it sat eight quarters ago, and December quarter guidance of about $1.35bn landed roughly 10% above the consensus analysts carried. "I see this explosive growth period in the next few years," chief executive Michael Hsing said on 29 October. "And we don't see anything -- any signs of the slowdown."
None of that is 800-volt revenue. The company's 800-volt gallium-nitride parts are only now sampling, with revenue expected late 2027 and material ramp in 2028; it intends to ship some 50m units before confirming a sub-one-part-per-million failure rate. Its first 48-volt automotive orders are a 2027 growth driver by management's own description. Against that, the shares trade at 26.7 times trailing gross profit, a multiple that was 49.8x in May.
Navitas Semiconductor sits at the other end of scale: $14.0m of revenue, up 38.4% and its first year-on-year growth since 2024, with gross margin back to 39.3% from minus 8.9%. The operating loss was $34.4m on that revenue and diluted shares rose 22.9% over the year. "Power is now the #1 constraint on AI compute," chief executive Chris Allexandre said on 3 November. The constraint is real; the billing is not yet. December quarter guidance is $16.0m against a breakeven level management frames in the low $60m a quarter, the anchor customer of its $126m Claros acquisition does not ramp until late 2028 to 2029, and the company's own date for in-rack native 800-volt systems has already slipped to early 2028. At 41.9 times forward sales, against onsemi's 3.7x, the de-rating here is a valuation fact.
What the fabs actually did
onsemi, which makes power switching and sensing devices for cars, industrial power and chargers, grew 11.1% to $1.7223bn and expanded non-GAAP gross margin 190 basis points to 41.2%, a fifth consecutive quarter of expansion. AI data-center revenue reached $180m, up 175%. Fab utilization held at 83%, up from 77% in the March quarter, and distributor inventory fell to 9.9 weeks. Automotive at $777m was flat and guided lower. "What you're seeing today is short term in nature and it's supply-driven, not strategically driven," chief executive Hassane El-Khoury said on 2 November. "What we are holding back is their replenishment." The stock is 19.2 times forward earnings against 35.8x trailing, and 10.0 times trailing gross profit against 12.2x in August.
Wolfspeed is the exception the numbers do explain. Revenue of $155.0m fell 21.2%, the fourth straight year-on-year decline, on a minus 21.9% gross margin and a $143.8m net loss. Breakeven needs roughly $200m a quarter. It has a conditional $1.5bn thirty-year Department of War loan commitment, but chief financial officer Gregor van Issum noted on 4 November that drawing the tranches carries "several financial commitments, limited equity raise, and some other de-risking measures." At 1.68 times forward sales there is no earnings or gross-profit multiple to quote.
A passive maker with no power stage fell hardest
On 5 November the Philadelphia Semiconductor Index fell 12.3%, its worst day since 16 March 2020, after a Democratic midterm sweep brought calls from party leaders for data-center restrictions. Monolithic Power fell 10.3%, onsemi 9.9%, Navitas 15.8%, Wolfspeed 10.7% — between a third and a half of each name's entire 30-day decline, inside one session.
Vishay Intertechnology fell 14.8%, harder than onsemi, Monolithic Power or Wolfspeed. It makes discrete semiconductors and passive components — resistors, capacitors, diodes — and owns no 800-volt power stage. It printed record revenue of $978.9m, up 23.8%, on a 1.29 book-to-bill and a $2.2bn backlog equal to 6.6 months, with selling prices up 4% year on year. "AI revenue, last year we were around $100 million," chief executive Joel Smejkal said on 4 November. "This year we keep pushing to be near $200 million is what our push is" — about 5% of the base, at 6.4 times trailing EV/EBITDA.
What the results account for
For four of the five the shipped numbers moved the wrong way for the price: revenue accelerated, margins widened, inventory in the channel thinned, and order books lengthened straight into the decline. The markdown sorted the group by how far each had run rather than by its exposure to the 800-volt socket, which is why the cheapest name on cash earnings fell about as hard as the most expensive one on sales. Only two of the five carry a de-rating their own disclosures support, and for different reasons: Wolfspeed because the revenue is shrinking against a fixed cost base, Navitas because 41.9 times forward sales prices a design-in that its own calendar puts years out.
The prize is not small — power equipment per rack rises from roughly $36,000 to more than $398,000 as racks scale toward 600 kilowatts. What the quarters establish is who is being paid for it now, and the answer is a short list that does not yet include the 800-volt parts themselves.
The next readings land before the voltage does. Monolithic Power's December quarter tests a $1.35bn guide; onsemi's tests a gross margin guided to 41.5-43.5% on $40-50m of capital spending. Both will print long before a single 800-volt gallium-nitride device bills a dollar.