

Reddit's Traffic Is Falling to Google's AI Answers, So It Is Selling Ads in Its Own Search
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Reddit's accounts and its audience moved in opposite directions last quarter, and management told investors the audience problem is getting worse. Advertising revenue grew 54% to $847m and the adjusted EBITDA margin reached 45%, while daily active uniques in the United States fell 2% to 50.7m, with logged-out users down 4% because Google's AI Overviews now answer the question instead of passing the click.
Management guided fourth-quarter revenue to $1.00bn-$1.03bn and simultaneously warned that total daily uniques could fall by a low double-digit percentage from 130.3m. Four days after the print it began testing ads inside Reddit's own search results.
The business explains the markdown better than the multiple does: at 17.5x forward earnings, consensus still carries 2027 revenue growth of 28.5% set before the traffic warning. AppLovin, which owns both the auction and the inventory, has no such distribution landlord.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
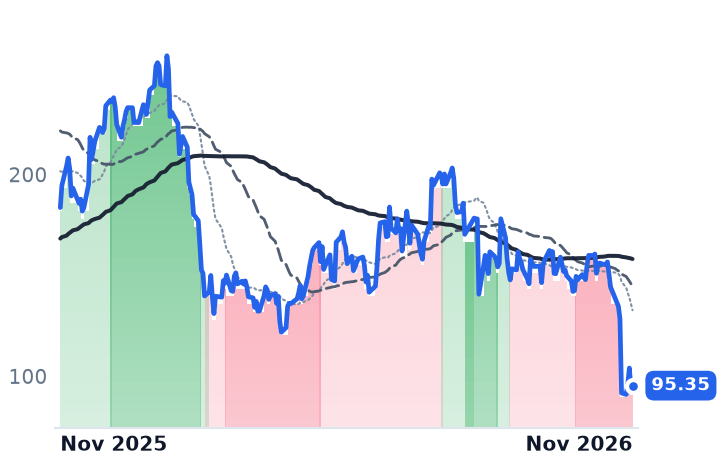
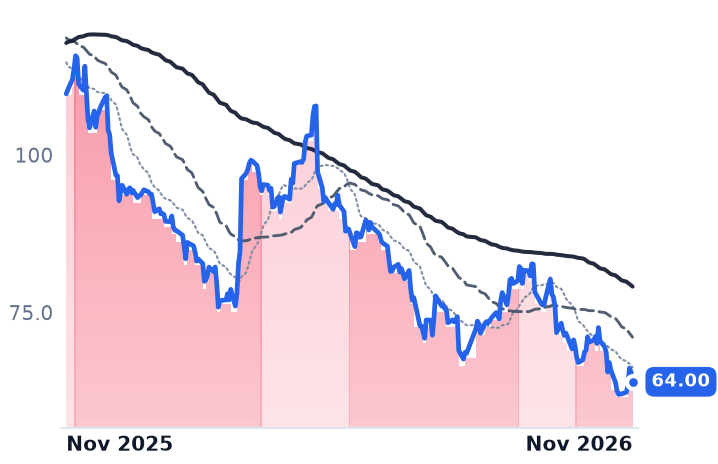
RDDT | Social & Community Platforms | 🔴 Cont. Bear | −35.5% | −48.1% | |
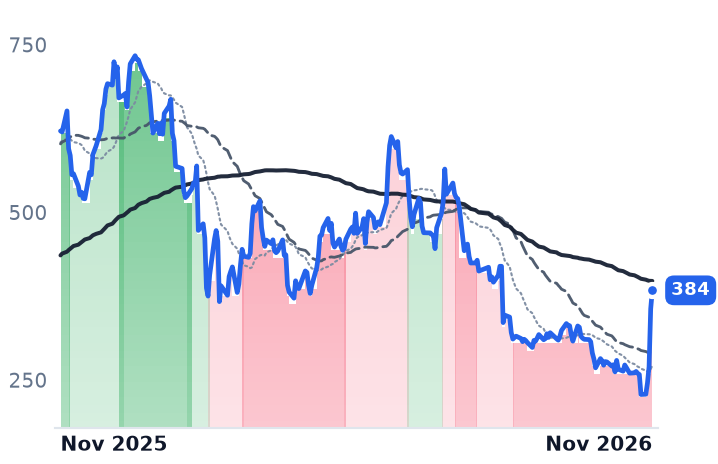
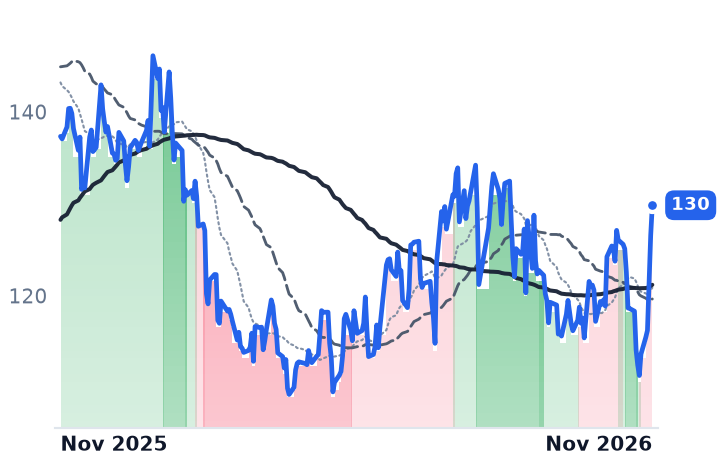
APP | AppLovin | Marketing, Advertising & Growth | 🔴 Cont. Bear | +41.0% | −38.2% |
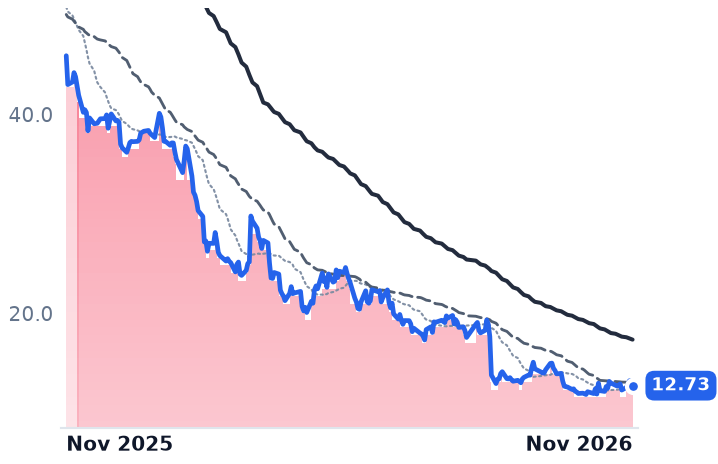
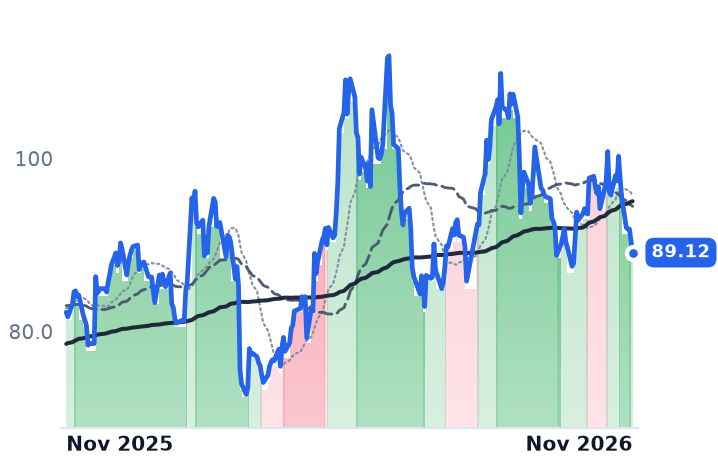
TTD | The Trade Desk | Programmatic Platforms | 🔴 Cont. Bear | +7.5% | −72.3% |
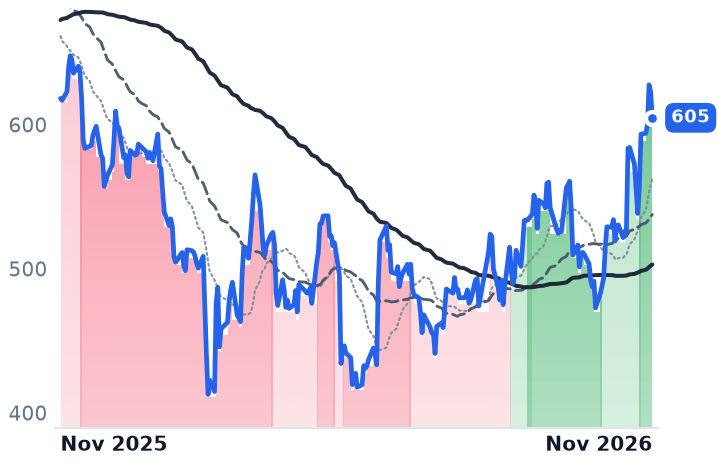
SPOT | Spotify Technology | Entertainment & Content Streaming | 🌱 Emerging Bull | +22.5% | −2.2% |
NFLX | Netflix | Streaming Services | 🔴 Cont. Bear | −7.3% | −41.7% |
NTES | NetEase | Premium Game Publishers | 🔴 Cont. Bear | +8.6% | −5.5% |
ZM | Zoom Communications | Software Development & Design | 🟢 Cont. Bull | −5.1% | +8.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RDDT | $18.4B | 18.4x | 17.5x | 6.0x | 5.4x | 6.5x | 5.9x | 16.7x | 6.5% |
APP | $117.3B | 25.7x | 24.5x | 15.4x | 14.5x | 17.4x | 16.3x | 18.8x | 4.2% |
TTD | $6.0B | 15.2x | 35.1x | 2.0x | 2.2x | 2.6x | 2.9x | 6.9x | 14.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPOT | $124.5B | 37.8x | 51.2x | 5.9x | 6.4x | 17.9x | 19.2x | 29.9x | 2.9% |
NFLX | $266.5B | 18.2x | 17.9x | 5.4x | 5.2x | 10.6x | 10.3x | 7.5x | 4.3% |
NTES | $82.7B | 16.8x | — | 4.7x | — | 7.0x | — | 11.7x | 9.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ZM | $26.3B | 8.2x | 14.7x | 5.3x | 5.2x | 6.8x | 6.7x | 5.9x | 7.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RDDT | Revenue | +58.1% | +28.5% | +24.1% |
| EPS | +135.0% | +25.5% | +24.9% | |
APP | Revenue | +43.0% | +24.8% | +20.7% |
| EPS | +66.9% | +25.4% | +24.1% | |
TTD | Revenue | −4.9% | −5.2% | +5.8% |
| EPS | −57.5% | −40.6% | +51.1% | |
SPOT | Revenue | +13.7% | +14.8% | +13.6% |
| EPS | +65.1% | +28.0% | +26.4% | |
NFLX | Revenue | +13.4% | +10.6% | +9.7% |
| EPS | +39.8% | +4.9% | +18.9% | |
NTES | Revenue | +6.8% | +7.6% | +6.8% |
| EPS | +0.9% | +16.1% | +8.5% | |
ZM | Revenue | +4.2% | +4.9% | +4.4% |
| EPS | +9.7% | +3.1% | +3.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Reddit earned more from a smaller American audience last quarter, and the company has stopped waiting to find out whether that trade can run. On 3 November it began testing advertisements inside its own search results, four days after telling investors that Google's AI answers were absorbing the visitors who used to click through.
The 29 October print was read as the quarter in which Reddit's pricing engine took over from its audience growth. Half of that reading survives contact with the numbers. Advertising revenue of $847m grew 54% year on year, gross margin held at 91.5% for a ninth consecutive quarter, and the adjusted EBITDA margin reached 45%. What does not survive is the assumption underneath it: that the audience being monetized stays put.
The audience fell where the dollars are
Global daily active uniques grew 12% to 130.3m, carried entirely by international users, up 24% to 79.6m. The United States, where the money is, went the other way: down 2% to 50.7m, with logged-out users off 4% and logged-in users up just 1%. Management said logged-out web traffic fell meaningfully through the quarter, that the decline accelerated late in it, and that October alone ran more than a million fewer weekly average referrals as Google's AI Overviews and AI Mode answered queries directly.
Then the guidance arrived in two halves that point different ways. Fourth-quarter revenue is guided to $1.00bn-$1.03bn, up 38% to 42%, with adjusted EBITDA of $480m-$510m. Total daily uniques, management warned, could fall by a low double-digit percentage from the 130m base if the search trend holds.
Price is doing the work, and licensing is not
Average revenue per user rose 36% to $6.87 globally, and in the United States 53% to $13.82. Performance advertising is now more than 60% of the business, with click volume up 50% and conversion volume more than tripled. The company earning materially more from each American reader is the same company with fewer of them.
One popular offset is not there. Other revenue, the line containing data licensing, was $48m, 5.4% of the total, growing 35% against advertising's 54%. Licensing talks with OpenAI and Google were described as ongoing with no new terms, so the AI products absorbing the referrals are not yet paying for them.
"Moving to primarily logged-in will ensure our users have the best Reddit experience possible," co-founder and chief executive Steve Huffman told investors on 29 October, announcing fourth-quarter tests of a logged-in-only experience in select non-US markets. "It's better for our business because we have more signals for ads targeting." Chief operating officer Jennifer Wong put the demand case this way the same day: "Half of U.S. shoppers say they come to Reddit to verify AI recommendations."
The comparison that explains the mechanism
AppLovin, which runs a mobile ad auction and the measurement layer around it across more than 140,000 apps, has no distribution landlord, and its quarter showed it. Revenue accelerated to a record $2.185bn, up 55.5%, at an 84% adjusted EBITDA margin, with the fourth quarter guided up 43% to 44%. The shares rose 31.98% on 5 November, to 24.5x consensus 2026 earnings of $15.69 against roughly 66x a year ago, helped by a buyback authorisation lifted by $3.2bn to $3.6bn. "We grew 55%, several times faster than the market," chief financial officer Matt Stumpf said on the 4 November call. The caveats are real: a securities-fraud class action over its AI claims is unresolved, and its reported return on ad spend is platform self-attribution.
The Trade Desk, which sells agencies the seat rather than the inventory, sits at the other end of the same mechanism, with June-quarter revenue up 3.0% and 6.93x trailing EV/EBITDA against a 14.3% free-cash-flow yield. Meta, Google and Amazon are forecast to take 62.3% of worldwide digital ad spend in 2026.
The 2027 estimates predate the traffic warning
Reddit's shares fell 28.6% in the session after the print, to $91.73 on 30 October, and are down 48.1% over twelve months. The accounts justify none of that; the meter behind them justifies most of it. At 17.5x forward earnings against 18.4x trailing, consensus still carries 2027 revenue of $4.359bn, up 28.5%, and earnings of $6.82 a share, figures set before the daily-user warning and not yet reconciled with it.
So the question Reddit has set itself is whether a community site can sell its own search box faster than someone else's stops sending people to it.