

Applied Optoelectronics Missed Its Margin Guide Because the New Volume Was 400-Gigabit
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
What a shipped optical module earns the company that builds it turns almost entirely on which speed grade sits inside it, and last quarter Applied Optoelectronics got the cheap one. Its data-center sales grew hard, but $93.4m of them — 60.2% of the segment — was 400-gigabit product against $47.5m of 800G, and non-GAAP gross margin landed at 28.7%, below both its own 29.0–30.5% guide and the 31.0% it earned a year earlier.
Nobody else along the chain had that problem. MaxLinear's price for the signal-processing chip inside the module roughly doubles across the same transition and it keeps 58.7% gross margin; Fabrinet keeps about twelve cents of every revenue dollar whatever the grade, and grew revenue 50.7%; Viavi grew 56.9% selling the test gear. Every one of these shares roughly halved in a month. Only Applied Optoelectronics' margin line is explained by what it actually shipped.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
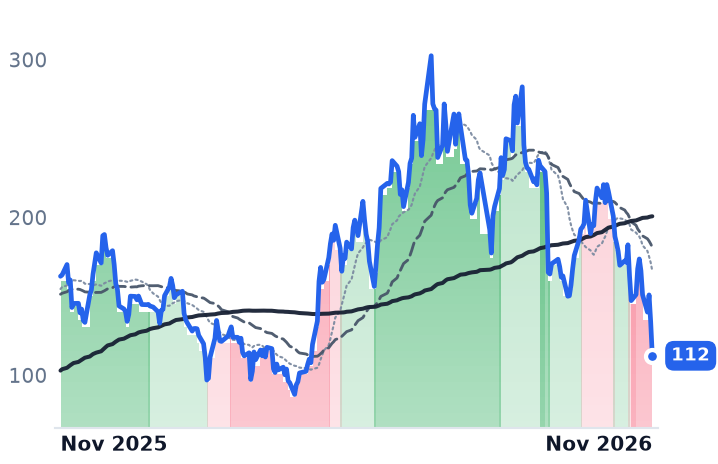
VIAV | Viavi Solutions | Other | ⚠️ Emerging Bear | −39.3% | +59.9% |
| Compared against · context, not the story | |||||
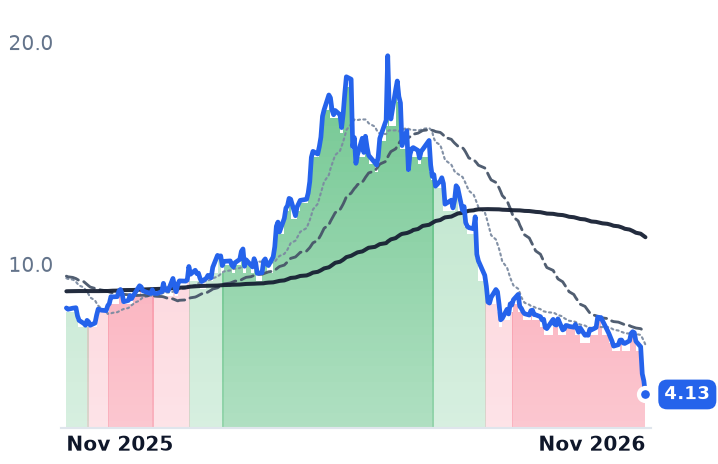
AAOI | Applied Optoelectronics | Optical Networking | 🔴 Cont. Bear | −61.7% | +61.1% |
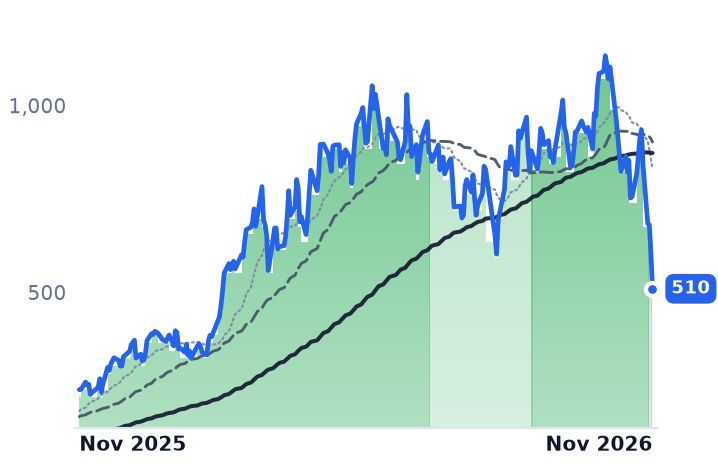
MXL | MaxLinear | Analog & Power Management | 🟢 Cont. Bull | −58.9% | +199.0% |
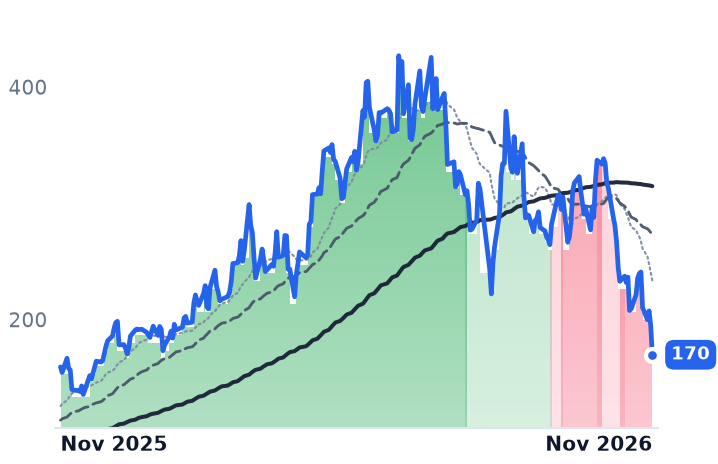
FN | Fabrinet | Contract Manufacturing | 🔴 Cont. Bear | −37.8% | −36.5% |
ADTN | ADTRAN | Optical Networking | 🔴 Cont. Bear | −45.6% | −48.6% |
LITE | Lumentum | Optical Networking | 🟢 Cont. Bull | −54.1% | +112.7% |
COHR | Coherent | Photonics & Optics | ⚠️ Emerging Bear | −49.3% | +6.6% |
CRDO | Credo Technology | Data Center & Networking | ⚠️ Emerging Bear | −46.3% | −31.0% |
MRVL | Marvell Technology | Data Center & Networking | 🟢 Cont. Bull | −52.4% | +43.3% |
ANET | Arista Networks | Cloud Networking | 🟢 Cont. Bull | −24.3% | +18.8% |
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | −23.5% | −3.4% |
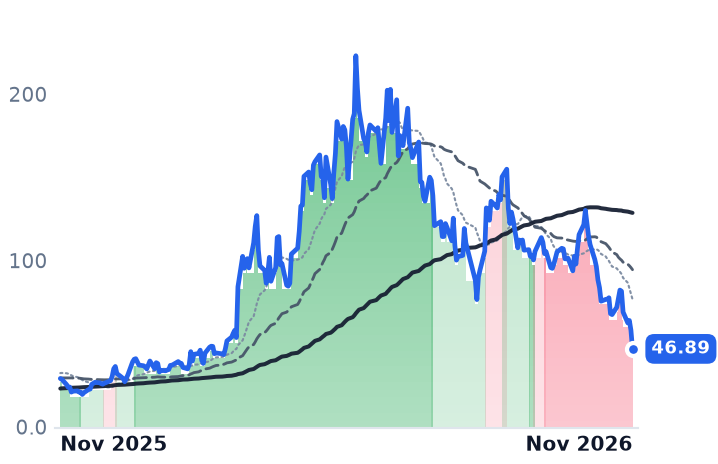
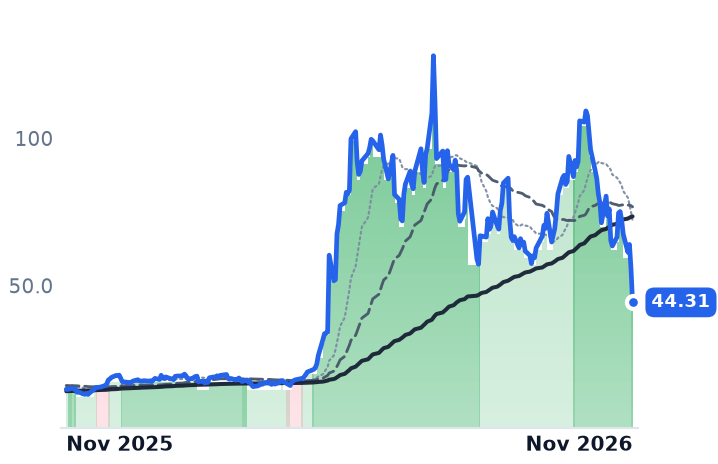
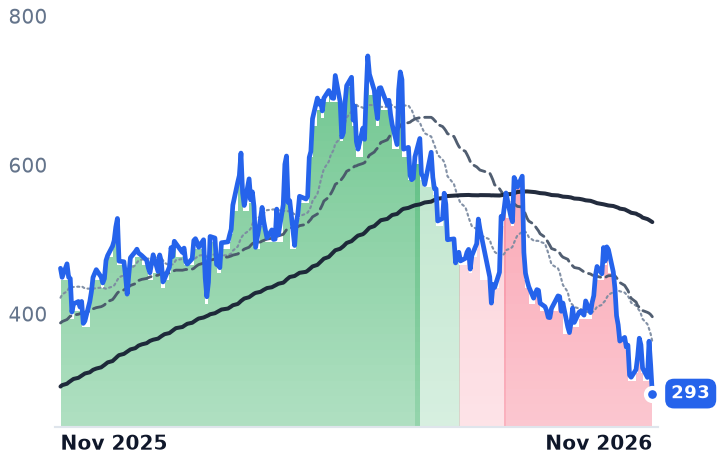
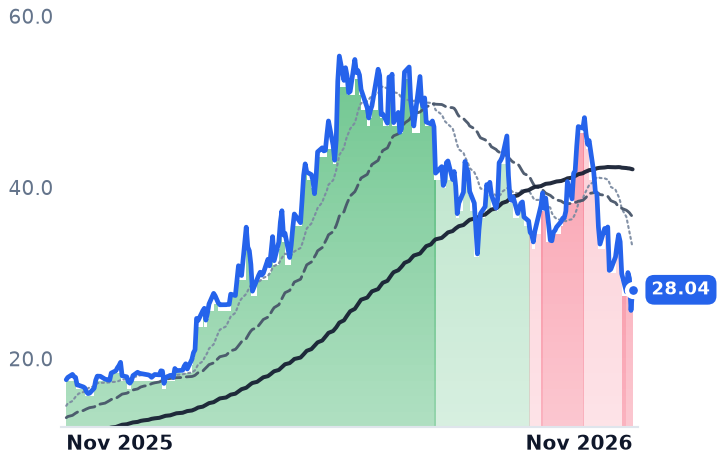
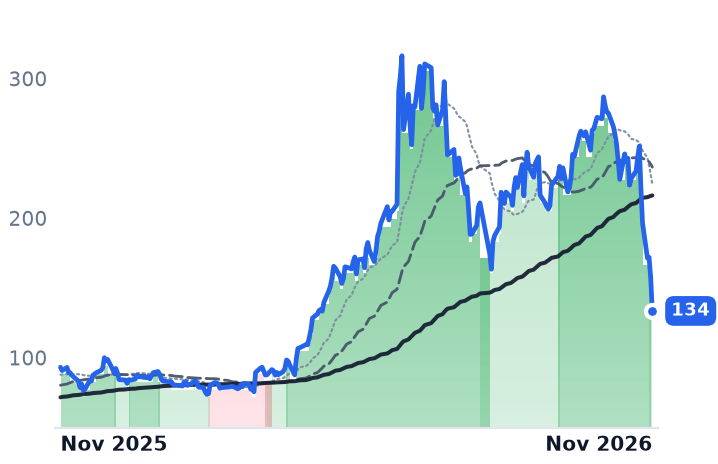
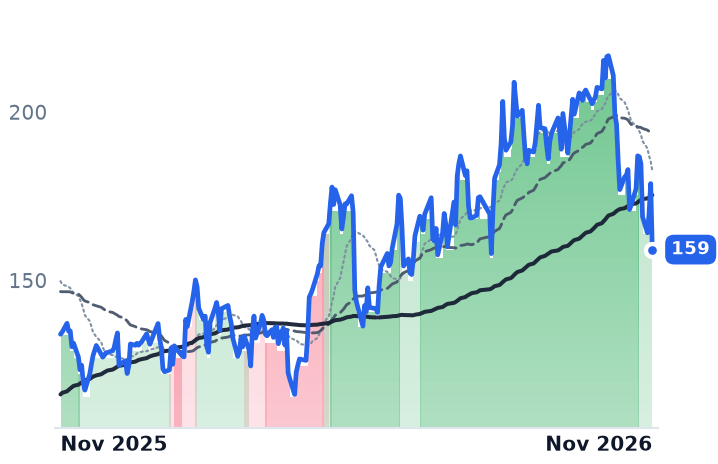
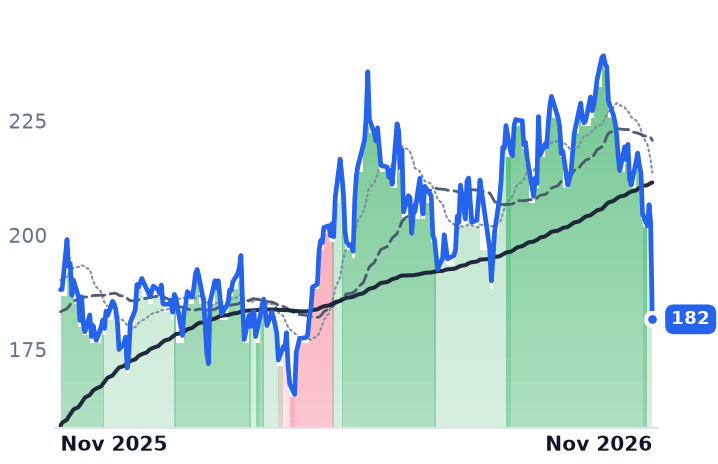
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAOI | $5.9B | n/m | 93.3x | 9.8x | 5.6x | 34.0x | 19.3x | n/m | -7.0% |
MXL | $6.1B | n/m | 34.1x | 9.3x | 7.9x | 16.0x | 13.6x | 187.7x | -0.3% |
FN | $11.4B | 23.7x | 16.1x | 2.2x | 1.7x | 18.5x | 14.4x | 16.8x | -1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VIAV | $6.9B | 101.4x | 17.1x | 4.1x | 3.7x | 7.0x | 6.2x | 26.0x | 2.2% |
ADTN | $326.3M | n/m | 13.7x | 0.3x | 0.3x | 0.7x | 0.7x | 5.1x | 6.9% |
LITE | $74.1B | n/m | 37.6x | 24.6x | 11.7x | 59.0x | 28.1x | n/m | 0.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
COHR | $43.6B | 50.9x | 23.5x | 6.1x | 4.1x | 16.3x | 11.0x | 29.5x | -2.4% |
CRDO | $43.0B | 88.0x | 37.3x | 32.2x | 17.5x | 47.3x | 25.7x | 82.0x | 0.9% |
MRVL | $204.7B | 76.7x | 55.5x | 21.7x | 17.0x | 42.1x | 33.0x | 43.3x | 0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ANET | $223.5B | 55.2x | 43.1x | 21.2x | 17.6x | 33.7x | 28.0x | 43.5x | 2.3% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AAOI | Revenue | +131.7% | +182.3% | +72.7% |
| EPS | −327.3% | +650.0% | +92.2% | |
MXL | Revenue | +66.7% | +78.3% | +32.3% |
| EPS | +583.6% | +135.9% | +22.8% | |
FN | Revenue | +35.6% | +43.2% | +19.5% |
| EPS | +36.2% | +42.4% | +21.7% | |
VIAV | Revenue | +39.8% | +25.1% | +13.4% |
| EPS | +107.0% | +75.4% | +18.6% | |
ADTN | Revenue | +5.5% | +6.4% | +7.7% |
| EPS | +82.1% | +60.1% | +68.4% | |
LITE | Revenue | +83.9% | +110.8% | +57.6% |
| EPS | +314.0% | +164.8% | +61.2% | |
COHR | Revenue | +22.1% | +50.0% | +37.9% |
| EPS | +56.5% | +72.3% | +49.3% | |
CRDO | Revenue | +211.9% | +85.0% | +49.7% |
| EPS | +423.2% | +86.8% | +48.2% | |
MRVL | Revenue | +42.4% | +47.4% | +61.9% |
| EPS | +82.6% | +48.1% | +72.8% | |
ANET | Revenue | +42.6% | +30.8% | +24.6% |
| EPS | +42.6% | +27.9% | +23.2% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Applied Optoelectronics reported its sixth consecutive record quarter on 5 November and still earned less on each dollar it shipped than a year earlier, and the reason is printed in the speed-grade split. Revenue of $269.9m was up 127.5% from a year ago, with $6.3m of net income, the first GAAP profit after operating losses in every year on record.
The 800-gigabit-to-1.6-terabit transition has been read all year as a rising tide for anyone holding a socket in an optical module. The quarter says the water level is uneven: the margin accrues to the grade you are actually on and to the silicon inside the package, while the assembler's toll is fixed at whatever it was.
The grade decides the margin
Applied Optoelectronics' incremental data-center volume arrived disproportionately in the older grade. Revenue from 400G nearly doubled sequentially to $93.4m, 60.2% of data-center revenue, while 800G nearly quadrupled to only $47.5m. Non-GAAP gross margin came in at 28.7%, under the 29.0–30.5% it had guided and under 31.0% a year earlier; management's stated objective is to work back toward roughly 40% as mix moves to 1.6T and in-house lasers. It is also not yet a pure AI-optics business: 41% of the quarter was cable-TV hardware, roughly $110m, against 58% from data-center products.
The 1.6T award it has advertised is real and partial. A three-year agreement signed after 30 September obliges a major hyperscale customer, with conditions, to buy 10% of certain 1.6Tb transceiver products from June 2026 to May 2029, worth a potential $1.0–1.5bn. That is a second-source allocation of a defined share. Diluted shares have meanwhile gone from 42.3m in the third quarter of 2024 to 81.6m by mid-2026, so per-share progress has had to outrun issuance.
MaxLinear is paid twice for the same socket
The same transition reprices the chip. MaxLinear's Infrastructure segment reached about $125m last quarter, up 210% and more than half of total revenue, on Keystone, a 5-nanometer 100-gigabit-per-lane signal processor in volume production for 800G builds; its 200-gigabit-per-lane successor is in qualification for 1.6T with first revenue early in 2027. "The ASP on the DSP is more or less doubling, and then we have TIA that we did not add before," chief executive Kishore Seendripu told investors on 22 October, referring to the transimpedance amplifier MaxLinear now attaches at an initial 80% rate. Company revenue of $218.1m grew 72.4% at 58.7% gross margin, with $30.2m of operating income after annual operating losses in 2023, 2024 and 2025. Management puts its optical share at 5–7% today.
Fabrinet's twelve cents are indifferent to speed
Fabrinet, which assembles transceivers, tunable lasers and amplifiers to its customers' designs, is paid for labor and process. Its September quarter revenue of $1.474bn grew 50.7%, the seventh consecutive quarter of accelerating growth, at a gross margin of 11.8% — within a hair of the 12.1% it averaged in fiscal 2025 and 2026. Data-center revenue of $777m, up 78%, is now 53% of the total, and the December guide of $1.60–1.65bn implies about 43% growth. Operating income grew 55%, faster than revenue, because fixed costs are only around 5% of total cost. Its fiscal-2026 annual report lists four customers above 10%: Cisco at 19.9%, NVIDIA 16.3%, Nokia 10.7% and Amazon 10.5%. Capacity goes from roughly $5.8bn of revenue to about $10bn in January 2027 and $16bn with two further buildings; first-quarter capital spending of $159m put free cash flow at minus $137m.
Viavi sells the test; ADTRAN buys the laser
Viavi, which sells network test and assurance instruments, grew revenue 56.9% to $469.3m at 61.2% gross margin against 56.0%, and its network software and convergence segment earned a 25.5% operating margin against 8.2%. "During this quarter, we expect to reach $2 billion revenue run rate, which is ahead of our prior expectations," chief executive Oleg Khaykin said on 4 November. ADTRAN sits on the other side of the invoice: revenue of $281.2m grew 0.6% and came in below consensus, with hyperscaler sales up more than 200% to roughly a tenth of the business. Of the margin pressure, chief executive Tom Stanton said on 3 November: "Generally speaking, I mean, it's 80%-90% supply cost." The inflating inputs are optics, lasers and semiconductors.
Only one margin line was self-inflicted
From 6 October to 5 November, Applied Optoelectronics fell 64.0%, MaxLinear 59.5%, Viavi 41.8% and Fabrinet 40.1%, against 24.1% for NVIDIA. Fabrinet has been in a downtrend since early August, a stretch that brackets two record quarters, and now trades near 14.9x fiscal-2027 consensus earnings against 58.5x trailing in May. Applied Optoelectronics' price against trailing gross profit is about 23x, down from 76x in mid-August.
The results account for one line of that: the 400G mix. The rest followed the 3 November midterms, after which analysts recast the buildout as a "war of attrition" and forward module volume became a question about permits rather than budgets, with 46 projects worth more than $170bn already blocked or stalled since January 2024.
Applied Optoelectronics is installing equipment for more than a million 800G and 1.6T units a month by the end of 2027. Whether the halls to plug them into get approved is now a separate question from whether the parts get built.