

Centrus Sold a Quarter Less Enrichment and Kept Almost All the Profit
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Six nuclear and uranium equities were marked down together this autumn as though the fuel cycle's prices had broken. They had not. Uranium's long-term contract indicator set a nominal record of US$99.00 a pound on 31 October, and spot enrichment has roughly tripled.
What broke was different in each business. Cameco's produced-uranium cash cost jumped 62% to C$40.73 a pound on an extended Key Lake mill outage, pulling gross margin from 37% to 16% and lifting its unit-cost-of-sales guidance. Centrus's enrichment segment still earned $72.6m of gross profit on 26% lower volume, essentially matching last year, while its shares fell by more than half in six months. Oklo, NuScale and Lightbridge were repriced for burn and dilution; none of the three has binding contracted revenue.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
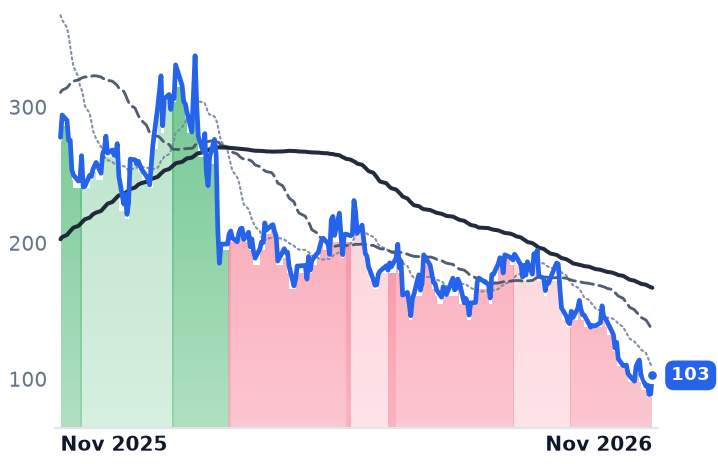
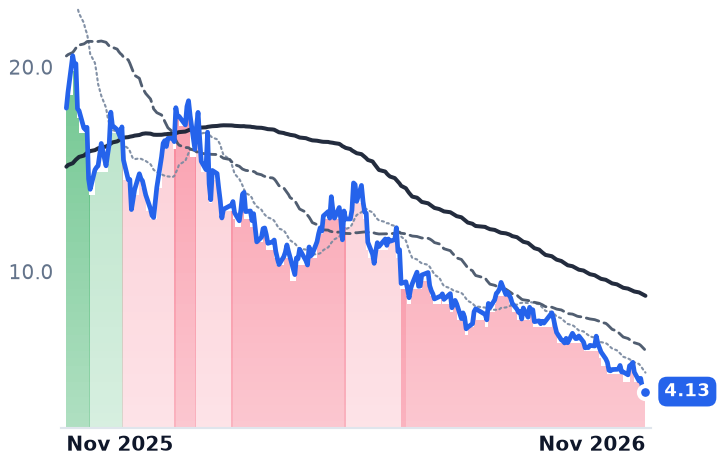
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −29.3% | −63.0% |
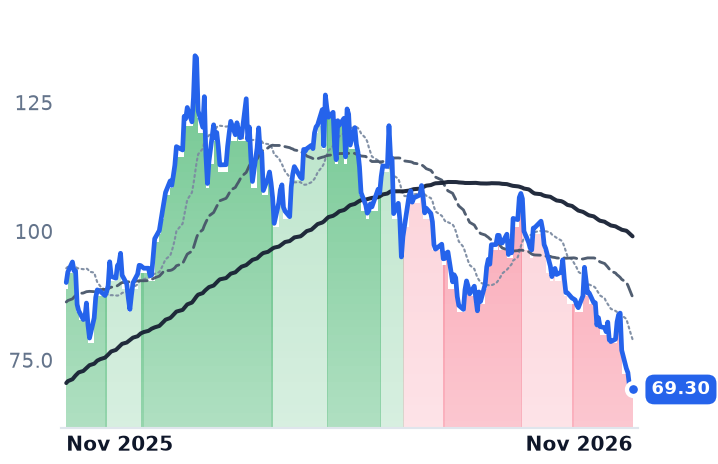
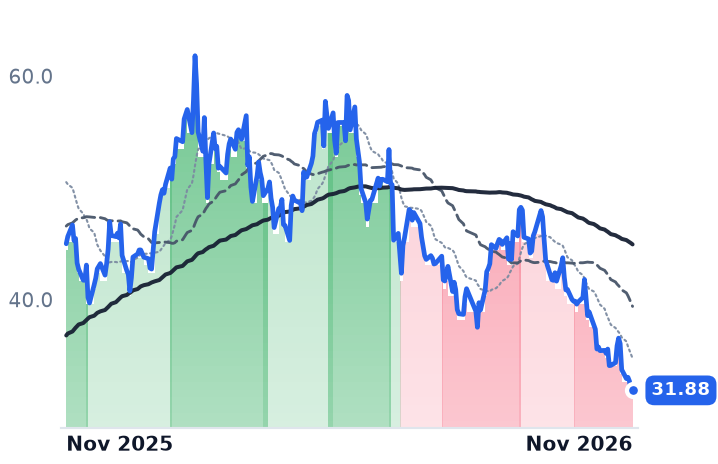
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −23.5% | −23.1% |
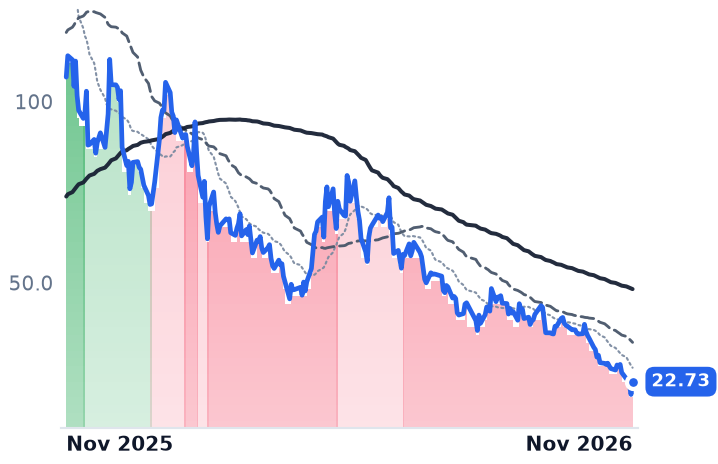
OKLO | Oklo | Advanced Nuclear | 🔴 Cont. Bear | −37.8% | −78.7% |
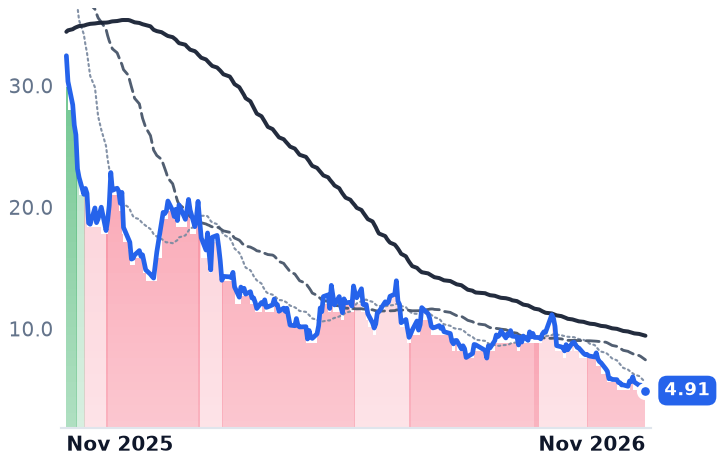
SMR | NuScale Power | Advanced Power Systems | 🔴 Cont. Bear | −34.6% | −84.9% |
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −36.2% | −77.0% |
URA | Global X - Uranium ETF | Asset Management | 🔴 Cont. Bear | −20.5% | −29.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $2.0B | 26.9x | 42.9x | 4.5x | 4.2x | 19.6x | 18.6x | 8.9x | -14.5% |
CCJ | $30.1B | 106.4x | 52.1x | 12.2x | 8.6x | 51.3x | 36.1x | 48.8x | 0.7% |
OKLO | $4.2B | n/m | — | — | — | — | — | n/m | -10.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMR | $1.5B | n/m | — | 534.8x | 86.3x | — | — | n/m | -41.5% |
LTBR | $154.9M | n/m | — | n/m | — | — | — | 2.8x | -12.5% |
URA | $3.2B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LEU | Revenue | +6.9% | +4.5% | −5.5% |
| EPS | −46.4% | +46.7% | −12.2% | |
CCJ | Revenue | +2.4% | +12.8% | +8.8% |
| EPS | −7.5% | +88.3% | +27.3% | |
OKLO | Revenue | — | +231.0% | +435.4% |
| EPS | +62.4% | +8.3% | +11.3% | |
SMR | Revenue | −59.6% | +507.1% | +271.3% |
| EPS | −77.1% | +14.4% | −16.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Centrus Energy, which sells enrichment services to nuclear utilities and builds centrifuges under US government contracts, sold a quarter less enrichment in the first nine months of this year than a year earlier at a 30% higher unit cost, and earned almost exactly the same profit doing it. Gross profit in its low-enriched uranium segment came to $72.6m against $74.1m a year earlier, a fall of $1.5m, on separative work unit volumes down 26%. The shares are down 55.6% since early May.
That gap is the whole question hanging over six nuclear-linked equities that all rolled into a six-month downtrend together. They were sold as if the prices underneath the fuel cycle had cracked. Those prices instead set records: uranium's long-term contract indicator reached US$99.00 a pound on 31 October, with spot near US$90–92, and spot enrichment has roughly tripled to about US$200 per separative work unit. Roughly 85% of uranium moves under long-term bilateral contracts of three to ten years, which is why the term indicator, not spot, is the number that reaches a producer's income statement. Three different things went wrong instead, and only one of them is a cost of production.
Centrus kept the margin and lost the earnings line
Centrus's consolidated quarter looked far worse than its enrichment unit: revenue fell 25.9% to $55.5m and the operating loss was $29.7m. The reported $31.6m of net income is a warrant mark; the company's own normalized figure is a $10.2m loss, or −$0.49 a share, against $3.9m of normalized income a year earlier. Commercial enrichment backlog grew from $3bn to $5.4bn during the quarter, though the $7.0bn total contains only about $0.8bn of firm uranium and enrichment deliveries, with $5.4bn contingent on the Piketon plant actually being built.
The physical news was ahead of schedule. Centrus completed its first new centrifuge in October, before its year-end target, and began shipping from Oak Ridge, Tennessee. "We now proved that US centrifuge manufacturing is a reality. It is a historic milestone for Centrus and The United States," chief executive Amir Vexler told investors on 5 November.
The de-rating still has an earnings logic. Centrus trades at 42.9x forward earnings against 26.9x trailing — a forward number above the trailing one prices profit falling, with consensus at $2.40 of 2026 earnings per share against $3.90 delivered in 2025. Set against $2.2bn of unrestricted cash and 8.86x trailing EV/EBITDA, the asset side reads differently from the earnings side.
Cameco's damage came out of a mill, not a price
Cameco raised its realized price. Its average realized uranium price rose 8% to C$91.76 a pound (Cameco reports in Canadian dollars) and full-year realized-price guidance went to C$91–96 from C$85–89. Produced-uranium cash cost rose 62% to C$40.73 a pound on a longer Key Lake maintenance outage and input inflation. Gross margin went from 37.3% to 16.1%, operating income fell 73% to $25.1m, and the compression is sequential: 35.7%, then 21.1%, then 16.1% across 2026's three quarters. Production guidance narrowed to 19.5–20.5m lbs and unit cost of sales guidance rose to C$67–70 from C$63–67.50.
"Capital can easily rotate out of a theme in a day or in a week. It takes much longer to replace a depleted uranium reserve, to build, license, and commission a fuel cycle facility," chief executive Tim Gitzel said on 30 October. Its 49% of Westinghouse contributed C$143m of adjusted EBITDA against C$124m, and Westinghouse has a confidential draft registration with the SEC targeting a valuation above $50bn. After a 48% fall from its 2026 high, the stock is still 52.1x forward earnings and 48.8x trailing EV/EBITDA.
Three developers, more than $5bn of cash, nothing signed
Oklo, which intends to own and operate 15-to-75 megawatt Aurora plants and sell the power, used $111m of operating cash in nine months against $49m a year earlier, funded by 32.6m shares sold for $2.25bn net. Shares outstanding reached roughly 192.3m against about 122.1m at its merger close. Its announced pipeline is 2,100 megawatts of letters of intent, memoranda and partnership agreements, none binding; at 1.17x book, about three-quarters of the market capitalisation is the cash balance.
NuScale, which licenses 77-megawatt reactor module designs, booked $281,000 of quarterly revenue, down 96.6%, while diluted shares rose 178% to 410.5m and the Tennessee Valley Authority power purchase agreement remains unsigned. At 86.3x forward sales it carries a revenue recovery that depends on contracts not yet in hand. Lightbridge, 13 employees developing twisted metallic fuel rods, has never reported revenue; operating expense rose 77% to $25.6m and $236.7m of cash sits against a $154.9m market value, or 0.62x book. "The authorization to construct and operate the pilot factory remains subject to additional DOE and INL agreements, reviews, authorizations and other prerequisites," chief operating officer Andrey Mushakov said on 2 November.
What the quarters account for
For Cameco and the developers, the numbers do most of the explaining: a real unit-cost shock with guidance moving the wrong way at one, and burn plus share count rising against non-binding pipelines at the other three. For Centrus the explanation splits — its enrichment economics held, and what the market marked down was consolidated earnings direction and the capital still needed at Piketon. The common final leg was not fuel at all. Over thirty sessions the six fell inside a 17-point band, against a 62-point spread over twelve months, and the last days coincided with a post-midterm sell-off that wiped roughly $2.5trn off AI-linked equities. Index concentration helped it travel: Cameco is 22.1% of the Global X Uranium ETF and its top ten holdings are 61.7% of assets. On 6 November all six bounced, Oklo 18.4% and Centrus 15.4%, on losses smaller than feared rather than revenue.
Centrus's September equity raise priced at $199.64 a share with four series of warrants attached, the lowest struck at $226.86. The shares have not been near that since. The money to finish the centrifuge plant is priced; whether it is available is a different question.