

DraftKings Is Spending Its Entire 2026 Profit to Build a Prediction Market
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
DraftKings' sportsbook is keeping more of each wagered dollar than it did a year ago, and the company has still told investors that this year's profit is gone. Sportsbook net revenue rose 36% on 12% handle growth as the margin the book earns on handle widened to 6.4%.
The money left below that line. Full-year adjusted earnings guidance swung from a profit to a loss on a $650-700m investment in its prediction exchange, with core profit described as on track.
Flutter is handing its parlay gains back as promotional credit and has guided FanDuel's US net revenue margin flat for 2027. Rush Street, three-quarters online casino, grew revenue 38.8%, reiterated guidance and fell hardest of the three. The squeeze is in customer acquisition.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
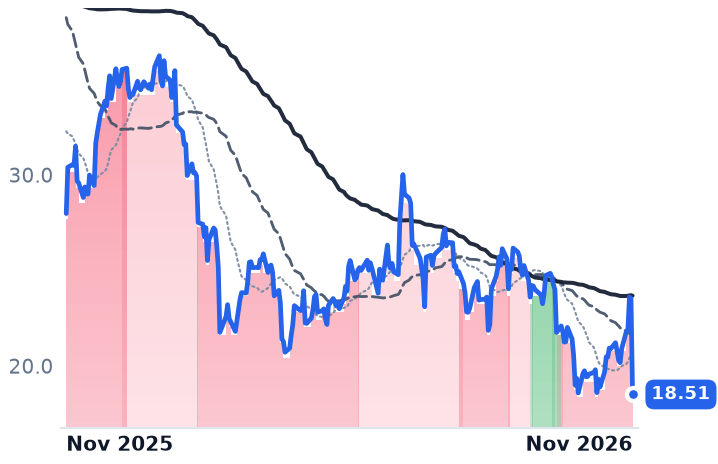
DKNG | DraftKings | Digital Sports Betting & iGaming | 🔴 Cont. Bear | −4.8% | −33.8% |
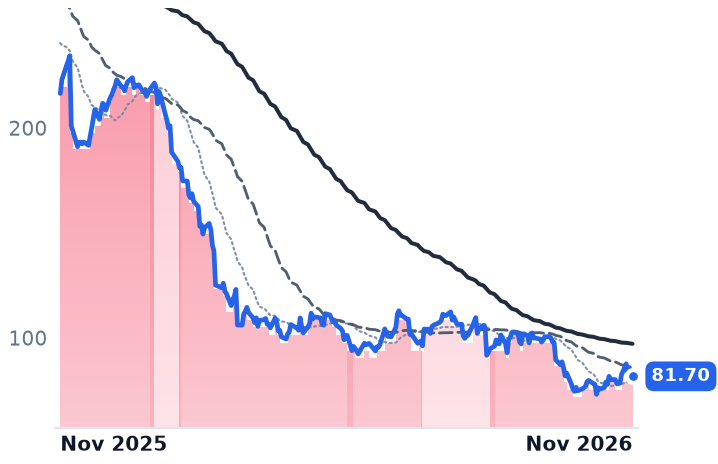
FLUT | Flutter Entertainment | Digital Sports Betting & iGaming | 🔴 Cont. Bear | +6.3% | −62.3% |
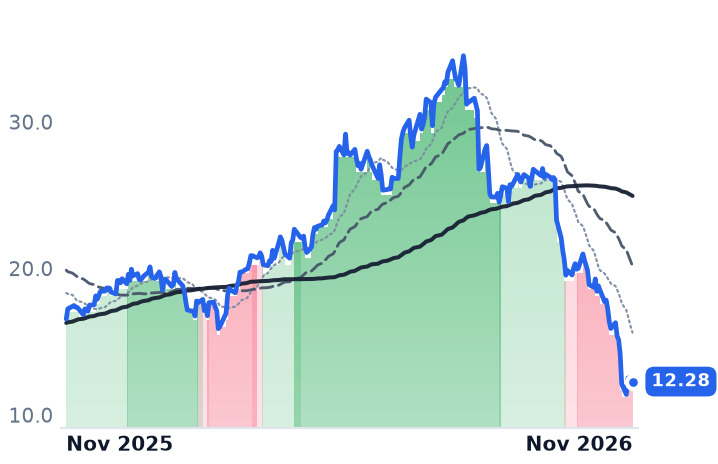
RSI | Rush Street Interactive | Digital Sports Betting & iGaming | ⚠️ Emerging Bear | −39.3% | −25.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DKNG | $9.2B | n/m | — | 1.4x | 1.4x | 3.5x | 3.4x | n/m | 3.5% |
FLUT | $14.2B | n/m | 18.7x | 0.8x | 0.8x | 2.0x | 1.9x | 21.8x | 5.4% |
RSI | $3.4B | 35.7x | 20.1x | 2.3x | 2.2x | 6.5x | 6.1x | 14.0x | 6.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DKNG | Revenue | +10.5% | +14.2% | +11.3% |
| EPS | +23.9% | −543.6% | +78.2% | |
FLUT | Revenue | +6.7% | +7.2% | +8.6% |
| EPS | −42.5% | +48.7% | +40.0% | |
RSI | Revenue | +41.0% | +14.0% | +14.5% |
| EPS | +51.7% | +34.7% | +26.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
DraftKings' sportsbook kept more of every dollar wagered last quarter than it did a year earlier, and the company still told investors on 6 November that this year's profit has been spent. Sportsbook net revenue at the Boston operator, which takes mobile and retail wagers in 18 states and runs online casino under the DraftKings and Golden Nugget Online brands, rose 36% on handle growth of 12%, because the margin the book earns on handle widened by about 1.2 percentage points to 6.4%, with parlay mix up three points.
For a year this corner of the market has been marked down on a belief about that number: that state taxes, promotional credits and untaxed prediction markets were stripping the revenue out of a wagered dollar. DraftKings is down 33.8% over twelve months and Flutter, owner of FanDuel, 62.3%. The third-quarter prints say the erosion is not in the hold; it sits in what it now costs to put a customer in front of the book.
The line where the profit left
DraftKings cut full-year revenue guidance to $6.35-6.55bn from $6.5-6.9bn and swung adjusted EBITDA guidance from a $700-900m profit to a loss of $175-275m, attributing the move to an increased predictions investment of $650-700m. Core-business EBITDA of $875-925m, management said, remains on track. The quarter itself missed on both lines: an adjusted loss of 53 cents against a 39-cent consensus, on revenue of $1.329bn against $1.398bn. The shares closed 21.3% lower.
The spending has a visible mechanism. New-customer promotional credits offset roughly 90% of the prediction exchange's gross gaming revenue, which is why that revenue is immaterial this year at an 11.1% take rate. Credits that large are the price of attention, and attention has repriced: betting-category media spending rose more than 60% year-on-year in September and more than 50% in October, driven mainly by prediction-market operators' advertising.
"In just a few months, we have become the clear number 3 predictions exchange by total volume. In October, annualized consumer volume reached $10.1 billion up nearly 3x from July," chief executive Jason Robins told investors on 6 November.
Total exchange volume annualised at $56.8bn, about 5.6 times that consumer figure, the gap between contracts re-traded and money a customer brought in.
Flutter gives the parlay gain back
Flutter's quarter is the cleaner confirmation. Revenue grew 2.1% to $3.874bn while gross profit fell 6.6% and gross margin went from 42.9% to 39.2%. FanDuel's US net revenue margin was 6.8% and its adjusted EBITDA fell 94% to $3m. The company guided 2027 US net revenue margin flat because promotional spend annualises at this year's elevated level.
"We are very confident that we can still grow the overall structural margins," chief financial officer Robert Coldrake said on 4 November, calling the pressure "more kind of temporary to medium term." The $300m revenue and $160m EBITDA guidance cuts were attributed to adverse sports results, the Brazil closure and UK gaming tax. The buyback is paused and net leverage is 4.6x against a 2-2.5x target. The shares sit on 18.7x forward earnings, against roughly 49.6x on that same estimate a year ago, and the estimate has itself been cut 42.5%.
Rush Street cut nothing and fell 39%
Rush Street Interactive, the Chicago operator of BetRivers and RushBet and three-quarters online casino by revenue, grew revenue 38.8% to $385.9m, lifted gross margin 2.4 points to 36.4%, nearly doubled operating income and reiterated full-year guidance of $1.56-1.6bn revenue and $245-265m adjusted EBITDA, placing October revenue at the low end. It is debt-free with $382m of cash.
It also fell 39.3% in a month.
Two items in its own disclosure explain part of that: revenue per active user down 15% to $309 on market maturation, which management ties to market-wide North American online-casino moderation while saying it is still gaining share year-on-year against listed peers everywhere but Michigan, and a Colombian bill proposing a 19% value-added tax on online wagering deposits. Forward earnings compressed from about 33x a month ago to 20.1x with no company number changed.
How much of the markdown the prints explain
Flutter's de-rating is earned by its own statements: consensus EBITDA for this year is down 24.7% and the gross-profit line is falling outright. DraftKings' is not a verdict on the business it has, where core profit is intact and it says it tied FanDuel for top US share, but on a discretionary bet whose return arrives in 2027 guidance of $800m to $1.0bn of adjusted EBITDA that consensus, at $770m, has not underwritten. Consensus revenue of $6.66bn still sits above the newly lowered guide. Rush Street's fall is the one with no operating cause attached to it, which leaves the cooling growth rate of regulated online casino as the likelier thing being repriced.
Robins gave the downside arithmetic himself: even if sports event contracts were ended in July 2028, he said, the customers DraftKings acquired this year would be fully paid back by that date, with a Supreme Court ruling in mid-2028 his base case. The money is being spent now against a judgment nobody has written yet.