

Waste Connections and Casella Were Repriced for a Volume Turn Only GFL Has Reported
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Three regional waste haulers were marked up through October on the belief that price per ton had finally outrun cost after four years of shrinking tonnage. The two largest operators in the industry rose as much or more, and most of the trio's gain landed before any of them reported.
Waste Connections took 5.5% core price against solid-waste volumes down 1.2% and raised both its outlook and its dividend. GFL Environmental was the only one of the three to report tonnage growing. Casella Waste Systems has not published a September quarter at all; its last one grew revenue 16.9% while operating income fell 22.4%.
The results account for the move at Waste Connections and GFL. They do not at Casella, where consensus has 2026 revenue up 14.4% and adjusted EBITDA up 0.3%. GFL's price has a non-operating anchor: a take-private deadline.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
WCN | Waste Connections | Regional Integrated | 🌱 Emerging Bull | +19.3% | +11.5% |
CWST | Casella Waste Systems | Regional Integrated | 🌱 Emerging Bull | +11.9% | +5.2% |
GFL | GFL Environmental | Regional Integrated | 🌱 Emerging Bull | +6.9% | +3.3% |
| Compared against · context, not the story | |||||
WM | Waste Management | National Integrated | 🔴 Cont. Bear | +13.0% | +19.6% |
RSG | Republic Services | National Integrated | 🟢 Cont. Bull | +14.7% | +19.6% |
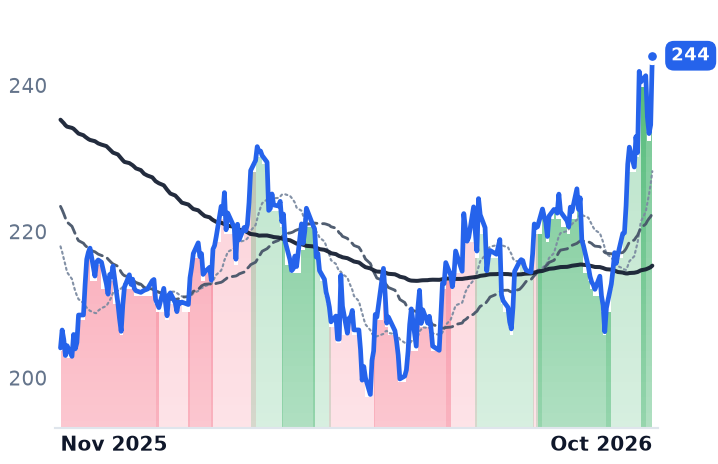
12-month price & trend
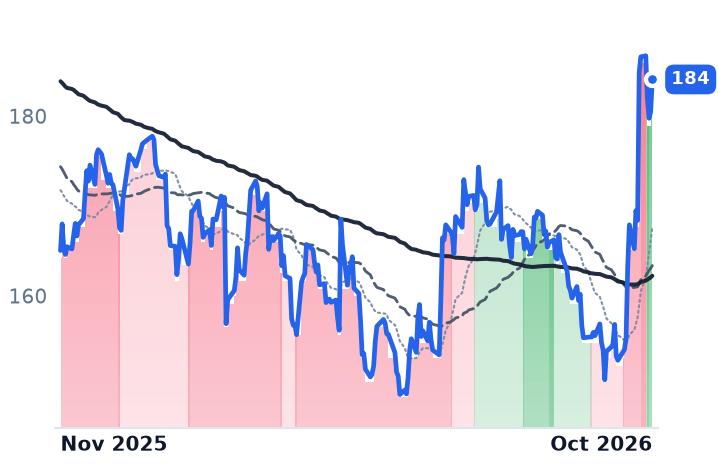
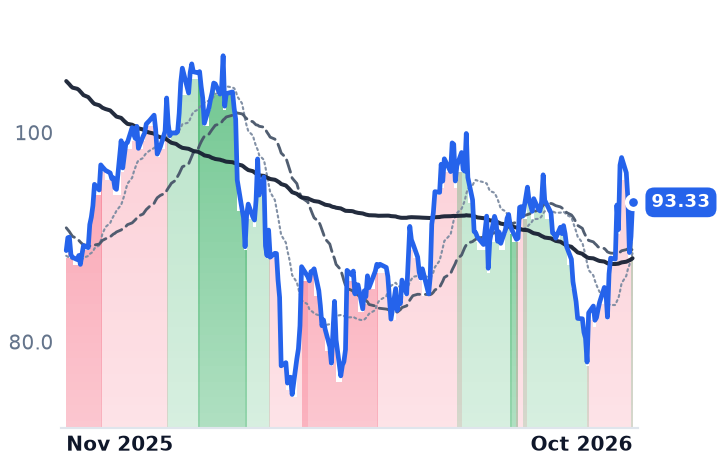
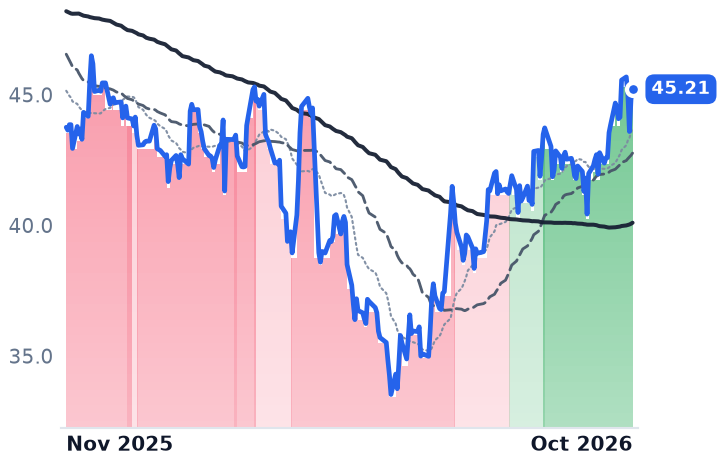
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WCN | $46.1B | 41.3x | 32.2x | 4.6x | 4.6x | 11.7x | 11.6x | 17.4x | 4.0% |
CWST | $5.8B | — | 69.0x | 3.0x | 2.8x | 11.8x | 11.0x | 18.3x | 1.8% |
GFL | $15.8B | n/m | 54.3x | 3.0x | 1.9x | 15.2x | 9.8x | 18.6x | 1.0% |
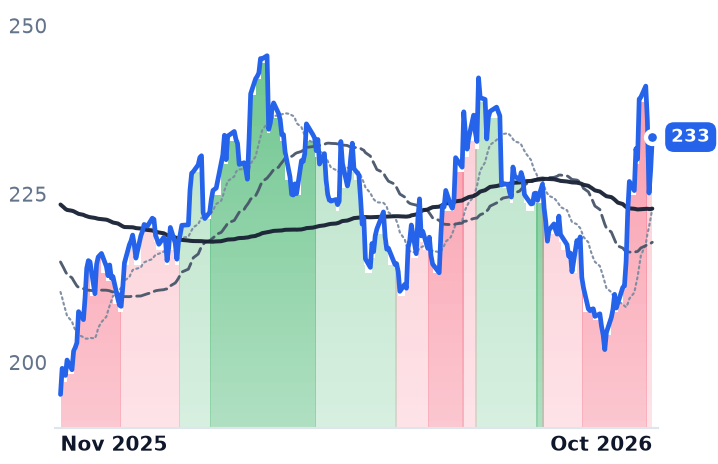
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WM | $92.8B | 30.5x | 29.0x | 3.6x | 3.5x | 11.1x | 10.9x | 14.6x | 4.0% |
RSG | $74.7B | 33.8x | 33.5x | 4.3x | 4.3x | 11.1x | 10.9x | 15.5x | 4.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
WCN | Revenue | +6.4% | +6.0% | +5.1% |
| EPS | +10.5% | +8.0% | +10.6% | |
CWST | Revenue | +14.4% | +7.3% | +6.2% |
| EPS | +13.1% | +16.1% | +24.3% | |
GFL | Revenue | +25.0% | +21.4% | +6.3% |
| EPS | +41.5% | +40.8% | +33.4% | |
WM | Revenue | +4.7% | +5.3% | +4.3% |
| EPS | +7.4% | +10.3% | +10.0% | |
RSG | Revenue | +4.6% | +4.9% | +4.6% |
| EPS | +5.5% | +10.9% | +10.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Waste Connections told investors on 22 October it was lifting its full-year outlook and its quarterly dividend, and the shares closed 9.8% higher that day. A week later GFL Environmental raised guidance for the third time this year and became the only one of these three haulers to report its tonnage growing. Casella Waste Systems, the smallest of the three, has not published a September quarter at all.
October was read as the month regional hauling economics turned, with price taken per ton finally outrunning cost after four years in which the tons themselves shrank. The reading has support outside the trio. Republic Services took 6.3% core price on related revenue against roughly flat volume and saw small and large containers both grow for the first time in over three years. "I think recycling and waste will tip to positive growth in 2027 across the industry, and we'll certainly try to match that or do a little better than that performance," chief executive Jon Vander Ark said on 29 October. Waste Management, meanwhile, still guides collection and disposal volume to about -1% for the year.
The bid was not discriminating, and most of it arrived before any numbers did. Over the 30 days to 30 October, Waste Connections rose 19.6%, Republic 16.3%, Casella 16.2% and Waste Management 14.4%, with GFL up 8.1%. By 21 October, the day before the first of the three reported, Waste Connections was already up 9.4% and Casella 12.9%. Across the trailing year the three regional names gained between 3.3% and 12.7% against 16.4% for Waste Management: October was catch-up inside a de-rated group, a defensive bid on the whole sector rather than a verdict on the smaller three.
5.5% price against 1.2% fewer tons
Waste Connections, which owns 61 municipal solid-waste landfills and 142 transfer stations serving secondary and exclusive markets across the US and Canada, published the cleanest version of the industry's algorithm. September-quarter revenue of $2.638bn was up 7.3%, built on 5.5% core price against solid-waste volumes down 1.2%, a 70-basis-point sequential improvement in volume. Adjusted EBITDA margin reached 34.0%, 20 basis points better than a year earlier and roughly 50 before the diesel spike, which cost $21.6m of fuel expense. Special-waste tons rose 7% and construction-and-demolition tons 5%. The full-year outlook went to about $10.09bn of revenue and the dividend rose 10% to $0.385 a share.
Two helpers in that quarter do not repeat. Recycling revenue was up 12% on higher values for old corrugated containers, the recovered cardboard haulers sell to mills; that grade averaged $38 a ton in October, half September's $77. And the company's own framing for next year is unexciting: mid- to high-single-digit revenue growth, roughly a point of it rollover from acquisitions and renewable natural gas plants, on a target spread of 150 basis points between price and cost. The shares carry 17.4x trailing EV/EBITDA against 14.6x at Waste Management and 15.5x at Republic. California's attorney general, Rob Bonta, sued the company in late October over hazardous-waste management at the closed Chiquita Canyon landfill.
Casella bought $948m of revenue and $5m of operating profit
Casella is vertically integrated across the Northeast with 50 collection operations, eight Subtitle D landfills and 65 transfer stations. Between 2021 and 2025 its revenue more than doubled, from $889m to $1,837m, while operating income moved only from $84.4m to $89.2m and net income fell from $41.1m to $7.9m. The June quarter kept that shape: revenue up 16.9% to $543.7m, operating income down 22.4% to $20.0m.
Pricing is not the weak link. Solid-waste price rose 5.8% in collection and 4.7% in disposal, in a market Brad Helgeson, the chief financial officer, described on the second-quarter call: "The dynamic in the Northeast is that landfill capacity is coming out of the market, and you have more and more tons looking for less and less landfill capacity." But internalization did not improve: of 86,000 additional landfill tons, 62,000 came from third parties against 24,000 from Casella's own routes. Net leverage stood at 2.7x and margin excluding fuel and resource solutions widened 30 basis points. Consensus has revenue up 14.4% this year with adjusted EBITDA up 0.3%. At 18.25x trailing EV/EBITDA and a 1.81% trailing free-cash-flow yield, it is the dearest of the five haulers on both. Its September quarter is due after the close on 9 November.
GFL's tons turned and its interest bill rose 39%
GFL, the Vaughan, Ontario operator of solid-waste collection, disposal and soil remediation, has the one positive volume print in the group. Core price of 5.7% came with volume up 50 basis points, landfill tons positive for the first time since early 2025 and construction-and-demolition tons up 4.5%. "Organic revenue growth accelerated 100 basis points over the second quarter, driven by core pricing ahead of expectations and 50 basis point improvements in both volume and commodity prices," chief financial officer Luke Pelosi said on 29 October. Adjusted EBITDA margin was 31.5%, flat as reported and about 125 basis points better underlying.
What the Environmental Services divestiture did not buy was cheaper money. GFL re-levered to fund SECURE Waste Infrastructure, closing the quarter at 3.8x net leverage after issuing 75 million shares and a $1bn term loan, and interest and finance costs reached $179.4m against $129.2m a year earlier. SECURE added $150m of revenue and over $50m of EBITDA in its first month inside the group, a mid-30s margin above GFL's own. Management puts the stock at 12 to 12.5x its 2027 EBITDA sketch against 18.6x trailing. The nearer anchor is procedural: the special committee's deadline for updated take-private proposals is 9 November.
Where the split comes from
The published results explain the month at two of the three. Waste Connections prices inside exclusive and secondary markets where it also owns the disposal, and its margin gain survives the fuel hit only on an underlying basis, because diesel at a record $6.52 a gallon in September passes through to customers on a one-to-two-month lag. GFL's improvement is partly bought: SECURE's higher-margin assets consolidated on 1 September, and management has warned of fourth-quarter volume deceleration as extended-producer-responsibility contracts lapse. Casella's gain priced a quarter that does not exist yet, and its last one showed routes bought with debt whose depreciation and interest absorb the pricing taken on them.
None of this can be settled at the ton. No company in the group publishes tonnage reconcilable to revenue or EBITDA, so core price against unit volume and adjusted EBITDA margin are as close to margin per ton as anyone outside the companies gets. "Free cash flow per share in a normal growth algorithm over the next five years, there's no path in which I don't think that free cash flow isn't close to a double," GFL's founder and chief executive Patrick Dovigi said on 29 October. That is a claim about five years, made four days before a sale process closes.
Both of the open questions resolve on the same date. On 9 November, Casella prints the quarter its shares have already moved on, and GFL learns what a buyer will pay for a business whose tons have only just started growing again.