

The Data-Center Turbines in BorgWarner's Valuation Have Not Shipped a Single Unit
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
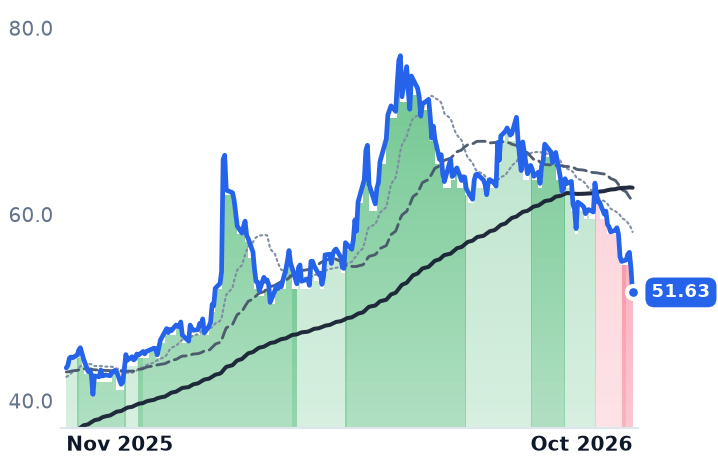
BorgWarner, which sells turbochargers, fuel injection, e-motors and battery packs to carmakers and truck builders, raised its full-year adjusted earnings guidance on 29 October and lost 7.7% over the next two sessions. The sales guidance it trimmed at the same time was electrification: roughly $250m of lost Battery Energy Systems revenue, about 1.7 points of organic growth.
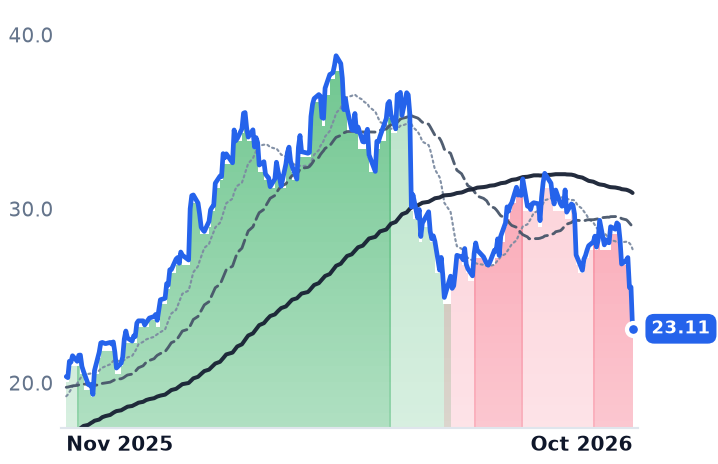
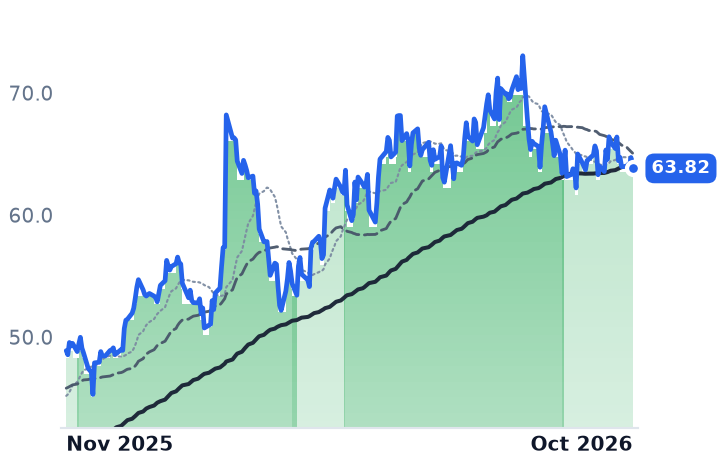
What was repriced sits outside the engine business entirely. BorgWarner guided about $300m of 2027 data-center turbine-generator revenue before the programme had run a production trial, and Garrett Motion guided a near-identical figure; the two fell hardest of the powertrain suppliers over the month. PHINIA, which promised nothing to data centers, rose as its aftermarket arm earned a 17.1% operating margin against 12.1% at its original-equipment segment.
On the shipped-unit evidence the combustion business is improving. At 9.8x forward earnings BorgWarner is the cheapest of the four.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BWA | BorgWarner | Powertrain & Engine Systems | ⚠️ Emerging Bear | −14.3% | +18.6% |
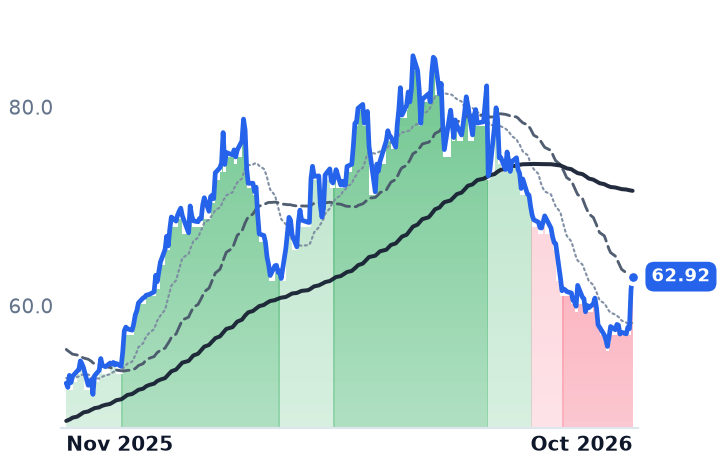
PHIN | PHINIA | Powertrain & Engine Systems | ⚠️ Emerging Bear | +4.6% | +20.5% |
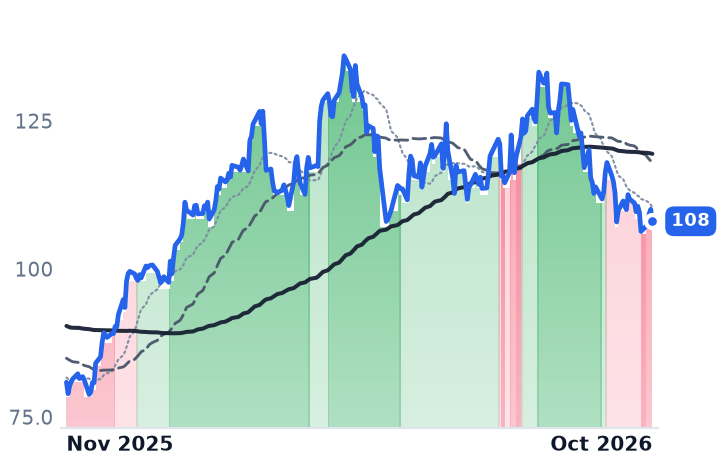
ALSN | Allison Transmission | Powertrain & Engine Systems | ⚠️ Emerging Bear | −6.7% | +33.6% |
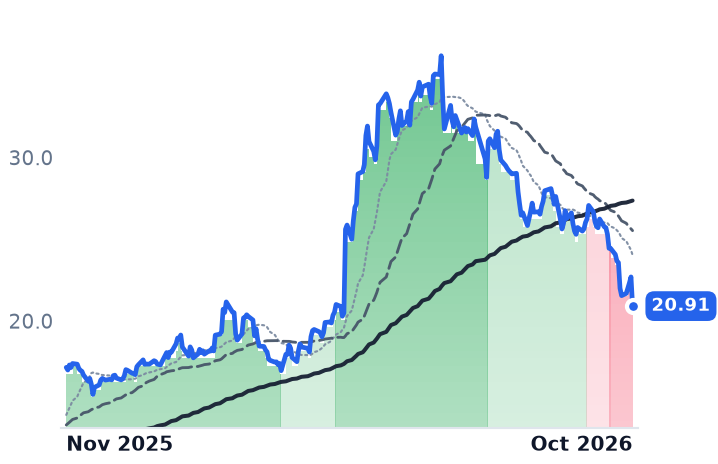
GTX | Garrett Motion | Powertrain & Engine Systems | ⚠️ Emerging Bear | −21.6% | +21.9% |
DAN | Dana Incorporated | Powertrain & Engine Systems | 🔴 Cont. Bear | −17.8% | +13.5% |
MGA | Magna International | Powertrain & Engine Systems | 🟢 Cont. Bull | −1.7% | +30.5% |
| Compared against · context, not the story | |||||
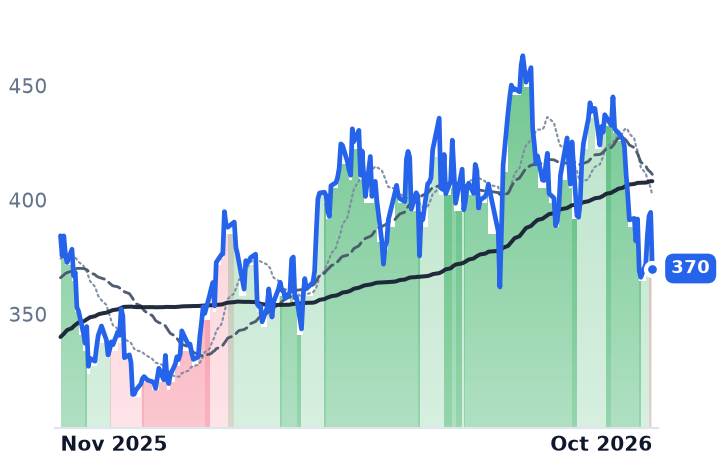
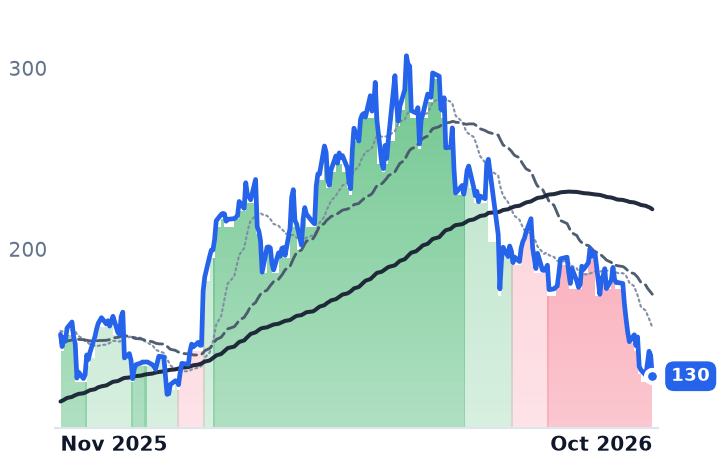
ETN | Eaton | Power Distribution Systems | 🟢 Cont. Bull | −14.5% | −3.7% |
MOD | Modine Manufacturing | HVAC & Refrigeration Systems | ⚠️ Emerging Bear | −29.1% | −15.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −2.5% | +11.2% |
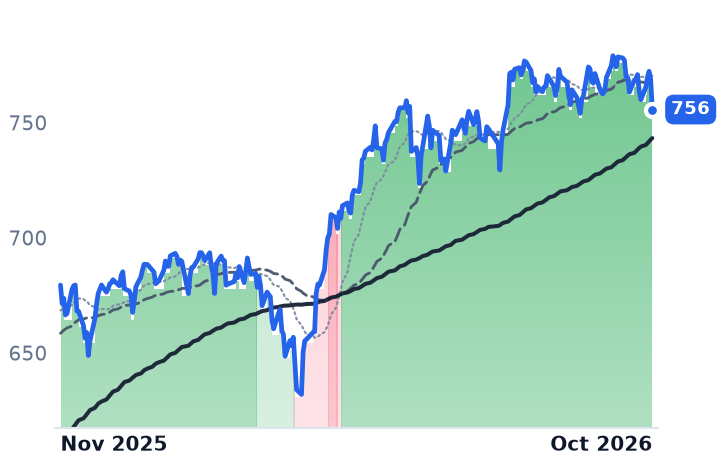
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWA | $10.4B | 21.6x | 9.8x | 0.7x | 0.7x | 3.7x | 3.7x | 8.8x | 11.4% |
PHIN | $2.3B | 12.6x | 10.4x | 0.6x | 0.6x | 2.9x | 2.8x | 6.5x | 12.4% |
ALSN | $8.9B | 17.0x | 13.3x | 2.4x | 1.5x | 6.1x | 3.8x | 11.5x | 8.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GTX | $3.9B | 10.5x | 10.6x | 1.0x | 1.0x | 5.4x | 5.3x | 9.7x | 10.2% |
DAN | $2.5B | n/m | 12.5x | n/m | 0.3x | — | — | 8.0x | 4.1% |
MGA | $16.9B | 20.6x | 9.0x | 0.4x | 0.4x | 3.6x | 3.6x | 5.8x | 16.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETN | $149.2B | 39.0x | 28.2x | 5.0x | 4.5x | 13.8x | 12.6x | 26.3x | 3.0% |
MOD | $6.9B | 48.6x | 18.5x | 2.0x | 2.1x | 9.2x | 9.5x | 24.7x | 1.5% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWA | Revenue | −1.0% | +3.9% | +6.6% |
| EPS | +10.7% | +11.8% | +15.2% | |
PHIN | Revenue | +6.2% | +3.2% | +1.7% |
| EPS | +22.1% | +13.1% | +11.2% | |
ALSN | Revenue | +98.0% | +4.3% | +4.9% |
| EPS | +4.9% | +32.5% | +17.1% | |
GTX | Revenue | +6.8% | +4.0% | +6.3% |
| EPS | +31.7% | +12.3% | +18.6% | |
DAN | Revenue | +4.2% | +26.0% | +13.4% |
| EPS | +206.4% | +85.7% | +29.8% | |
MGA | Revenue | −0.3% | +1.1% | +2.3% |
| EPS | +31.0% | +11.9% | +12.1% | |
ETN | Revenue | +20.2% | +11.4% | +9.9% |
| EPS | +12.8% | +19.7% | +17.0% | |
MOD | Revenue | +22.6% | +3.9% | +33.2% |
| EPS | +33.4% | +47.1% | +40.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
BorgWarner told investors on 29 October that it would earn more this year than it had promised and sell slightly less, and its shares fell 7.7% over the two sessions that followed. The reduction was not in engines. The company narrowed full-year sales guidance to $14.0bn-$14.2bn while raising adjusted earnings guidance to $5.20-$5.35 a share from $5.05-$5.30, and the single largest identified drag on the top line was an expected $250m year-on-year decline in Battery Energy Systems, worth roughly 1.7 percentage points of organic growth — an electrification product line, not a combustion one.
The belief being tested here was built in early October, when BorgWarner was re-rated as a power-generation story: Morgan Stanley moved the shares to Overweight on 6 October with a $95 target, up from $71, and BofA Securities to Buy on 15 October at $85. The stock closed at $63.36 the day of the first upgrade and $51.63 on 30 October, 18.5% lower over the stretch in which both landed. The quarter in between said the opposite of the thesis: combustion content is being contracted further out, and the data-center business has yet to produce a dollar.
A revenue line guided before the line ran
"Then we expect to see $300 million of turbine generator revenue," chief financial officer Craig Aaron told investors on the 29 October call. "So excited to get to 2027 and see an upswing in our top line for BorgWarner." As of that call the final assembly plant was complete, production trials were expected by year-end, certification was advancing and demonstrations with multiple hyperscalers were set to expand in the fourth quarter. Management also flagged near-term political and permitting delays affecting data-center project finalization, which it views as short-term. October was the month that stopped giving such programmes the benefit of the doubt: data-center equipment makers fell 23% and at least 47 major projects faced delay or cancellation during 2026.
What the engine business actually did
Third-quarter revenue fell 2.9% to $3,487m while gross margin widened to 19.0% from 18.5% and net income rose 39.9% to $221m. Adjusted operating margin reached 10.9%, 20 basis points better than a year earlier on lower production, which management attributed to cost control and productivity. Among nine new awards announced in the quarter were engine control modules for a pickup truck running through 2034 and three turbocharger conquest wins in South America and Europe, taken in the sockets Garrett Motion contests.
The electrified side is growing without yet paying. "Our light vehicle eProduct sales were $630 million in the quarter, or a 33% increase compared with a year ago, primarily due to strength in Europe," chief executive Joe Fadool said on the same call. PowerDrive Systems still ran a $5m operating loss.
The truck cycle that was supposed to be rolling over
BorgWarner described the global commercial-vehicle market as growing about 3%, with North America up roughly 11%. ACT Research forecasts US retail sales of new Class 8 trucks at 229,400 units in 2026, up 7.8%, with surcharge-free build slots sold out and backlogs oversubscribed by some 35,000 units. The forward-buying ahead of stricter 2027 emissions rules is behind, not ahead: September net orders were 18,700 units, down 9.5% year on year as regulatory uncertainty froze normal seasonal ordering.
Allison Transmission, which builds fully-automatic transmissions for medium- and heavy-duty trucks and military vehicles, held up best of the group, down 4.4% over the 30 sessions to 30 October. Its June quarter carried a 26% adjusted EBITDA margin and record free cash flow of $281m, up 84%, with chair and chief executive David Graziosi citing "continued momentum in the North American truck market" and "record quarterly net sales of $860 million" at the legacy transmission unit. It is also the dearest of the four at 11.5x trailing EV/EBITDA, and its $2,628m purchase of Dana's off-highway business dilutes consensus 2026 EBITDA margin to 19.1% from 34.8%. Its September quarter reports after the close on 2 November.
PHINIA, spun out of BorgWarner in 2023 with the fuel-systems and independent-aftermarket business, was the one name up over the month. Revenue of $912m rose 0.4% to a record 14.8% adjusted EBITDA margin, and the replacement annuity out-earned the build cycle: Aftermarket Solutions sales of $351m at a 17.1% operating margin against Power Systems at $561m and 12.1%, down from 13.3%. Aftermarket is 38.5% of sales. It trades at 6.5x trailing EV/EBITDA on a 12.4% free-cash-flow yield.
What the split follows
Nothing in the reported numbers explains the selling. All four expanded margin on soft or flat revenue and raised or held guidance. The split instead follows guided data-center dollars. BorgWarner and Garrett each put roughly $300m of 2027 power-generation revenue into their 2027 story — Garrett's chief executive Olivier Rabiller said on 29 October that "when you look at the $300 million that we are doing industrial sales today, this is mostly genset" — and fell 14.1% and 19.7%. PHINIA, whose incremental growth is an aging vehicle fleet and four won aerospace and defense programmes, rose 5.9%. What was marked down is the credibility of revenue that depends on other companies' capital plans, not dollars of content per truck.
Two doubts stay open. Garrett's flat 10.5x trailing to 10.6x forward earnings says the market now prices no growth from a line it says is growing 30%, and the 2027 truck build draws on an order book the pre-buy emptied.
The assembly plant is finished and the certification work is running. Whether $300m arrives in 2027 is now a question about which hyperscaler signs, and when — a decision made in someone else's capital budget, on a business whose engine parts just raised the year.