

Digital Realty Builds Data Centers at Nearly Three Times the Cost of Its New Debt
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A data center landlord being marked down for the cost of money just reported the widest gap in its history between what a built megawatt yields and what the money to build it costs. Digital Realty's pipeline is underwritten to an 11.6% stabilized yield; its last debt raise carried a 4% blended coupon.
Both it and Equinix reported on 28 and 29 October: record bookings, a record $2.5bn signed-but-not-commenced backlog, cash renewal spreads of about 12%, record-low 0.7% churn at Digital Realty, and a third straight guidance raise at Equinix. Digital Realty's shares are flat over twelve months even as revenue grew 20.6%.
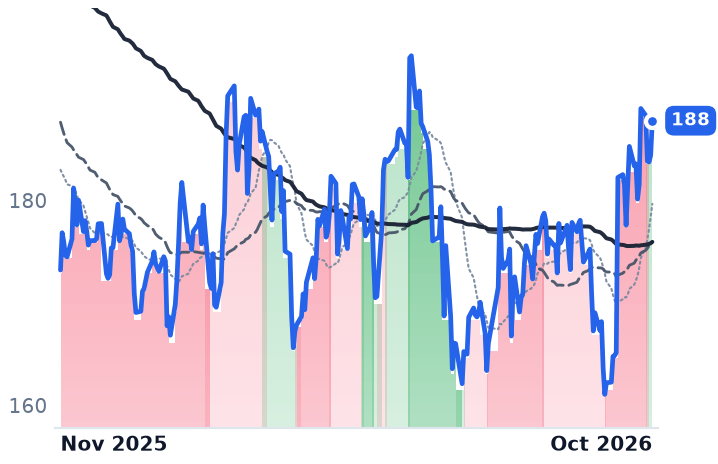
The de-rating sits in discount rates and AI risk aversion, not in the leasing books. The segment's 20% twelve-month decline is largely one pre-revenue developer, Fermi, down 89%.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
DLR | Digital Realty Trust | Data Center Operators | ⚠️ Emerging Bear | +1.2% | +6.6% |
EQIX | Equinix | Data Center Operators | ⚠️ Emerging Bear | −1.2% | +23.1% |
FRMI | Fermi | Data Center Operators | 🔴 Cont. Bear | −35.2% | −90.7% |
BXDC | Blackstone Digital Infrastructure Trust | Data Center Operators | 🔴 Cont. Bear | −8.8% | −20.5% |
| Compared against · context, not the story | |||||
AMT | American Tower | Tower & Fiber Infrastructure | 🔴 Cont. Bear | +15.8% | +8.4% |
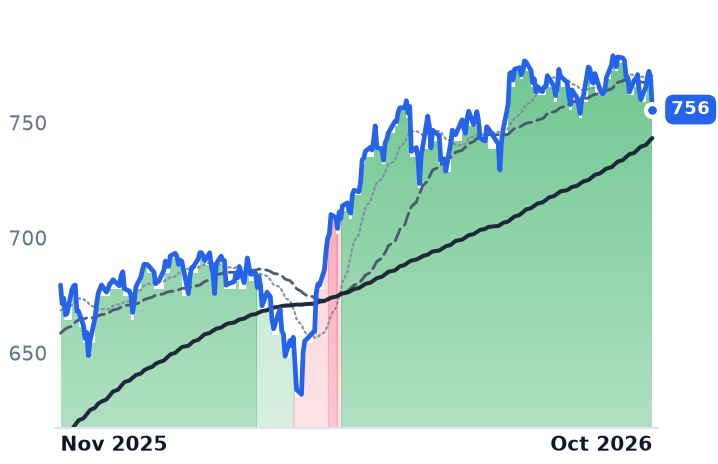
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.8% | +11.2% |
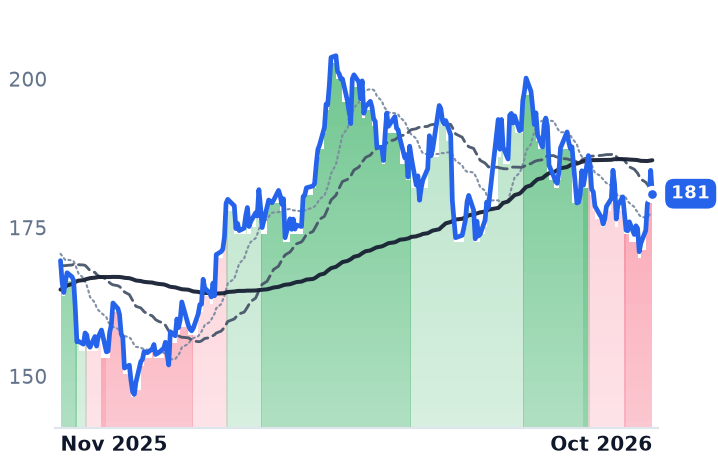
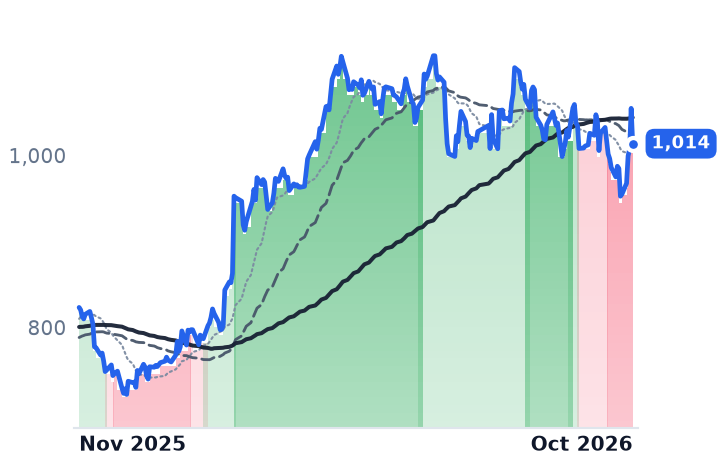
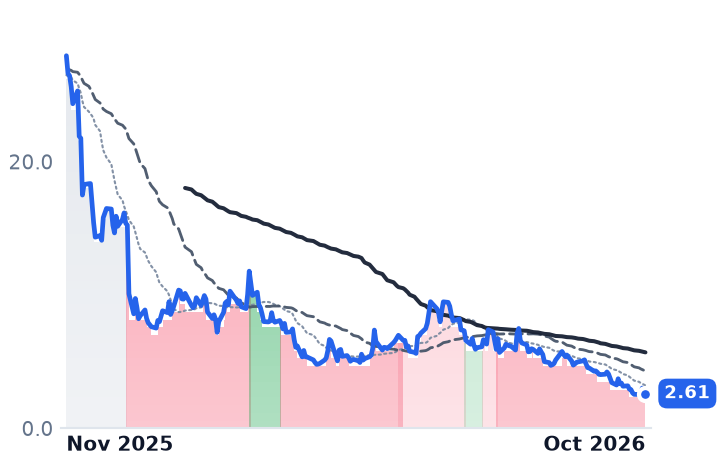
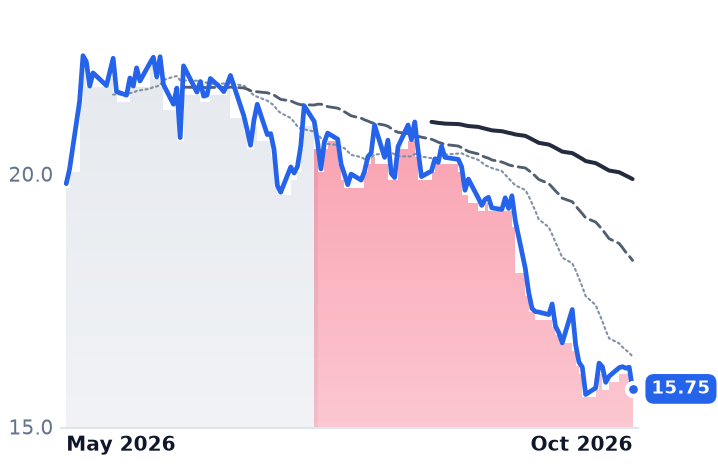
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DLR | $67.0B | 72.3x | 64.6x | 9.3x | 9.2x | 59.3x | 58.6x | 24.4x | 2.1% |
EQIX | $100.3B | 60.6x | 56.2x | 10.0x | 9.7x | 19.3x | 18.8x | 26.6x | 1.2% |
FRMI | $1.7B | n/m | — | n/m | 220.8x | — | — | n/m | -70.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BXDC | $1.6B | — | — | — | — | — | — | — | — |
AMT | $84.9B | 25.0x | 26.1x | 7.8x | 7.7x | 10.6x | 10.5x | 18.3x | 4.7% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DLR | Revenue | +19.8% | +11.1% | +13.4% |
| EPS | −23.5% | −3.4% | +20.9% | |
EQIX | Revenue | +11.7% | +11.2% | +11.9% |
| EPS | +22.3% | +9.3% | +9.5% | |
FRMI | Revenue | −52.5% | +5212.8% | +441.5% |
| EPS | +326.2% | −116.4% | +1983.0% | |
AMT | Revenue | +4.1% | +3.3% | +6.1% |
| EPS | +36.1% | +1.1% | +11.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Digital Realty signed more new rent in the September quarter than in any quarter of its existence, and told investors on 29 October that the capacity it currently has under construction is underwritten to stabilize at a yield of 11.6%. The most recent debt it raised to pay for that construction, $1.7bn, carried a blended coupon of 4%.
That gap is the whole argument. Data center landlords have been marked down since the summer on a mechanical story: long rates rose, so the spread between the yield on a newly built megawatt and the cost of capital funding it must be closing, and hyperscale tenants would rather self-build anyway. The quarters reported on 28 and 29 October say the spread went the other way. A prior reading of Digital Realty's book had an 11.5% stabilized yield on a 1.4-gigawatt pipeline against a 5.28% 30-year Treasury; the September quarter shows 11.6% on 1.5 gigawatts, with the long bond at 5.31% on 30 October after touching a 24-year high of 5.67% on 7 October.
$14.7m buys a megawatt; the stabilized rent on it is about $1.7m a year
The arithmetic is reproducible from the company's own disclosure. Digital Realty, which owns 309 data centers and about 3.0 gigawatts of installed capacity leased to cloud, financial and manufacturing tenants, has 1.5 gigawatts under construction at an expected cost of $22bn: roughly $14.7m per megawatt. At the stated 11.6% stabilized yield, each leased megawatt should throw off about $1.70m of annual net operating income. That capacity is 63% pre-leased before it opens.
The in-place book got better on every line. Cash re-leasing spreads on renewals ran about 12%, management raised full-year renewal-spread guidance by a point to 10-12%, churn fell to a record-low 0.7%, and stabilized occupancy rose 90 basis points to 93.4%. Bookings will generate $855m of annualized base rent at 100% share, $627m at Digital Realty's share, leaving a record $2.5bn backlog of signed-but-not-commenced rent, roughly 40% of in-place rent. "Total leasing for the quarter was a blowout at $855 million or $627 million at our share, with new records set across several metrics," investor relations head Jordan Sadler said on the 29 October call.
The dilution objection fails on its own numbers. Diluted shares rose 8.8% year on year, and core funds from operations per share still grew 11%, to $2.10 — implying aggregate core FFO grew about a fifth. Full-year guidance went to $8.30-$8.35, near 13% growth. Against $19.5bn of debt, net leverage is 5.2x adjusted EBITDA.
Equinix re-lets a vacated cabinet at 7 kilowatts
Equinix, which sells colocation and interconnection inside its own campuses to more than 3,200 customers, runs a different engine on the same spread. Cabinet utilization was flat at about 78% year over year, so growth came from price and power: customers churned out at 5 kilowatts per cabinet and in at 7, with churn held at 1.7%. "Pricing on new deals was up 12% year-over-year in the quarter," chief executive Adaire Fox-Martin said on 28 October. Adjusted EBITDA margin widened 180 basis points to 51.4%, AFFO per share grew 12% on just 1.1% more shares, and guidance was raised for a third consecutive quarter. Stabilized assets yield 27% cash-on-cash against a 3.2% blended borrowing cost. Most hyperscale capital sits outside the balance sheet in a $15bn joint venture in which Equinix holds only 25% of the equity.
The segment's 20% decline is one pre-revenue developer
The four-name data center group is down about 20% over twelve months on an equal-weighted basis. Strip out Fermi and the rest average roughly flat. Fermi has reported exactly zero revenue in every quarter of its existence, lost $177.8m in 2025, and fell after its prospective anchor tenant terminated a $150m construction-funding agreement and a federal subpoena landed; its shares are down 89%. Blackstone Digital Infrastructure Trust, which listed 87.5m shares at $20.00 in May as a blind pool with no assets acquired, trades at $15.75 on a $1.59bn market value and a single reported quarter of $9.3m of revenue. Neither collects rent on a mature megawatt.
Where the de-rating actually came from
Digital Realty is flat over twelve months on revenue up 20.6% and operating margin 660 basis points wider, and sits 11.4% below its 52-week high. Equinix is up 20.8% while its trailing earnings multiple compressed from about 74x in May to 60.6x, meaning earnings, not re-rating, paid for the move. Nothing in either leasing book explains the first case.
The residual causes are the discount rate and a wholesale repricing of AI risk. More than $2trn of Nasdaq-100 value evaporated in October. Tenant budgets stopped surprising upward: Microsoft cut its fiscal-year capex forecast to $170bn from $175bn and Alphabet's third-quarter spend came in at $51.36bn against $55.09bn expected, even as combined guidance across the four largest hyperscalers reached $720-745bn for 2026. Funding did tighten, but selectively: CoreWeave's debt slid toward distressed prices and several private data center listings were pulled or paused. Over the same 30 sessions, tower landlord American Tower rose 16.6%, which is hard to square with a sector-wide REIT funding squeeze.
On its raised guidance, Digital Realty trades at 21.7x core FFO, below the 22-25x it carried in May when management was guiding FFO growth of 8-9% rather than 13%. Equinix at 26.6x trailing EV/EBITDA remains dear against any property-sector comparison; Digital Realty's 24.4x is not cheap either.
The open question is conversion, and both companies named it themselves: power availability, grid capacity, water, community sentiment and permitting. A $2.5bn backlog is only worth 11.6% once the substation is energized.