

Curtiss-Wright's Nuclear Premium Rested on a Reactor Order That Has Not Been Awarded
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
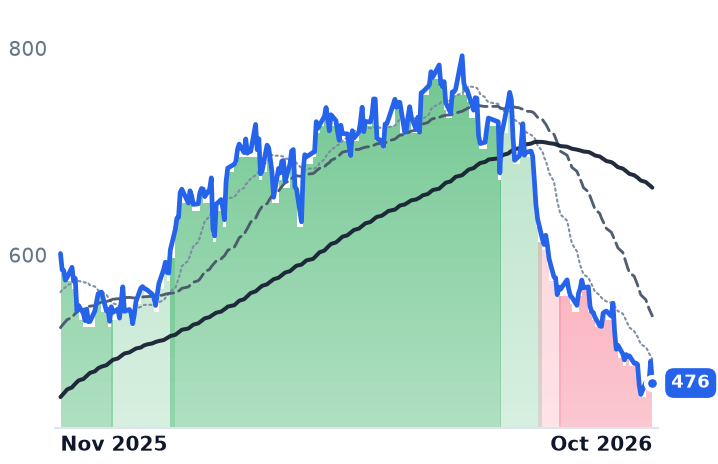
Curtiss-Wright's June quarter improved on every line of its income statement — revenue, margin, orders and a record backlog — and since early September its shares have been marked down alongside nuclear developers that have no revenue at all. The naval work is not the problem: submarine production is funded into the 2030s.
What the premium was priced on was the first production order for Westinghouse's AP1000 reactor, worth about $120m of content per unit, which chief executive Lynn Bamford said she expected in 2026 and which had not been awarded by mid-September. The trailing earnings multiple is 32.6x against 56.5x in May.
BWX Technologies broke first and fell further, but part of its decline is earned: group operating margin compressed to 10.0% while revenue grew 18%.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
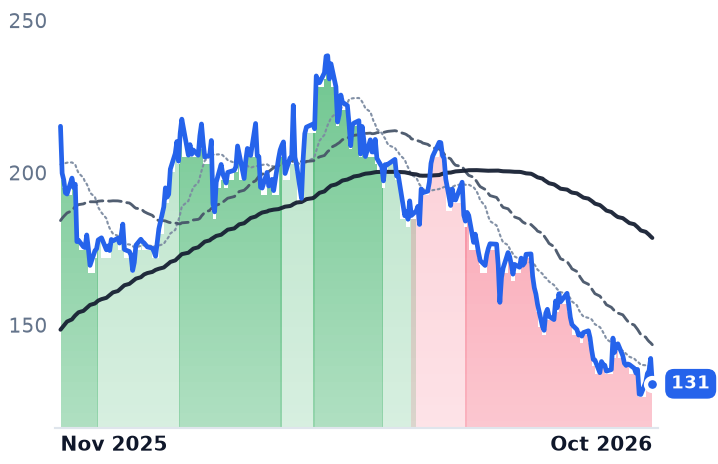
CW | Curtiss-Wright | Aerospace Components & Propulsion | ⚠️ Emerging Bear | −12.8% | −20.8% |
BWXT | BWX Technologies | Aerospace Components & Propulsion | 🔴 Cont. Bear | −3.1% | −39.3% |
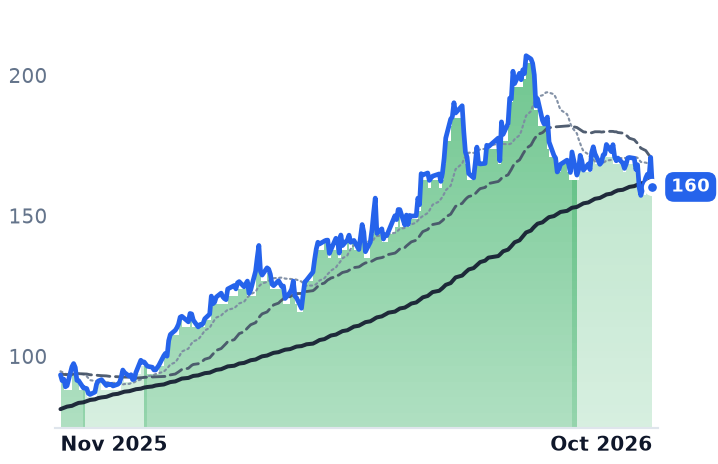
DCO | Ducommun Incorporated | Aerospace Components & Propulsion | 🟢 Cont. Bull | −8.6% | +71.6% |
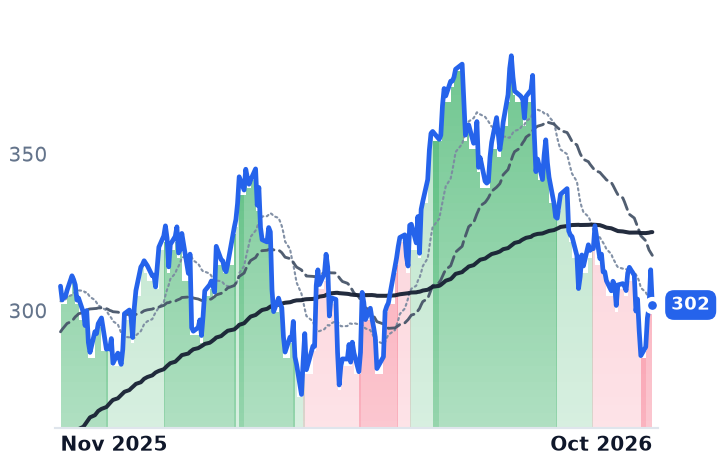
GE | GE Aerospace | Aerospace Components & Propulsion | ⚠️ Emerging Bear | −2.5% | −2.0% |
ATRO | Astronics | Aerospace Components & Propulsion | ⚠️ Emerging Bear | −12.9% | +21.9% |
| Compared against · context, not the story | |||||
SMR | NuScale Power | Advanced Power Systems | 🔴 Cont. Bear | −27.5% | −86.2% |
OKLO | Oklo | Advanced Nuclear | 🔴 Cont. Bear | −29.6% | −80.1% |
NNE | Nano Nuclear Energy | Advanced Power Systems | 🔴 Cont. Bear | −25.4% | −74.2% |
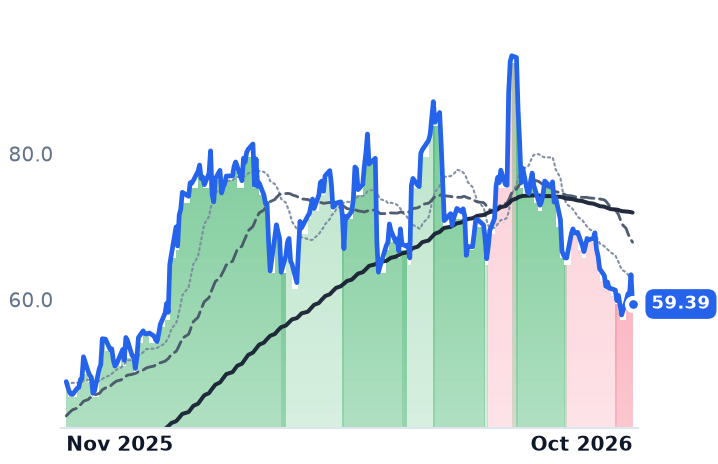
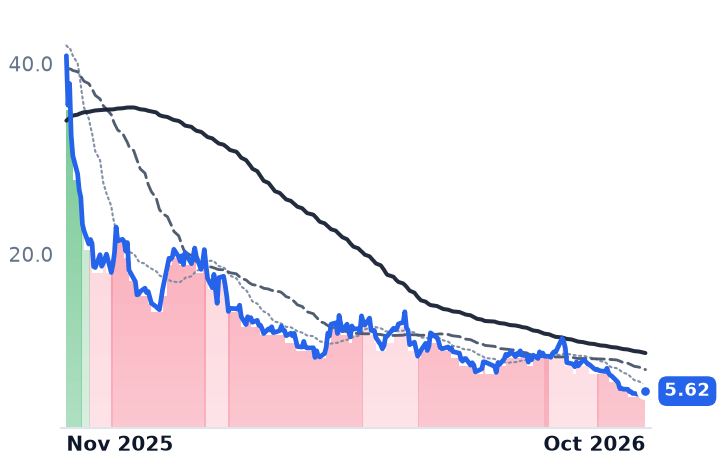
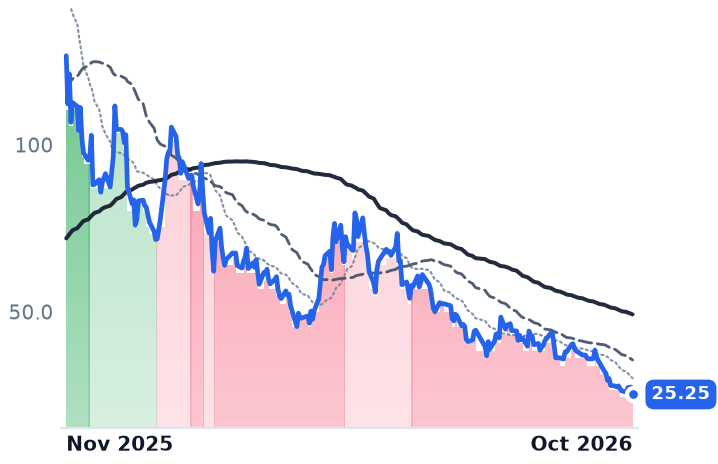
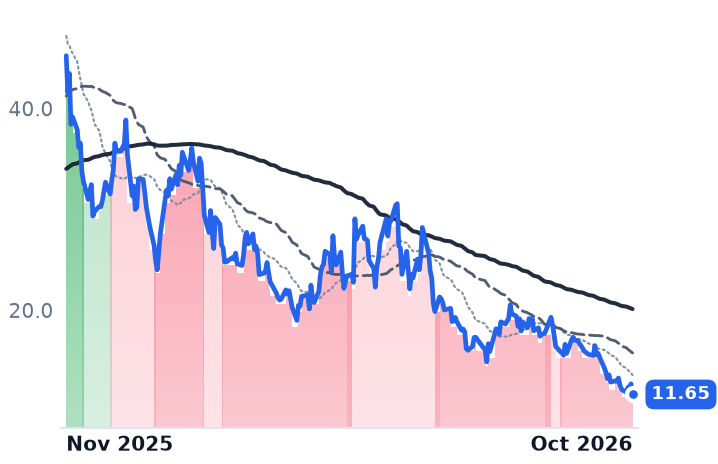
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CW | $17.6B | 32.6x | 31.0x | 4.8x | 4.6x | 12.8x | 12.3x | 21.4x | 3.6% |
BWXT | $12.0B | 33.7x | 27.6x | 3.4x | 3.1x | 15.4x | 14.3x | 24.2x | 2.6% |
DCO | $2.4B | n/m | 36.9x | 2.8x | 2.7x | 10.3x | 10.1x | 462.4x | -1.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GE | $313.1B | 34.7x | 37.0x | 6.0x | 6.2x | 16.9x | 17.5x | 25.2x | 2.6% |
ATRO | $2.1B | 29.1x | 21.9x | 2.3x | 2.1x | 7.0x | 6.4x | 21.3x | 2.9% |
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKLO | $6.6B | n/m | — | — | — | — | — | n/m | -4.2% |
NNE | $1.1B | n/m | — | — | 887.7x | — | — | n/m | -3.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CW | Revenue | +10.4% | +8.2% | +8.2% |
| EPS | +16.9% | +12.2% | +13.2% | |
BWXT | Revenue | +20.7% | +8.9% | +9.7% |
| EPS | +24.1% | +10.5% | +13.9% | |
DCO | Revenue | +6.9% | +9.6% | +9.9% |
| EPS | +18.4% | +23.1% | +18.8% | |
GE | Revenue | +21.6% | +11.7% | +9.3% |
| EPS | +30.7% | +14.1% | +14.4% | |
ATRO | Revenue | +20.3% | +9.8% | −5.4% |
| EPS | +81.9% | +15.3% | −100.0% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
OKLO | Revenue | — | +247.8% | +498.2% |
| EPS | +64.1% | +8.1% | +10.3% | |
NNE | Revenue | +1684.0% | +356.5% | +39.0% |
| EPS | −23.4% | +55.2% | +34.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Curtiss-Wright sells coolant pumps, control-rod drive mechanisms and valves into the US Navy's nuclear fleet and spent-fuel hardware to commercial reactor operators, and in the June quarter its revenue, margins, orders and backlog all moved up together. The shares have since fallen 38% from their June close, a slide that was already running when the company named a successor to its chief executive on 22 September and that steepened on the day long-term Treasury yields hit their highest level since 2002.
The run in the naval-nuclear supply chain was read as a bet on shipped content: submarine reactor parts already contracted, commercial reactor hardware already specified. The marked-down half is the second one. Nothing in Curtiss-Wright's submarine business got worse this year, and the catalyst its valuation leaned on — a first firm order for commercial reactor components — has not arrived.
The submarine side got bigger
Naval & Power sales reached $410m in the June quarter, up 7% on submarine-programme production timing and shipyard aftermarket work, with management guiding the segment to 10–11% sales growth in the September quarter. In the March quarter the same segment earned a 14.9% operating margin, 230 basis points better than a year earlier. Group revenue rose 5.4% to $924.0m, operating margin widened 151 basis points to 19.34% and net income rose 24.9%. Backlog finished the half at a record $4.5bn, up 10% from the end of 2025, with Naval & Power booking 1.5 times what it shipped.
The money behind that is not in doubt either. The Defense Department awarded $76.6bn in July 2026 for nine Virginia- and five Columbia-class submarines, and the Navy's fiscal 2027 request puts $65.8bn into shipbuilding, up 48%.
The order that did not come
Curtiss-Wright carries roughly $120m of content per AP1000 reactor, and the Energy Department has made a conditional $17.5bn loan commitment for up to ten of them. "Long-established and significant commercial nuclear expertise dating back to the industry's inception" was how Bamford described the position on the August earnings call, telling investors launch customers "were overwhelmingly impressed with the quality of our critical manufacturing processes" and that she expected a first production order in 2026. No such award had been identified by mid-September.
The sell side then named the move for what it was. Truist cut the shares to Hold on the view that nuclear's long-term addressable market is "adequately reflected in current valuations and stock prices". On 7 October, the day the ten-year Treasury yield touched 5.286%, Citigroup pulled its target to $622 from $793 and the stock fell 8.0% to $509.10; Stifel went to $518 from $700 before a new 52-week low on 20 October. This is a repricing of distant cash flows, not a demand problem: NuScale and Oklo, which ship nothing, are down 87% and 81% over twelve months.
BWXT's compression is partly its own
BWX Technologies, the sole-source maker of naval reactors and fuel for the Navy's propulsion programme, entered its downtrend on 8 July and has fallen 29% since. Some of that it earned. June-quarter revenue grew 18.0% to $901.6m while operating margin compressed 344 basis points to 9.97%, the fourth consecutive quarter of lower operating income, because Commercial Operations grew 121% at a 12.9% adjusted-EBITDA margin against Government Operations' 20.9%, and the commercial margin guide was cut to about 13% from about 14% to fund capacity.
The order book did the opposite. Backlog reached $8.4bn, up 40%, on 1.7 times trailing book-to-bill, and free-cash-flow guidance went up by $30m to $345m–$360m. BWXT trades at 33.7x trailing earnings against 55.0x in early May, with a forward 27.6x.
Ducommun, which builds contoured fuselage panels, winglets and rotor blades and has no nuclear content, shows what an aerospace-structures business did instead: June-quarter revenue up 11.0% to $224.5m, operating income up 59.4%, the shares up 75% over twelve months.
What the multiple gave back
For Curtiss-Wright, the results account for none of the decline. Earnings rose, margins widened, backlog set a record, and the trailing multiple fell from 56.5x in May to 32.6x. Its forward 31.0x sits only 1.6 turns below trailing against consensus 2026 earnings of $15.36 a share, up 17% — the market has stopped paying for acceleration in a business whose naval revenue is contracted and whose commercial upside is a decade out. BWXT's 27.6x forward against 33.7x trailing still embeds a 24% earnings jump, which is the harder claim of the two, and its mix is working against margins while it funds capacity.
The split has a cause: Curtiss-Wright's nuclear content is already inside expanding segment margins, so only the valuation moved; BWXT's growth is arriving through a lower-margin commercial line it is still building out, so both the valuation and the earnings line moved.
BWXT reports third-quarter results after the close on Monday, with analysts looking for $1.19 a share. It will say a good deal about mix and nothing about the reactor order neither company has yet been given.