

Smithfield Guided Its Branded Meats to Out-Earn the Whole Company This Year
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Smithfield told investors on 27 October that its branded Packaged Meats arm should earn more this fiscal year than Smithfield entire, because the hog farms and slaughter plants that supply it are losing money. Packaged Meats widened its margin to 11.6% on average selling prices down 5.3%; Fresh Pork lost $89m as the processing spread fell 35%.
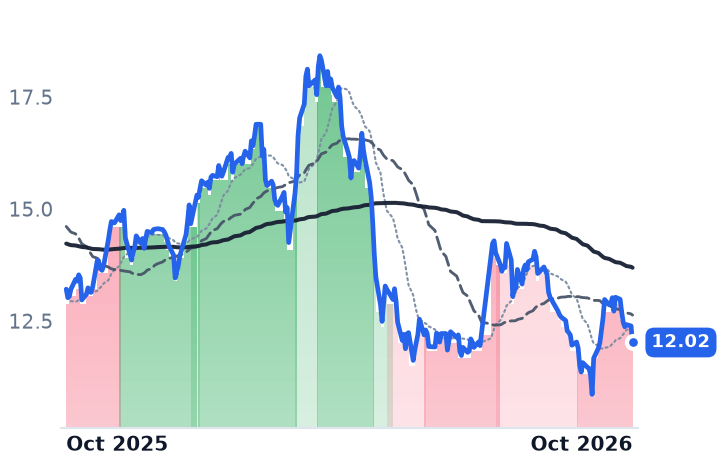
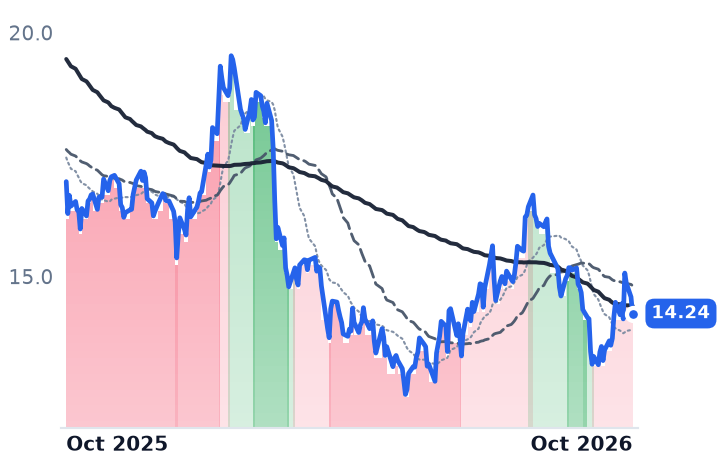
That mechanism splits the shelf the market has been selling as one. Smithfield and Hormel own the brand that captures a cheap pound of meat, and Hormel's adjusted operating margin reached 9.0% as it raised fiscal 2026 earnings guidance. Pilgrim's Pride sells the commodity itself, and with the jumbo cutout down 27% its US margin halved to 8.7%; there the share price has followed the earnings down.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
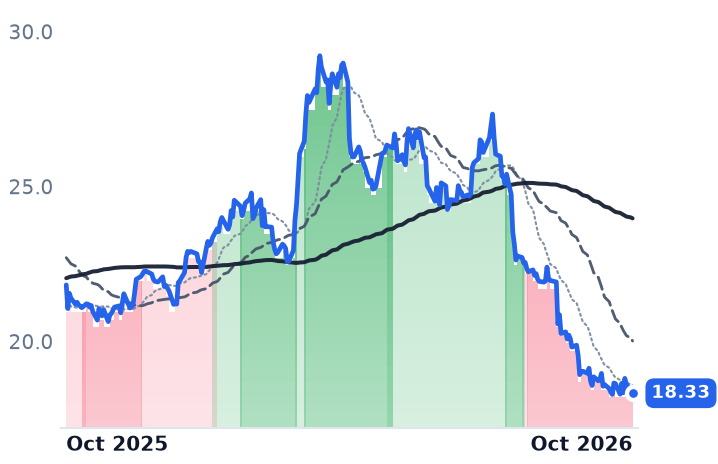
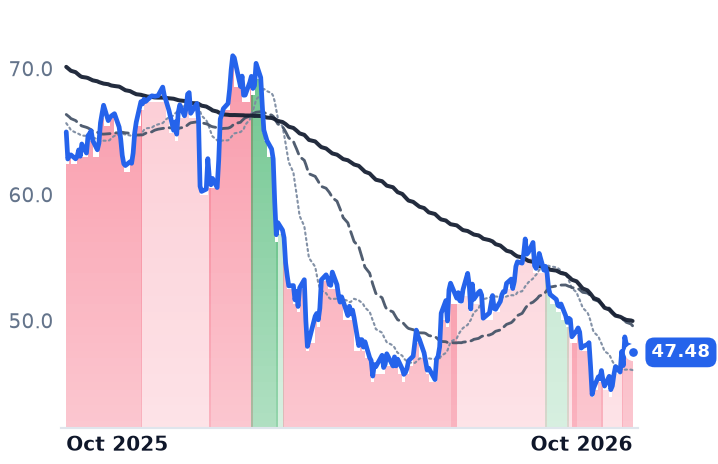
SFD | Smithfield Foods | Meat & Poultry | ⚠️ Emerging Bear | −3.4% | −16.0% |
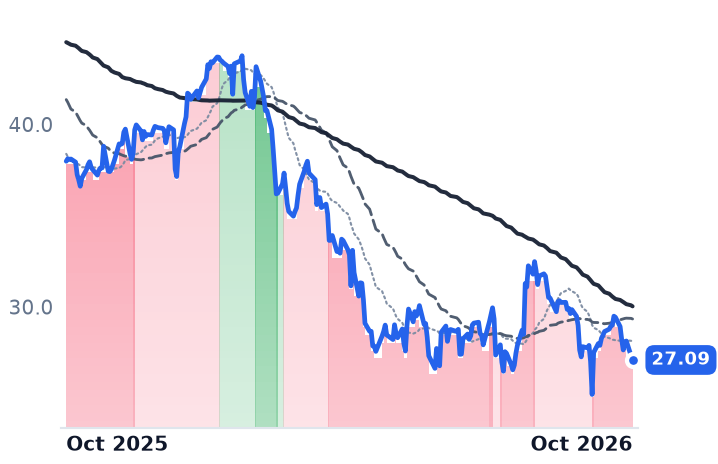
PPC | Pilgrim's Pride | Meat & Poultry | 🔴 Cont. Bear | −2.4% | −28.7% |
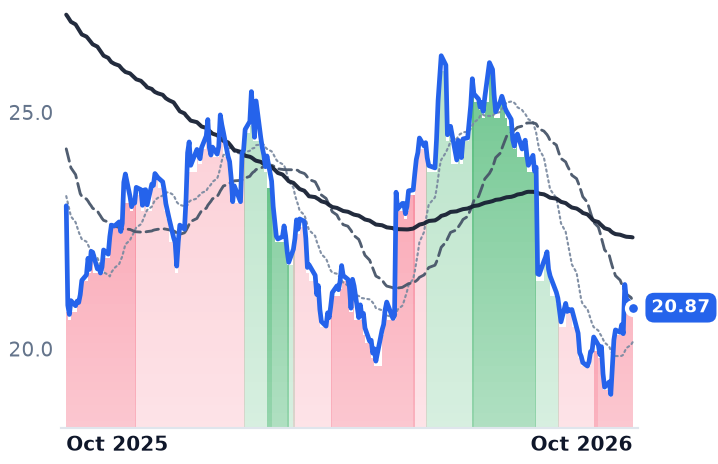
HRL | Hormel Foods | Meat & Poultry | 🔴 Cont. Bear | +6.3% | −9.4% |
JBS | Jbs | Meat & Poultry | 🔴 Cont. Bear | +4.8% | −9.0% |
| Compared against · context, not the story | |||||
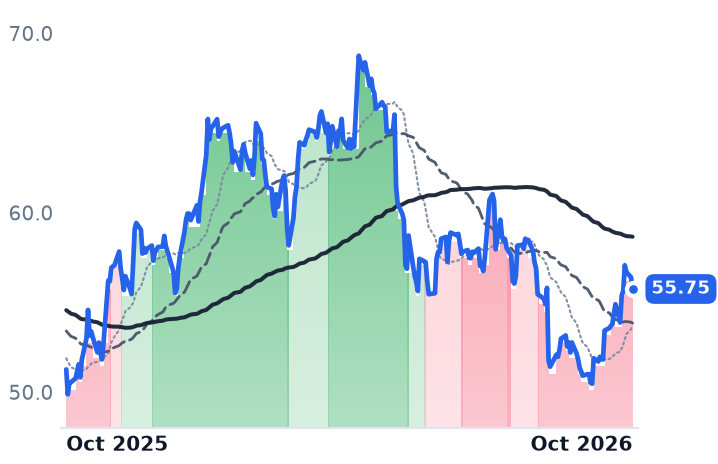
TSN | Tyson Foods | Meat Processing | 🔴 Cont. Bear | +9.3% | +8.7% |
CAG | Conagra Brands | Diversified CPG | 🔴 Cont. Bear | +0.6% | −16.0% |
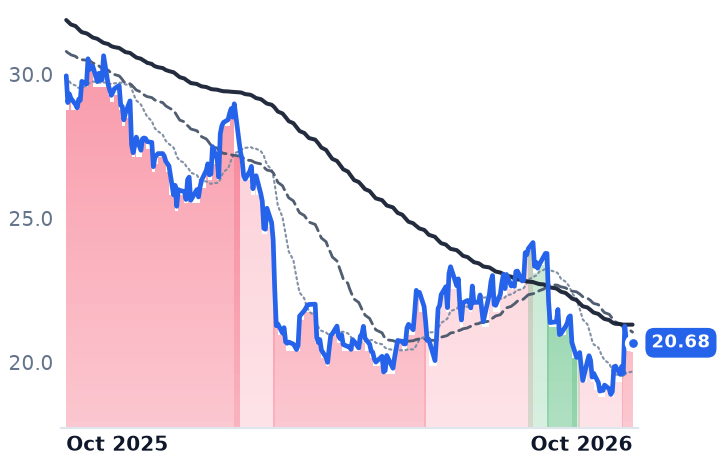
CPB | Campbell Soup | Sauces & Seasonings | 🔴 Cont. Bear | +3.2% | −31.0% |
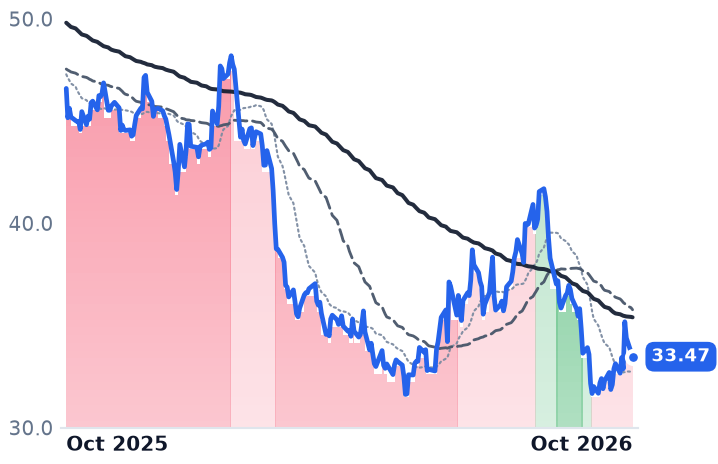
GIS | General Mills | Diversified CPG | 🔴 Cont. Bear | −1.3% | −28.2% |
MKC | McCormick & Company, Incorporated | Sauces & Seasonings | 🔴 Cont. Bear | −1.3% | −26.9% |
KHC | The Kraft Heinz | Diversified CPG | 🌱 Emerging Bull | +1.8% | −2.6% |
SJM | The J. M. Smucker | Diversified CPG | 🟢 Cont. Bull | +4.9% | +25.4% |
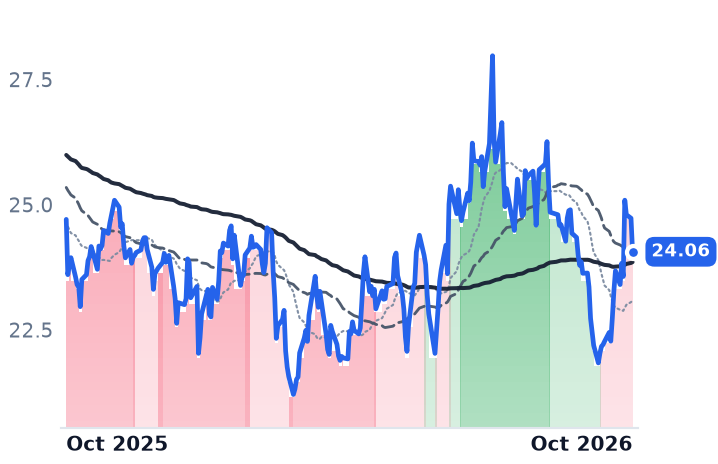
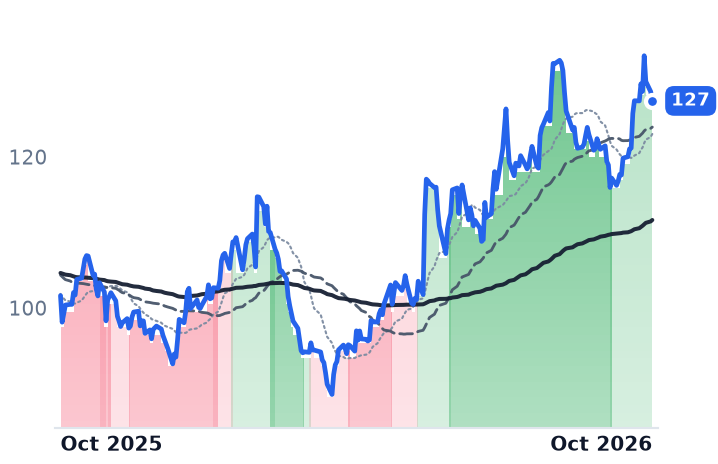
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SFD | $7.2B | 8.0x | 9.3x | 0.5x | 0.5x | 3.9x | 3.8x | 6.3x | 12.8% |
PPC | $6.5B | 11.8x | 11.9x | 0.3x | 0.3x | 3.6x | 3.6x | 6.3x | 4.7% |
HRL | $11.5B | 33.1x | 13.3x | 0.9x | 0.9x | 6.0x | 5.9x | 15.5x | 6.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TSN | $19.6B | 33.4x | 14.1x | 0.4x | 0.4x | 5.7x | 5.8x | 10.3x | 5.9% |
JBS | $26.7B | 17.1x | — | 0.4x | — | 3.1x | — | 5.4x | 1.5% |
CAG | $6.4B | n/m | 9.1x | 0.6x | 0.6x | 2.4x | 2.5x | n/m | 13.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CPB | $5.9B | 14.9x | 11.8x | 0.6x | 0.6x | 2.2x | 2.2x | 10.0x | 11.4% |
GIS | $17.2B | n/m | 10.4x | 0.9x | 1.0x | 2.8x | 2.9x | 9.1x | 9.0% |
MKC | $12.1B | 8.1x | 14.5x | 1.6x | 1.5x | 4.0x | 3.9x | 12.0x | 7.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KHC | $26.9B | n/m | 11.1x | 1.1x | 1.1x | 3.3x | 3.3x | n/m | 14.2% |
SJM | $13.0B | 56.7x | 11.2x | 1.4x | 1.5x | 3.7x | 3.8x | 14.9x | 12.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SFD | Revenue | −0.7% | −1.2% | +2.0% |
| EPS | −17.3% | −0.5% | +12.6% | |
PPC | Revenue | +0.8% | +2.2% | +2.8% |
| EPS | −56.8% | +15.7% | +21.8% | |
HRL | Revenue | −0.1% | +2.9% | +2.3% |
| EPS | +8.8% | +5.7% | +5.4% | |
TSN | Revenue | +2.3% | −1.2% | +1.2% |
| EPS | −12.2% | +18.0% | +24.1% | |
JBS | Revenue | +1.5% | +2.0% | +1.8% |
| EPS | −64.9% | +90.8% | +44.2% | |
CAG | Revenue | −3.2% | −4.1% | −0.4% |
| EPS | −26.7% | −13.9% | +2.5% | |
CPB | Revenue | −4.9% | −2.9% | −0.5% |
| EPS | −26.0% | −21.7% | +6.9% | |
GIS | Revenue | −5.7% | −3.8% | +0.3% |
| EPS | −18.7% | −9.5% | +2.4% | |
MKC | Revenue | +16.2% | +2.7% | +3.5% |
| EPS | +2.5% | +3.9% | +8.6% | |
KHC | Revenue | −1.2% | +0.1% | +1.4% |
| EPS | −18.9% | +0.8% | +2.8% | |
SJM | Revenue | +3.1% | −1.0% | +1.3% |
| EPS | −10.2% | +20.1% | +1.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Smithfield Foods, which raises hogs and sells Smithfield bacon, Nathan's Famous hot dogs and Eckrich deli meat, told investors on 27 October that its branded Packaged Meats segment should earn adjusted operating income of $1,075m–$1,150m this fiscal year. The company as a whole is guided to $900m–$1.0bn. The branded arm is expected to out-earn the business that contains it, because the farms and slaughter plants feeding it are losing money.
Four of the five big US meat and poultry names have been marked down between about 7% and 29% over the past year, Tyson Foods excepted, on a premise that cheap grain and cheap hogs would widen processing spreads. The quarters reported in June and September show something narrower. Inside a vertically integrated protein company the cheap raw material is a transfer, not a windfall, and it settles wherever the brand sits.
Smithfield's margin came out of its own barns
Packaged Meats earned about $230m in the September quarter, with margin widening to 11.6% from 10.8%, on sales down 5.2% to $2bn. Average selling price fell 5.3% and volume rose 0.2%: the segment made more money per pound because hog and pork cost fell faster than the price it charged. Upstream, Fresh Pork swung to a loss of $89m from a $10m profit as the processing spread fell 35% and volume dropped 6.3%, while Hog Production earned $34m against $89m. Group adjusted operating profit fell 55% to $145m.
The share gains downstream rest on distribution and brand. "Across our top 25 categories, industry volume declined 3.3%, while we grew volume by nearly 1%. We were the only company in our core competitive set to grow volume in this quarter, driving 0.4 points increase in volume share," Shane Smith, president and chief executive, told investors on 27 October. Smithfield gained share in all five of its largest categories, led by 2.3 points in smoked ham, and its Nathan's Famous purchase eliminates $33m of annual licence costs on rights previously held only through 2032. A new supply agreement with a joint-venture partner cuts internally produced hogs by roughly 900,000.
The shares closed 27 October at $18.33, a few cents above a 52-week low, at 1.03x book with a 12.8% trailing free-cash-flow yield and net debt at 0.5x EBITDA. The forward earnings multiple of 9.3x sits above 8.0x trailing, so consensus is still falling.
Pilgrim's had nothing downstream to catch it
Pilgrim's Pride, the Greeley, Colorado chicken and pork processor controlled by JBS, is the same geometry with the brand missing. US net revenues slipped to $2.65bn from $2.82bn in the June quarter while US adjusted EBITDA fell to $231.5m from $482.7m, a margin of 8.7% against 17.1%, which the company attributed primarily to a 27% drop in the jumbo cutout value. Consolidated operating margin has run 10.4%, 4.5%, 3.6% and 1.4% over the last four quarters.
Feed, the premise the widening-spread case rested on, moved against the processor. Corn ran roughly $4.25–$4.50 a bushel for the year but averaged $5.18 in the first week of August, and October soybean meal traded at $350–$360 a short ton in mid-September against a first-half range of $275–$325. Corn and soymeal are 60–70% of a broiler's diet.
The company is also adding pounds into the falling cutout: about 2.5% US supply growth in the second half. "What we want is to grow our branded business in the U.S. That will compensate the volatility in the big bird commodity market. Once again, we don't want to reduce our commodity operation," chief executive Fabio Sandri said on the 30 July call. Consensus has fiscal 2026 earnings at $2.27 a share against $5.26 for 2025; at $27.09 the forward multiple of 11.9x is wider than the roughly 8.4x the stock carried last October on $4.54 of delivered earnings.
Hormel divested the turkeys and kept the margin
Hormel Foods, the SPAM, Skippy and Jennie-O owner, is the counter-case. Gross margin moved 15 hundredths of a percentage point in the July quarter, against a 7.7-point loss at Pilgrim's; adjusted operating margin expanded to 9.0% and the company raised fiscal 2026 adjusted earnings guidance to $1.45–$1.51. Roughly half its segment sales decline came from divesting the whole-bird turkey business and exiting private-label snack nuts. "With our strong year-to-date performance and continued opportunities ahead, we are raising and narrowing our adjusted earnings outlook for fiscal 2026," interim chief executive Jeff Ettinger said on 27 August. The shares still fell 19.4% over three months, and at 13.3x forward earnings Hormel is marginally cheaper than Tyson's 14.1x — Tyson being the name whose beef unit is guided to a fiscal 2026 operating loss of $625m–$775m while its chicken segment is guided to $1.85bn–$1.95bn.
Arithmetic at Pilgrim's, an open question at Smithfield
Three companies, one cheap pound of meat, three outcomes decided by who owns the label on the package.
For Pilgrim's the market has done the arithmetic: a 28.5% decline over the year against consensus earnings more than halved, and a forward multiple that widened as the price fell. Smithfield is the awkward one, sitting at a 52-week low on the day it reaffirmed the segment guided to carry all of group profit; management tied the duration of the upstream loss to the fourth-quarter holiday season and spring 2027. Hormel's de-rating tests something else entirely: organic sales growth guided to 1–2%.
Pilgrim's Pride reports its third quarter after today's close, with consensus at 48 cents a share. Smithfield has shown where the money in a cheap pound of meat ends up; nobody can yet price when the cutout stops falling for the company that only sells pounds.