

The 800-Volt Rack Build Arrives in 2027, and Vicor Is Billing Patents in the Meantime
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Two companies built for the shift to 800-volt direct-current rack power fell by about a third in thirty days, and only one of them has revenue to show for the architecture. Vicor's October quarter carried $66.6m of patent royalties inside $197.1m of revenue, a third of the top line set by a licensing calendar rather than by modules shipped.
The royalty line did not substitute for hardware. Product revenue implied by the company's own figures rose roughly 15.5% sequentially, gross margin went from 58.0% to 68.3%, and one-year backlog reached $406m. The problem sits in the next quarter, where guided product growth of about 10% plus a $43m royalty minimum points to a sequential decline.
Navitas is the other side of the same mechanism: $10.53m of quarterly revenue, no gross profit, and an 800-volt ramp its own management dates through late 2027 and early 2028.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
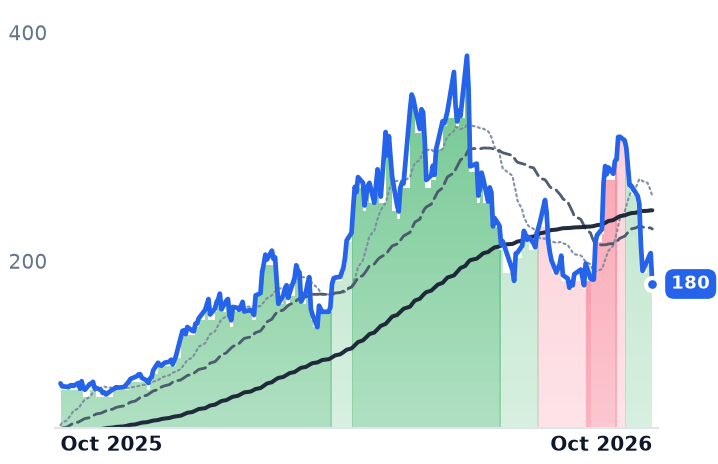
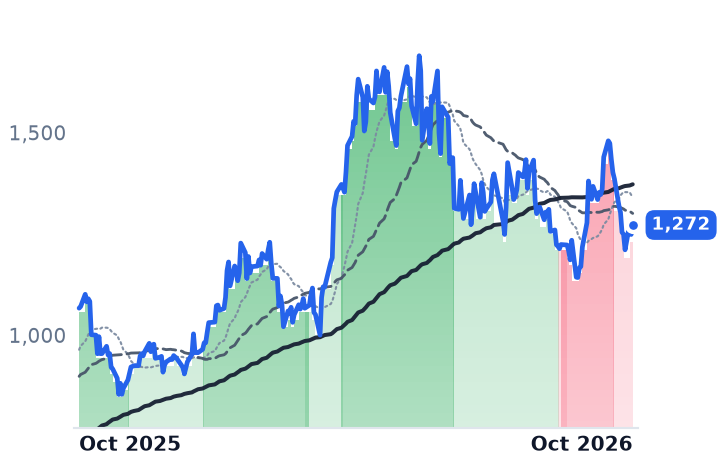
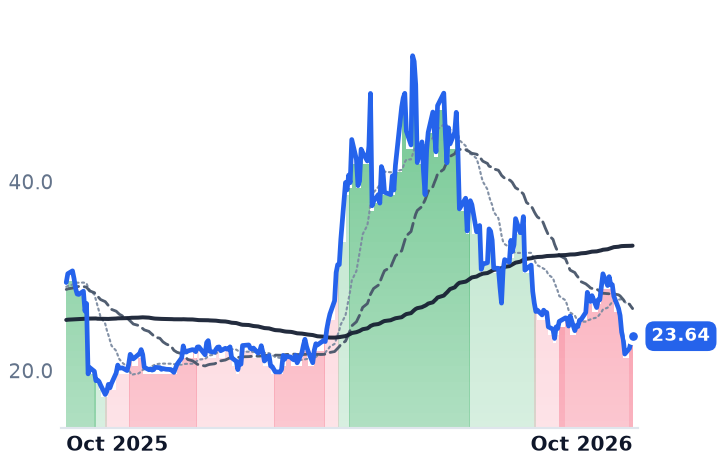
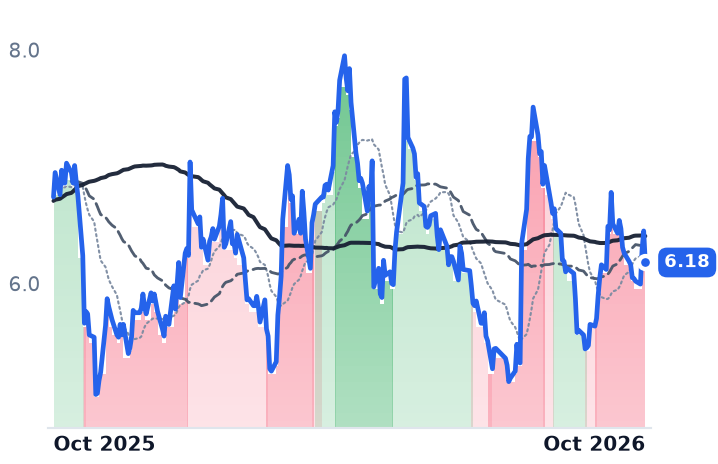
VICR | Vicor | Power Conversion & Control | ⚠️ Emerging Bear | −36.4% | +93.6% |
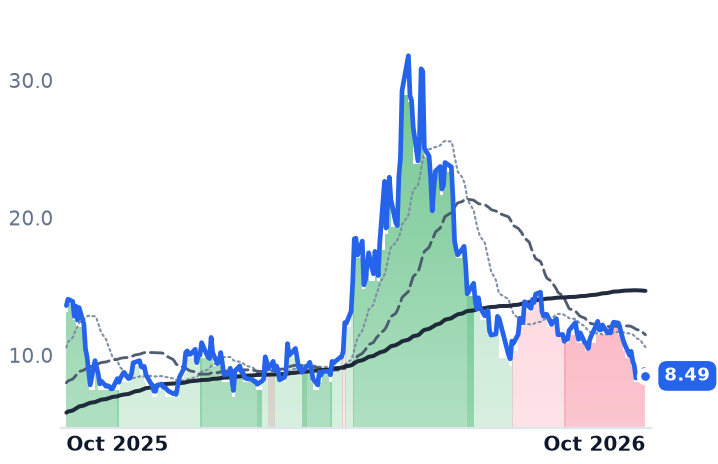
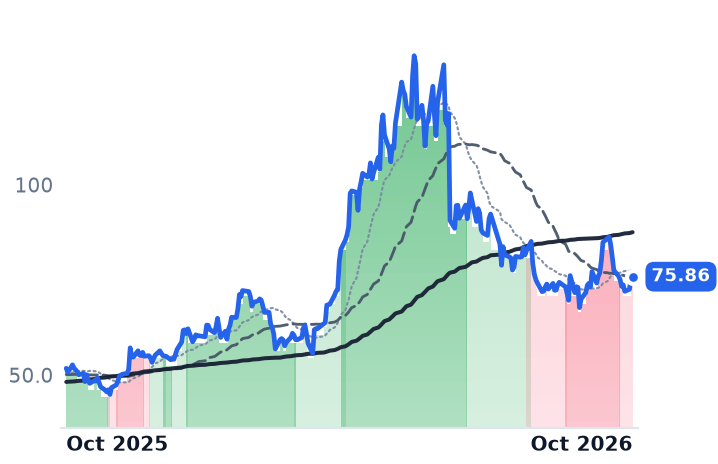
NVTS | Navitas Semiconductor | Analog & Power Management | ⚠️ Emerging Bear | −28.3% | −37.6% |
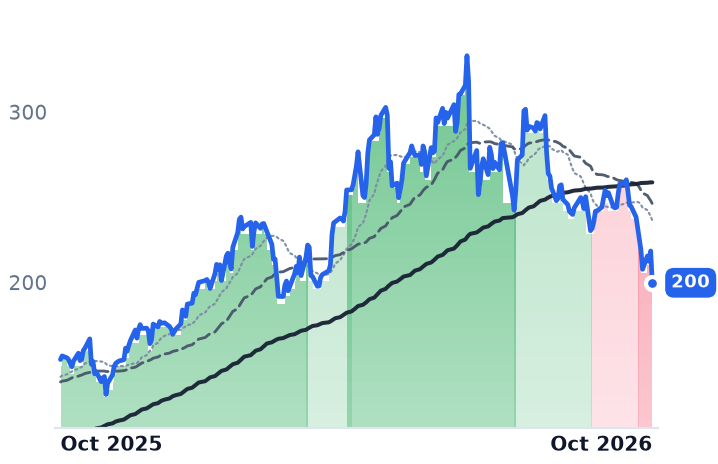
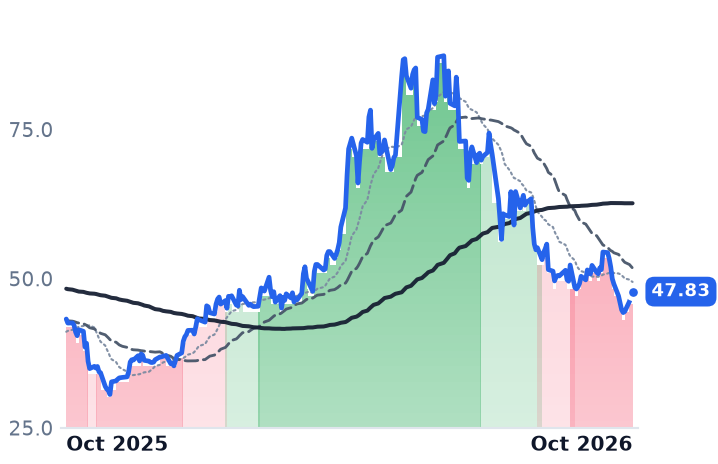
BELFB | Bel Fuse | Power Conversion & Control | ⚠️ Emerging Bear | −21.4% | +29.1% |
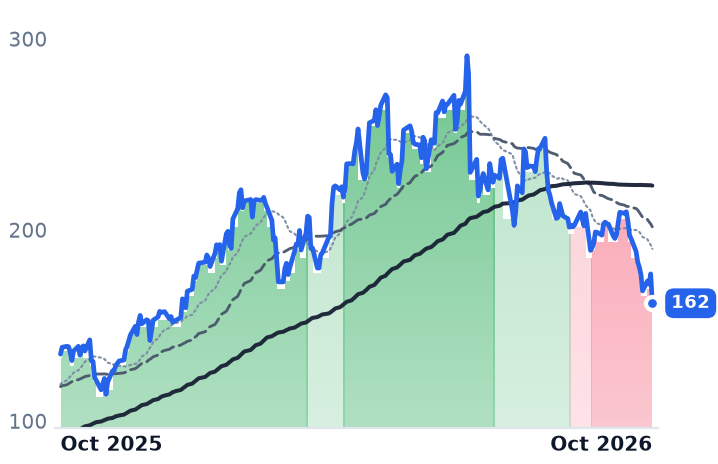
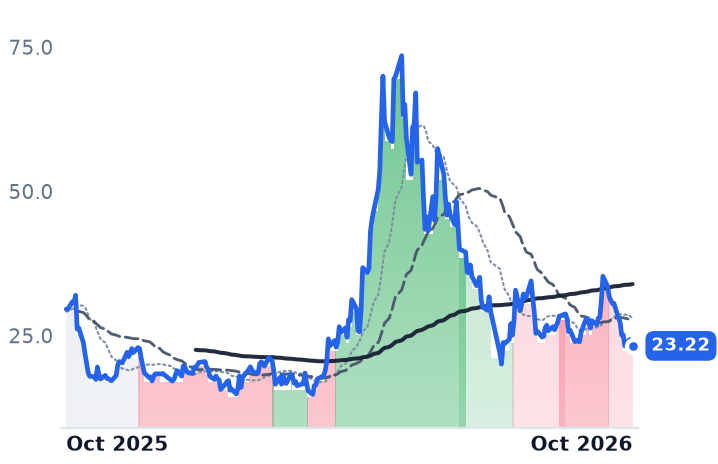
BELFA | Bel Fuse | Hardware, Equipment & Parts | ⚠️ Emerging Bear | −20.8% | +19.7% |
IPWR | Ideal Power | Semiconductors | 🔴 Cont. Bear | −29.8% | −48.7% |
ULBI | Ultralife | Electrical Equipment & Parts | 🔴 Cont. Bear | +4.7% | −8.3% |
| Compared against · context, not the story | |||||
MPWR | Monolithic Power Systems | Analog & Power Management | ⚠️ Emerging Bear | −6.2% | +19.2% |
ON | ON Semiconductor | Analog & Power Management | ⚠️ Emerging Bear | +2.4% | +46.5% |
POWI | Power Integrations | Analog & Power Management | ⚠️ Emerging Bear | −6.3% | +10.6% |
WOLF | Wolfspeed | Analog & Power Management | 🔴 Cont. Bear | −14.4% | −21.5% |
AOSL | Alpha and Omega Semiconductor | Analog & Power Management | ⚠️ Emerging Bear | −14.7% | −19.4% |
VRT | Vertiv | Advanced Power Systems | ⚠️ Emerging Bear | −14.5% | +16.1% |
AEIS | Advanced Energy Industries | Power Conversion & Control | ⚠️ Emerging Bear | −12.3% | +23.7% |
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | −2.5% | +20.7% |
LRCX | Lam Research | Fabrication Equipment & Materials | 🟢 Cont. Bull | −13.4% | +80.9% |
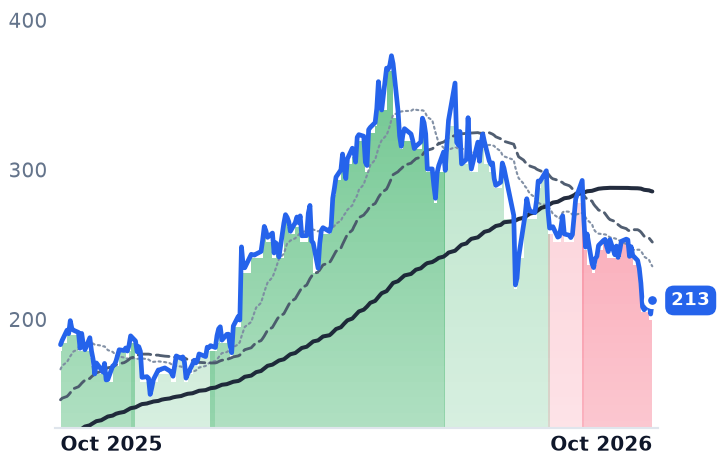
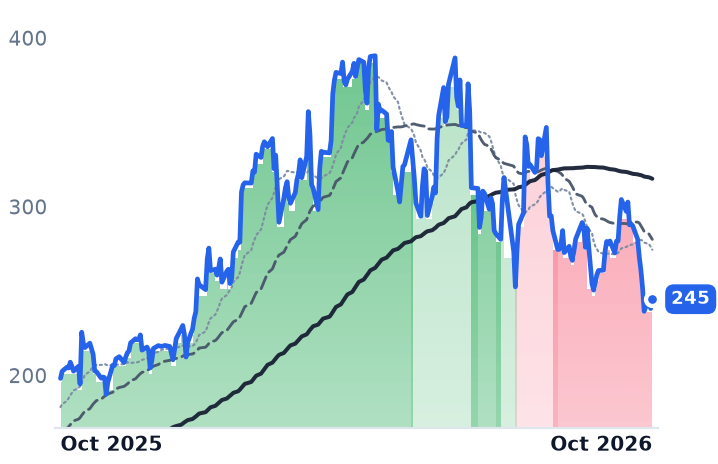
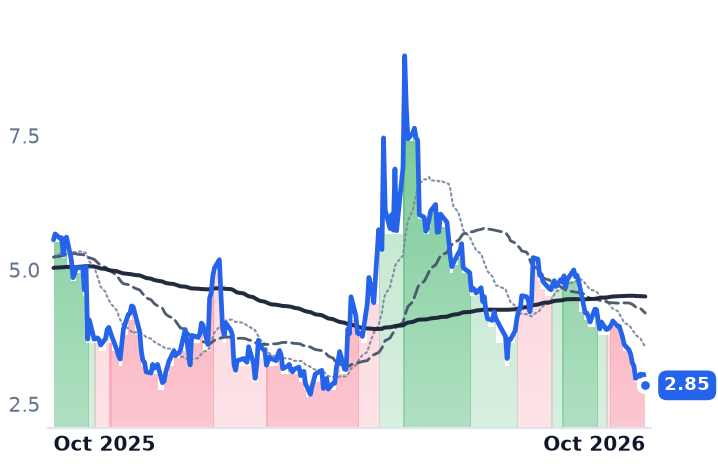
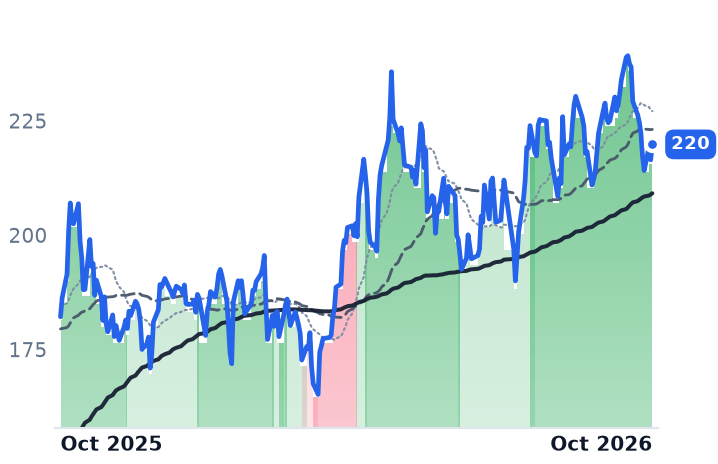
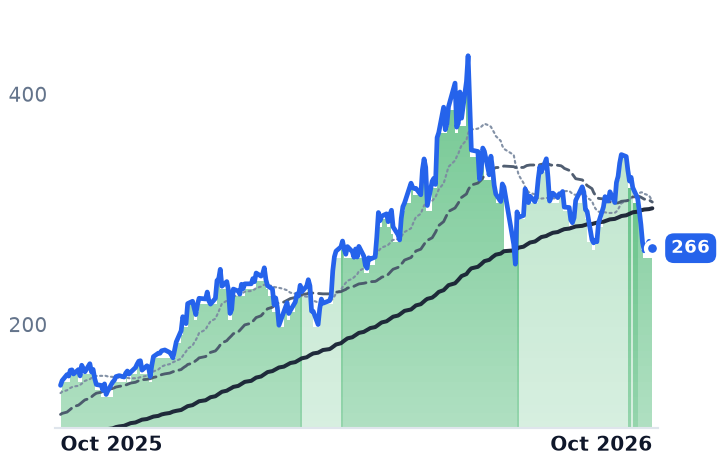
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VICR | $8.3B | 45.8x | 45.9x | 14.8x | 13.1x | 24.4x | 21.6x | 45.0x | 0.6% |
NVTS | $2.2B | n/m | — | 60.7x | 46.5x | — | — | n/m | -3.1% |
BELFB | $2.5B | 50.0x | 20.3x | 3.3x | 3.0x | 8.4x | 7.7x | 16.9x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BELFA | $2.4B | 50.0x | 16.6x | 3.3x | 2.9x | 8.4x | 7.5x | 16.9x | 3.0% |
MPWR | $57.4B | 71.2x | 42.3x | 17.5x | 13.8x | 31.8x | 24.9x | 54.0x | 1.0% |
ON | $33.0B | 53.7x | 26.5x | 5.3x | 5.0x | 14.2x | 13.5x | 26.9x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWI | $3.5B | 136.5x | 44.7x | 7.7x | 7.2x | 14.4x | 13.5x | 84.1x | 2.3% |
WOLF | $1.8B | n/m | — | 2.8x | 2.9x | — | — | n/m | -19.3% |
AOSL | $929.9M | n/m | — | 1.4x | 1.3x | 6.1x | 5.9x | n/m | -1.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
AEIS | $11.4B | 49.5x | 25.4x | 5.6x | 4.7x | 14.1x | 11.9x | 37.7x | 0.8% |
IPWR | $46.8M | n/m | — | — | 58.5x | — | — | n/m | -20.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ULBI | $103.0M | n/m | 7.2x | 0.5x | 0.5x | 2.3x | 1.9x | n/m | 2.0% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
LRCX | $430.0B | 59.4x | 36.7x | 18.5x | 12.4x | 36.7x | 24.6x | 49.2x | 1.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VICR | Revenue | +39.8% | +48.5% | +25.7% |
| EPS | +81.2% | +59.8% | +35.2% | |
NVTS | Revenue | +4.7% | +52.5% | +59.8% |
| EPS | −21.9% | −17.9% | −44.8% | |
BELFB | Revenue | +20.7% | +8.5% | +13.8% |
| EPS | +45.9% | +13.7% | +22.9% | |
BELFA | Revenue | +20.5% | +8.2% | +14.3% |
| EPS | +44.5% | +13.1% | +24.1% | |
MPWR | Revenue | +50.0% | +29.8% | +19.2% |
| EPS | +56.1% | +32.4% | +18.8% | |
ON | Revenue | +9.2% | +13.1% | +13.9% |
| EPS | +37.1% | +40.9% | +30.2% | |
POWI | Revenue | +7.7% | +14.2% | +20.8% |
| EPS | +14.8% | +34.8% | +43.0% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
AOSL | Revenue | −1.9% | +4.4% | +18.5% |
| EPS | −479.7% | −9.8% | −332.6% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
AEIS | Revenue | +36.0% | +24.1% | +17.2% |
| EPS | +79.8% | +35.1% | +22.0% | |
IPWR | Revenue | +1500.0% | +0.0% | +975.0% |
| EPS | −31.5% | −18.8% | −20.3% | |
ULBI | Revenue | +6.2% | — | — |
| EPS | +22.9% | — | — | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
LRCX | Revenue | +27.0% | +49.0% | +18.6% |
| EPS | +41.9% | +64.7% | +25.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vicor's October quarter answered a question the design-win announcements could not: how much of the 800-volt data-center power transition is billable today. The Andover, Massachusetts maker of modular DC-DC converters and custom power systems reported $197.1m of revenue for its third quarter, and $66.6m of that was royalties on a patent it is asserting against twenty respondents at the US International Trade Commission.
The belief the shares carried into October was that the architecture pays its component suppliers now. NVIDIA's own schedule puts the content later: the 800-volt rack is an optional configuration for Vera Rubin, with broader adoption expected at Rubin Ultra in the second half of 2027, the generation whose Kyber racks draw 600kW. Vicor and Navitas Semiconductor, the two specialists built for that conversion chain, each lost about a third of their market value over the thirty days to 22 October. Each has found a different way to cross the gap to 2027, and only one of them is being paid to wait.
The docket became a revenue line
On 9 October the trade commission instituted an investigation of vertical power delivery modules and computing systems on Vicor's complaint over US Patent No. 10,903,734, naming Delta Electronics, Infineon Technologies, Monolithic Power Systems, Flex, Celestica, Quanta and Hon Hai among the respondents, and seeking exclusion and cease-and-desist orders. The accused products are the systems that power AI accelerators, graphics processors and tensor processing units, which means importers of unlicensed designs need a license from Vicor. Vicor's royalty rates escalate across stages tied to how far that investigation has progressed; it has signed a first vertical-power-delivery license with a leading AI original-equipment manufacturer at stage-two rates, and that customer placed a further significant order at the start of the fourth quarter.
Royalties of $66.6m were up from $30.4m in the prior quarter. Strip them out of both periods and the implied product revenue still rose, from about $113.0m to about $130.5m, a derived increase of roughly 15.5%. Advanced Products reached $139m, up 47.5% sequentially and 70.4% of the total. One-year backlog was $406m at quarter-end, up 7% sequentially with book-to-bill above 1, and gross margin expanded from 58.0% to 68.3%. Licensing added to hardware growth here; it did not replace it.
"So as of yesterday, the backlog is actually closer to $400 million," Patrizio Vinciarelli, Vicor's chief executive, told investors on the 20 October call, marking the figure down slightly from the quarter-end number. The mechanism he described is physical. "Every generation of AI processor is stepping up its current requirements...it is now at the thousand amp level and on its way to thousands of amps," Vinciarelli said on the same call. Vicor's capacity to answer that is dated: equipment deployment at its second fab begins in the second quarter of 2027, funded from $513m of cash without a raise.
The fourth quarter steps down
Guidance is where the composition bites. Product revenue is guided to roughly 10% sequential growth and royalties to a minimum of $43m, which works out to about $186m in total, some 5% below the third quarter. The quarter that beat consensus on both lines, $1.33 against $1.29 of expected earnings per share and $197.1m against $183.7m, is not the quarter being annualized.
The shares rose 7.1% on the print to $204.14. The 13.1% break came two sessions later, on a day the whole AI-power complex fell on data-center financing-cost concerns, with GE Vernova and Bloom Energy each off more than 11% and Vertiv down 8.7%, after Lam Research's chief financial officer Doug Bettinger said supply-chain constraints had held back the December-quarter guide. Over the same thirty days onsemi rose 3.1% and Monolithic Power fell 7.9%, so the de-rating concentrated in the names whose content is dated furthest out.
Navitas has the roadmap and no gross profit
Navitas, a 190-person designer of gallium-nitride and silicon-carbide power devices, is the same timing problem without the licensing bridge. Second-quarter revenue was $10.53m, down 27.3% year on year as it exits mobile and consumer chargers, with negative gross profit in each of the first two quarters of 2026. It guided the third quarter to $13.5m, plus or minus $0.5m, on more than 50% year-on-year growth in high-power markets, and expects AI data centers plus grid and energy infrastructure to exceed one-third of sales by the end of 2026, implying roughly $4m to $5m a quarter. Management describes the 800-volt shift as three staged inflections running from the second half of 2026 through "late 2027 and early 2028". It closed the $232.8m acquisition of Claros on 6 October to reach the final conversion stage inside the processor, and at October's GTC Berlin conference Infineon announced its own gallium-nitride collaboration with NVIDIA for 800-volt racks covering the same 800-volt-to-6-volt sockets.
How much of the fall the numbers explain
For Navitas, most of it. The company trades at 46.5x forward revenue with no gross profit to value, and consensus puts fiscal 2026 revenue at $47.69m, only 4.7% above 2025, with the step up to $72.71m deferred to 2027. The calendar in the de-rating is the company's own.
For Vicor, little of it. The quarter beat, the backlog grew, the margin expanded, and the fall arrived two days later with the sector. What the results do not settle is the quality of a third of the revenue: a royalty stream whose rate rises with the progress of a trade case, against a fourth-quarter total the company itself guides lower. At 45.9x consensus 2026 earnings and 28.7x 2027, the shares have come down from roughly 68x forward in May, when they traded between $273 and $304.
The difference between the two is not the roadmap, which they share, but what each can charge before it arrives. Vicor can bill a patent portfolio at 68% gross margin while its fab waits for 2027 equipment. Navitas reports third-quarter results on 3 November, and has to sell parts.