

The 15% Technology Spending Boom Gartner Forecast for 2027 Pays Consultants Just 4.9%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Enterprise consulting shares have risen about a fifth in a month on the premise that the 2026 fear — artificial intelligence eating billable hours — was wrong. Only one of the three big integrators has published numbers that turned.
Accenture's fourth-quarter new bookings reached $22.17bn, a book-to-bill of 1.2, with managed services at a record $12.8bn, and it guided fiscal 2027 to 3–6% growth in local currency. Infosys moved the other way, cutting its full-year constant-currency guide to 1–2% on 23 October. Cognizant has disclosed nothing since July; its June-quarter bookings were down 6% year on year.
The per-head economics underneath all three improved by roughly 1–2% — stabilization below wage inflation. The research forecast credited for the rally puts information-technology services growth at 4.9%, inside what Accenture had already told investors.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
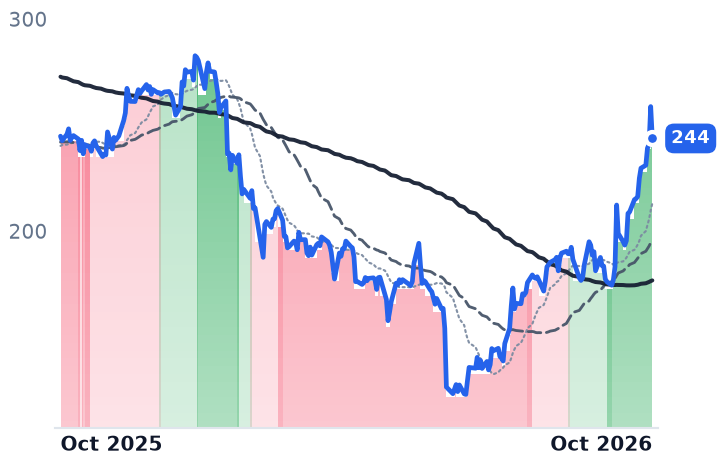
ACN | Accenture | Consulting & Professional Services | 🌱 Emerging Bull | +32.8% | −0.4% |
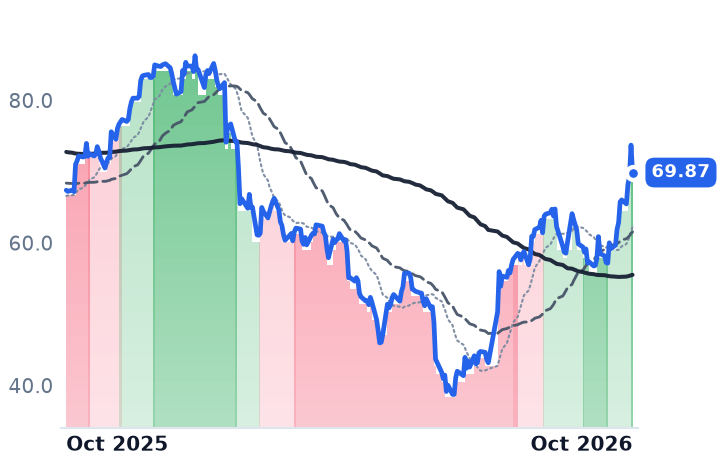
CTSH | Cognizant Technology Solutions | Consulting & Professional Services | 🌱 Emerging Bull | +18.1% | +3.7% |
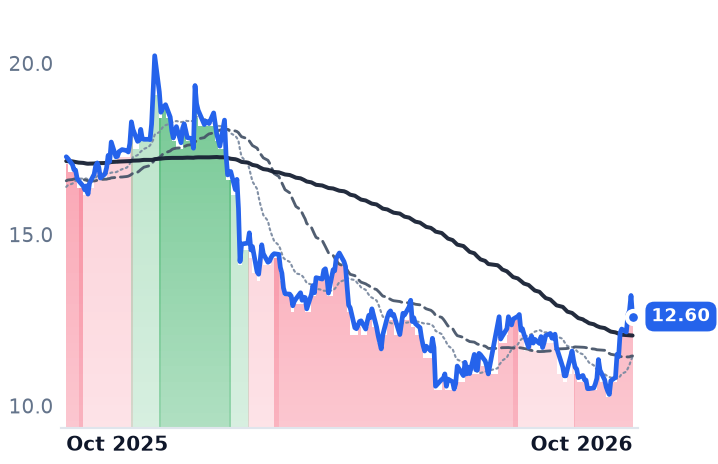
INFY | Infosys | Consulting & Professional Services | 🔴 Cont. Bear | +17.3% | −27.0% |
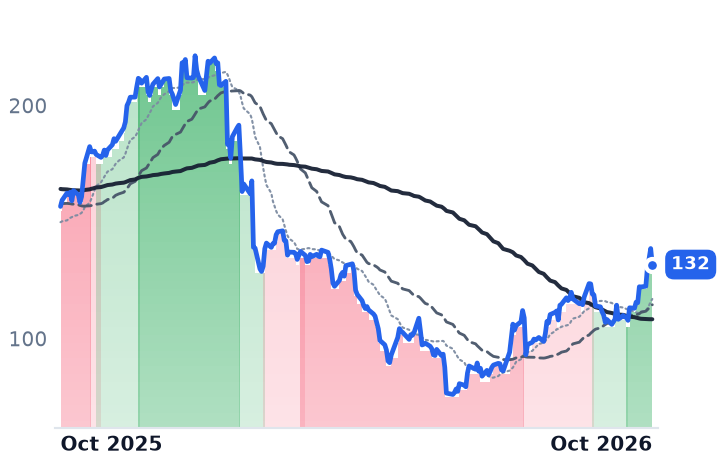
EPAM | EPAM Systems | Consulting & Professional Services | 🌱 Emerging Bull | +19.7% | −15.9% |
GLOB | Globant | Consulting & Professional Services | 🔴 Cont. Bear | +29.9% | −25.3% |
GDYN | Grid Dynamics | Consulting & Professional Services | 🌱 Emerging Bull | +7.7% | +4.2% |
WIT | Wipro | Consulting & Professional Services | 🔴 Cont. Bear | +24.0% | −22.7% |
| Compared against · context, not the story | |||||
DXC | DXC Technology | IT Infrastructure & Services | 🌱 Emerging Bull | +47.8% | +20.3% |
IBM | International Business Machines | Consulting & Professional Services | 🔴 Cont. Bear | +8.3% | −9.9% |
IT | Gartner | Research & Analytics Services | 🌱 Emerging Bull | +31.3% | −6.6% |
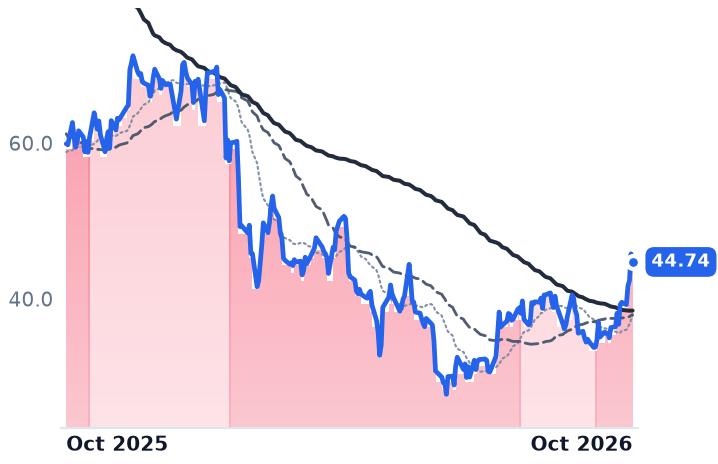
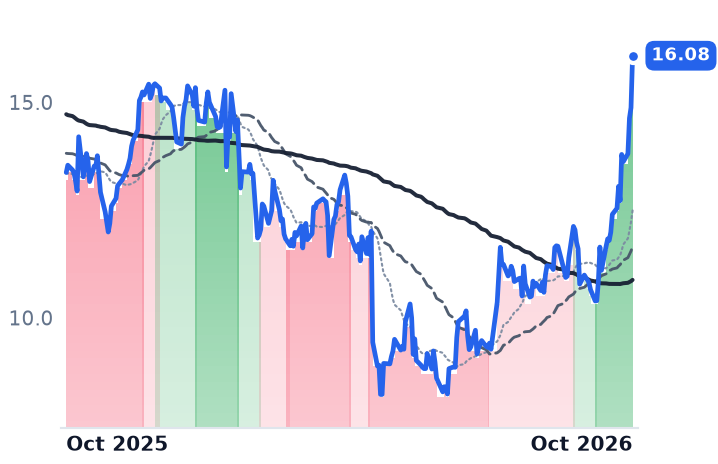
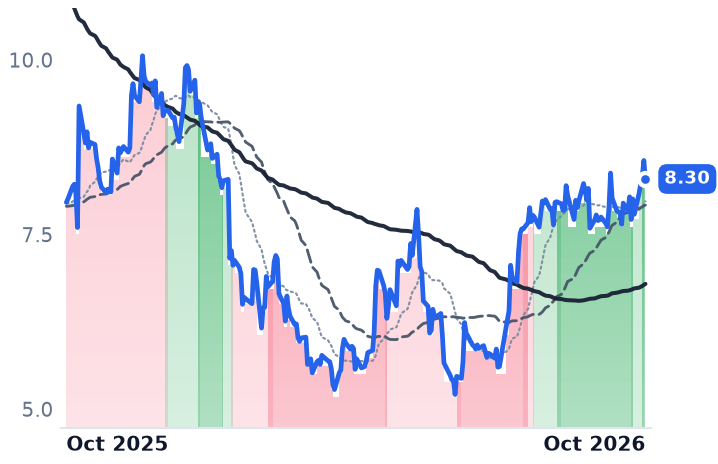
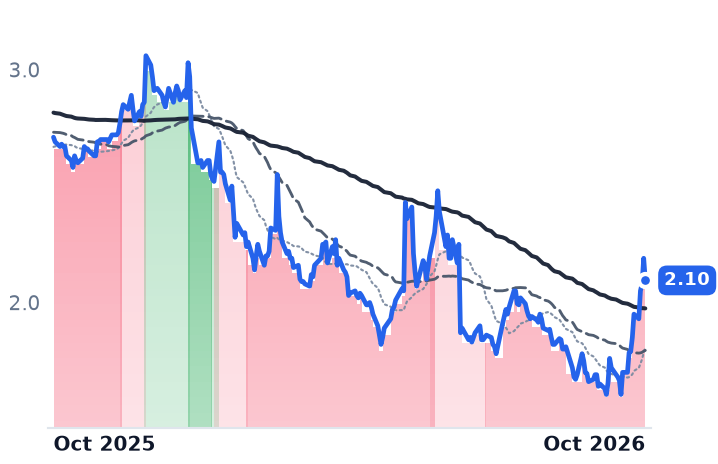
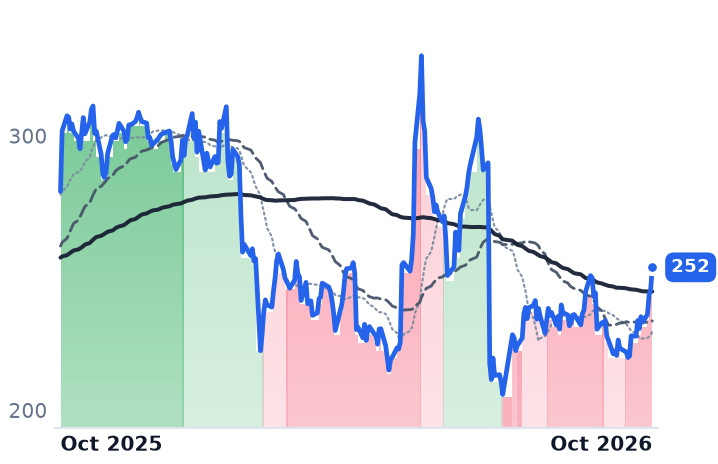
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACN | $149.0B | 17.8x | 16.6x | 2.0x | 1.9x | 6.3x | 6.0x | 11.3x | 7.8% |
CTSH | $31.5B | 15.0x | 12.1x | 1.5x | 1.4x | 4.5x | 4.4x | 7.9x | 8.2% |
INFY | $51.2B | 15.6x | 15.8x | 2.5x | 2.5x | 8.3x | 8.3x | 10.5x | 7.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EPAM | $6.8B | 17.8x | 10.0x | 1.2x | 1.2x | 4.3x | 4.2x | 8.7x | 7.1% |
GLOB | $1.9B | 17.3x | 7.6x | 0.8x | 0.8x | 2.4x | 2.4x | 7.5x | 16.5% |
DXC | $1.8B | 14.2x | 4.2x | 0.1x | 0.1x | 1.0x | 1.1x | 2.6x | 71.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GDYN | $672.5M | 301.5x | 17.8x | 1.6x | 1.5x | 4.6x | 4.4x | 16.3x | 2.4% |
WIT | $20.7B | 14.9x | — | 1.9x | — | 6.7x | — | 9.7x | 8.8% |
IBM | $222.5B | 20.6x | 19.2x | 3.2x | 3.2x | 5.5x | 5.4x | 17.3x | 6.6% |
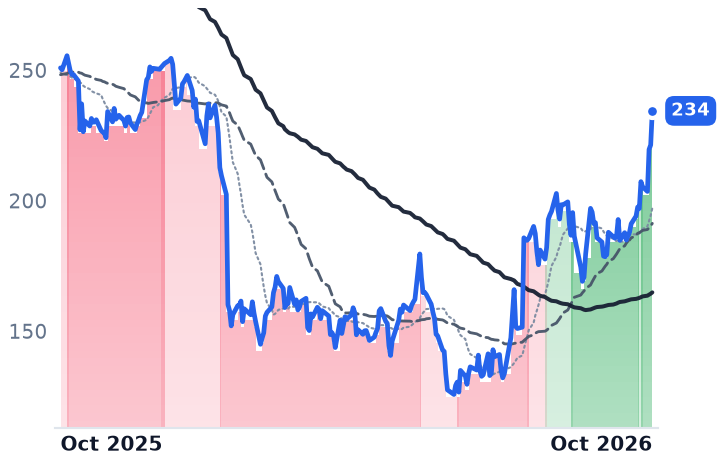
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IT | $12.4B | 17.5x | 13.5x | 1.9x | 1.9x | 2.8x | 2.8x | 10.6x | 10.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ACN | Revenue | +6.0% | +5.3% | +5.1% |
| EPS | +7.6% | +5.9% | +8.6% | |
CTSH | Revenue | +5.2% | +4.7% | +5.1% |
| EPS | +11.0% | +9.9% | +10.2% | |
INFY | Revenue | +1.6% | +4.5% | +3.4% |
| EPS | +2.3% | +4.7% | +4.2% | |
EPAM | Revenue | +3.9% | +3.4% | +4.7% |
| EPS | +15.1% | +6.9% | +7.1% | |
GLOB | Revenue | −0.2% | +2.0% | +3.3% |
| EPS | −3.0% | +4.1% | +3.9% | |
DXC | Revenue | −1.2% | −4.1% | −1.4% |
| EPS | −5.6% | −18.4% | +14.1% | |
GDYN | Revenue | +6.4% | +8.7% | +10.5% |
| EPS | +17.8% | +12.8% | +7.3% | |
WIT | Revenue | +5.4% | +7.4% | +2.7% |
| EPS | +4.6% | +4.8% | +3.4% | |
IBM | Revenue | +5.0% | +3.9% | +5.1% |
| EPS | +8.4% | +6.8% | +8.6% | |
IT | Revenue | −1.2% | +4.2% | +5.1% |
| EPS | +13.2% | +13.8% | +14.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Gartner's new global technology budget forecast lifted the consulting and systems-integration shelf twice in a week, and the number that moved the shares is not the number that pays these companies. Worldwide information-technology spending is forecast to grow 15% in 2027 to $7.35 trillion, published 21 October. Inside it, the services line grows 4.9%, to $1,633bn. The headline rate belongs to data-centre systems, up 55.5%, and software, up 14.6%, on memory-driven hardware inflation that Gartner expects to persist through next year.
The month has been read as proof that the AI de-rating of 2026 was a mistake, and that discretionary consulting budgets are coming back. What the disclosures show is narrower: one of the three large integrators published numbers that turned, the other two did not, and a dollar added to a hardware budget by memory prices buys no billable hour.
Accenture is the one that earned it
Accenture, which sells strategy, consulting and multi-year managed services to large enterprises and governments, reported fourth-quarter new bookings of $22.17bn, up 5% in local currency, a book-to-bill of 1.2 — after a 2% bookings decline and a 1.0 ratio the prior quarter. The composition matters more than the total: managed-services signings hit a record $12.8bn at a 1.4 book-to-bill, while consulting signings of $9.40bn came in at exactly 1.0. The order book was filled by long-duration outsourcing.
It guided fiscal 2027 to 3–6% revenue growth in local currency, with 2 to 2.5 points of that from acquisitions, above estimates. The shares rose 15.9% on 1 October.
"We continue to believe the opportunities related to AI are greater than the impact of AI-related efficiencies in our business," chair and chief executive Julie Sweet told investors on the fiscal fourth-quarter call that day.
The pricing disclosure is less generous. Accenture ended the year with 814,391 staff on 5% headcount growth against 6.5% revenue growth, which works out to roughly $91,100 of revenue per employee, up about 1.4%. On the same call the company said revenue per person would rise again in fiscal 2027 but "at a lower rate in part due to AI", and that in the fourth quarter it "saw lower pricing in many areas of our business." At about 18.0x trailing earnings the stock is cheaper than at four of its last five fiscal year-ends, but 28% above where it closed fiscal 2026 seven weeks earlier, and the step to 16.6x forward implies only the 3–6% earnings growth guided.
Infosys guided the other way on the day the shelf fell
Infosys, India's second-largest information-technology services firm, cut its fiscal-2027 constant-currency growth guidance to 1–2% from 1.5–3% on 23 October, the second downgrade of the year, holding its 20–22% operating-margin range. Order intake went the opposite way: large-deal signings of $5.2bn against $3.6bn in the June quarter, 62% net-new, including one mega-deal above $2bn. Its AI-related revenue grew 29% in the same quarter the forecast came down. Headcount of 332,542 at the end of September is 551 higher than a year earlier, so per-employee revenue of roughly $61,890 is up about 1.2% — won back from attrition, not from price. Infosys is the only one of the three whose forward price-to-earnings of 15.8x sits above its trailing 15.6x: dollar earnings are expected to go slightly backwards, which is what 1–2% constant-currency growth produces.
Cognizant's move came with no numbers at all
Cognizant, the Teaneck-based outsourcer with a largely offshore delivery base, has published nothing since 29 July. Its last print showed trailing-twelve-month bookings up 5% to $29.1bn while bookings signed in the June quarter alone fell 6%, and headcount down 900 in the quarter to 356,700. Annualizing June-quarter revenue over that staff gives roughly $61,500 per employee against $60,030 for 2025 — the best per-head gain of the three, about 2.4%, on a workforce that shrank. The shares rose 19% over thirty days anyway. Barron's, reviewing the week to 16 October, found nearly half the gain came on a single session as money rotated into services while AI and chip stocks sold off, and concluded it "shows up in the multiple." At 15.0x trailing the stock is still below the 18.2x it carried at the end of 2025.
What the month accounts for
Accenture's own bookings, margin and guidance account for Accenture's re-rating. Nothing in the other two companies' filings accounts for theirs, and the research forecast credited for the second leg sits inside Accenture's guide and above Infosys's. The per-head price of the work improved by one to two and a half percent across all three — stabilization, and still below wage inflation, with Accenture's roughly $91,100 seat billing about 1.5 times the offshore seat at the other two. The likelier reading of the rest is rotation into cheap services names rather than a return of discretionary budgets, and the whole shelf fell between 2.3% and 5.8% in the single session of 23 October, with only Infosys reporting.
Meanwhile the bidders for the implementation work have changed. OpenAI launched a deployment company with more than $4bn of initial investment to embed AI engineers inside client organizations, after Anthropic raised $1.5bn for a rival enterprise services business; on 23 October Anthropic was reported to be preparing a European consultancy with Hg, with hubs in London and Berlin.
Cognizant reports on 29 October. It will be the first company in this group to add new information since the rally began, and the only question its own June numbers leave open is whether a quarter of bookings decline was one quarter.