

Texas Instruments Said Analog Prices Turned Up; the Selloff Hit AI Small Caps Instead
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The analog and mixed-signal shelf has been sold this month as though the 2026 restocking cycle were ending. The companies whose order books define that cycle are not the ones falling.
Texas Instruments reported on 20 October that analog revenue rose 32% year on year and that analog pricing turned up in the second half after a flat first half. Microchip's distributor inventory sits at 25 days and is being called the low end of its range; NXP's book-to-bill is above one. All three of Microchip, NXP and Analog Devices have now posted four consecutive quarters of accelerating revenue growth.
The 30-day losses belong to SiTime, MaxLinear and Lattice, artificial-intelligence data-center names down 21% to 27%, while the analog large caps moved less than two points. The business explains almost none of Microchip's and NXP's three-month declines into forward earnings of 20.4x and 15.7x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
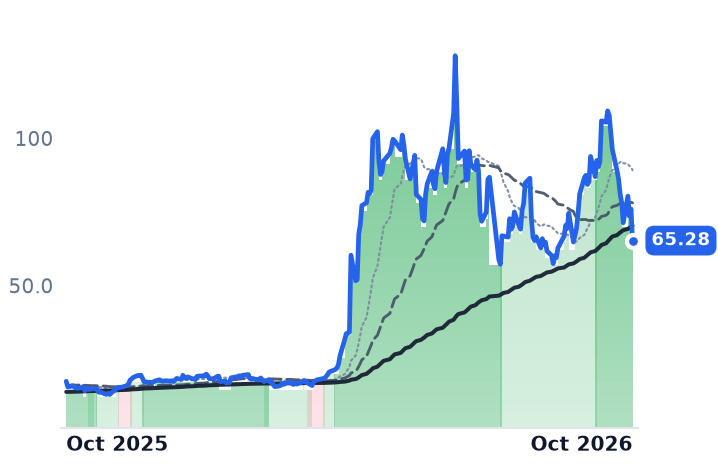
TXN | Texas Instruments Incorporated | Analog & Power Management | 🟢 Cont. Bull | +2.5% | +65.7% |
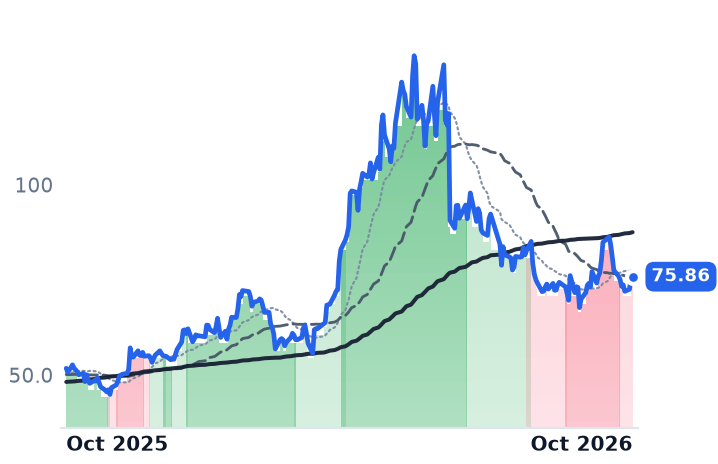
MCHP | Microchip Technology Incorporated | Processors & Accelerators | ⚠️ Emerging Bear | −1.3% | +16.2% |
NXPI | NXP Semiconductors | Processors & Accelerators | ⚠️ Emerging Bear | +1.0% | +8.8% |
ADI | Analog Devices | Analog & Power Management | 🟢 Cont. Bull | +0.1% | +59.6% |
ON | ON Semiconductor | Analog & Power Management | ⚠️ Emerging Bear | −1.2% | +41.4% |
| Compared against · context, not the story | |||||
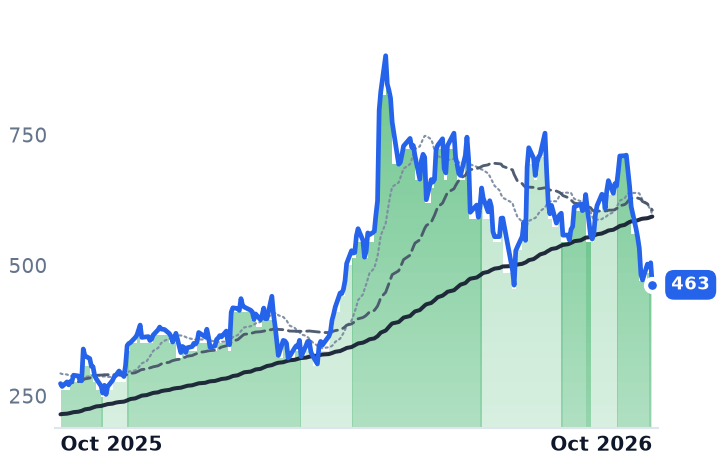
MXL | MaxLinear | Analog & Power Management | 🟢 Cont. Bull | −22.6% | +272.6% |
SITM | SiTime | Analog & Power Management | 🟢 Cont. Bull | −24.0% | +69.1% |
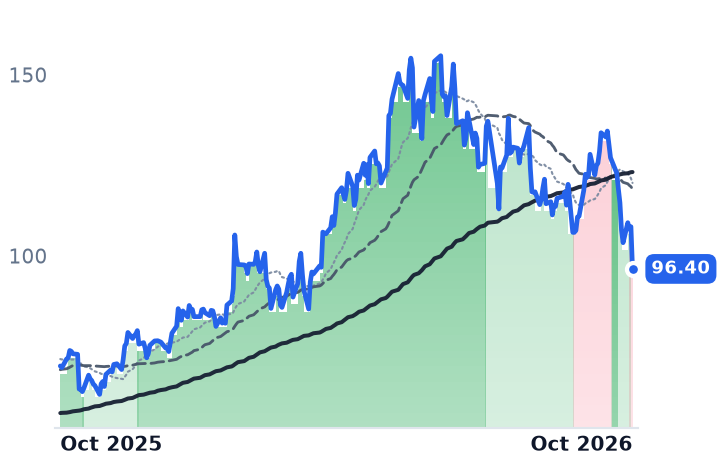
LSCC | Lattice Semiconductor | Processors & Accelerators | ⚠️ Emerging Bear | −20.8% | +38.5% |
12-month price & trend
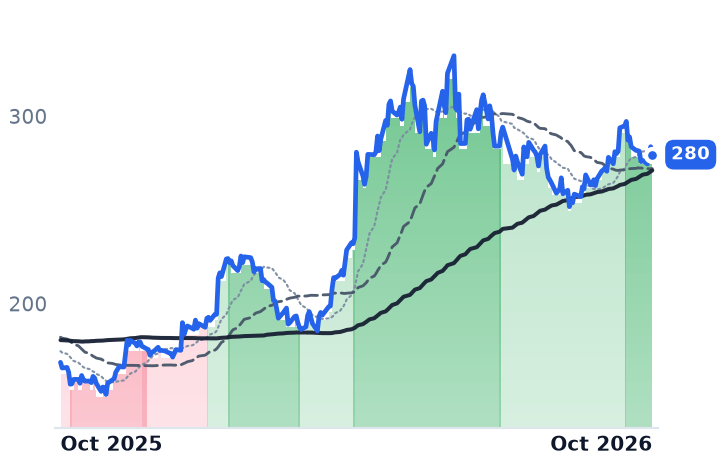
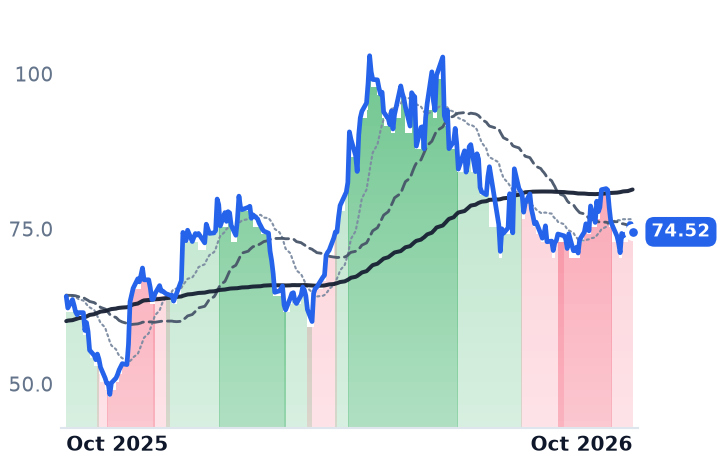
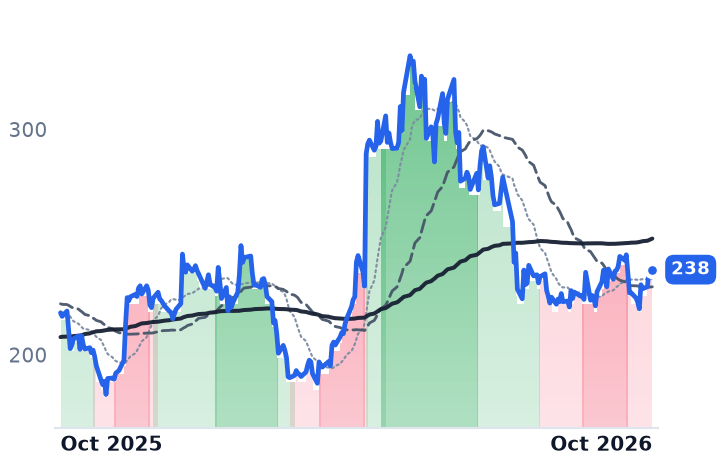
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXN | $255.3B | 36.2x | 31.0x | 12.3x | 11.4x | 20.4x | 18.9x | 25.5x | 2.9% |
MCHP | $40.5B | 103.3x | 20.4x | 7.9x | 6.3x | 13.1x | 10.5x | 27.1x | 2.7% |
NXPI | $60.0B | 20.2x | 15.7x | 4.5x | 4.2x | 8.1x | 7.5x | 13.8x | 4.9% |
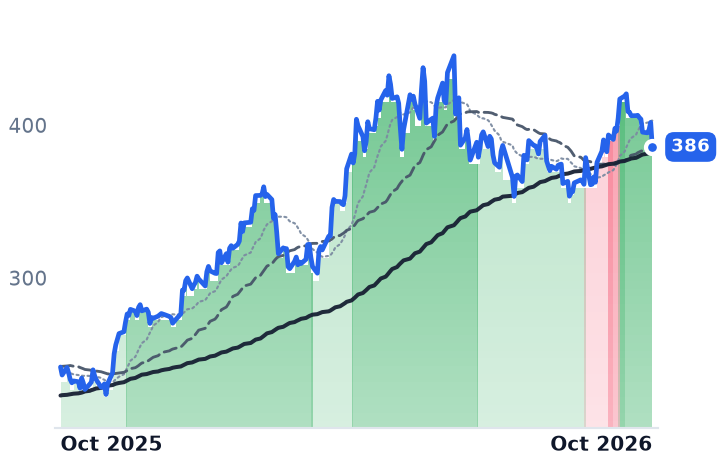
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADI | $186.9B | 45.5x | 29.9x | 13.5x | 12.4x | 20.5x | 18.8x | 27.6x | 2.6% |
MXL | $5.9B | n/m | 37.3x | 9.0x | 8.0x | 15.5x | 13.8x | 181.5x | -0.3% |
ON | $28.5B | 46.3x | 22.9x | 4.6x | 4.3x | 12.3x | 11.6x | 19.1x | 6.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SITM | $15.8B | — | 53.1x | 33.7x | 18.0x | 57.4x | 30.7x | 292.9x | 0.4% |
LSCC | $17.5B | 484.1x | 60.1x | 26.9x | 19.1x | 39.8x | 28.2x | 200.9x | 1.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TXN | Revenue | +26.4% | +17.6% | +10.3% |
| EPS | +64.7% | +28.2% | +15.7% | |
MCHP | Revenue | +6.2% | +37.3% | +16.6% |
| EPS | +20.7% | +132.9% | +25.7% | |
NXPI | Revenue | +16.9% | +12.1% | +8.3% |
| EPS | +28.5% | +21.3% | +16.2% | |
ADI | Revenue | +38.1% | +22.9% | +12.0% |
| EPS | +65.9% | +30.6% | +18.5% | |
MXL | Revenue | +58.7% | +32.7% | +18.3% |
| EPS | +505.2% | +57.1% | +25.0% | |
ON | Revenue | +9.3% | +13.0% | +13.5% |
| EPS | +37.3% | +41.2% | +29.7% | |
SITM | Revenue | +177.5% | +54.9% | +27.3% |
| EPS | +296.4% | +32.7% | +34.9% | |
LSCC | Revenue | +2.3% | +76.6% | +45.1% |
| EPS | +11.9% | +103.0% | +50.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Texas Instruments told shareholders on 20 October that the price of its analog chips turned up in the second half of 2026 after holding flat through the first. A distribution channel clearing out surplus parts does not start paying more for them.
The quarter around that line was the same shape. Texas Instruments, which sells analog and embedded chips into industrial, automotive and data-center customers, reported revenue of $6.06bn, up 28% year on year, with analog revenue of $4.9bn up 32% and gross margin 2.8 percentage points wider than the June quarter. Chief executive Haviv Ilan said industrial revenue only now matched the level it reached in the third quarter of 2022, its first new peak in four years, and that customers had not kept much inventory.
That matters because the analog and mixed-signal group has spent October being sold as if the restocking cycle were finished. Measured to 22 October, the analog companies are not the ones falling: Analog Devices is down 1.2% over thirty days, Microchip 1.7%, ON Semiconductor 0.5%, NXP up fractionally, Texas Instruments up 3%. The drawdown on the same shelf belongs to SiTime, down 27%, MaxLinear, down 25%, and Lattice Semiconductor, down 21%, all three levered to artificial-intelligence data-center spending.
Microchip is turning its fabs back on
Microchip, which sells microcontrollers and analog parts to automotive, industrial, computing and aerospace customers, ended June with 25 days of distributor inventory, which management called the lower end of its historical range, and internal inventory of $1.05bn, down ten days sequentially. Its June-quarter non-GAAP gross margin of 63.8% absorbed $38.5m of underutilization charges taken while the company raised factory loadings. "We kicked off fiscal 2027 on a strong note, with net sales increasing 38% year over year and 13.2% sequentially to $1.485 billion, above the high end of our guidance," chief executive Steve Sanghi said on 6 August. September-quarter guidance is $1.589-1.618bn, 8% sequential growth, at a 66-67% gross margin.
NXP's eleven weeks
NXP, the Eindhoven maker of automotive microcontrollers, processors and connectivity chips, carries the one number on the shelf that argues the other way: 11 weeks of channel inventory at the end of June, flat sequentially but above nine weeks a year earlier. Everything else points forward. Chief executive Rafael Sotomayor said on the July call that book-to-bill is above one and above the prior quarter, with customer escalations doubled and visibility improving into early 2027. Third-quarter guidance is $3.75bn plus or minus $100m, up 18% year on year.
Analog Devices has the growth and is charged for it
Analog Devices, which sells data converters, power management and sensors into industrial, automotive and instrumentation customers, posted its first $4bn quarter in August: revenue up 39.6% year on year, operating margin 40.1%, and an industrial segment that was 49% of revenue and grew 53%. "ADI delivered a strong third quarter, exceeding the midpoint of our revenue, margin, and earnings outlook as we capitalized on broad-based demand," chief executive Vincent Roche said on 19 August. It is also the dearest of the three, at 29.9x forward earnings against Microchip's 20.4x and NXP's 15.7x, the cheapest on the shelf.
The losses sit with the optical and timing vendors
MaxLinear is the clean test. It sells communications chips for optical transceivers and broadband gear, and on 22 October it reported September-quarter revenue up 72% year on year with its infrastructure segment up 210%, guided the December quarter to $240-260m against consensus near $227m, and the shares fell 13.9% that session. "The ASP on the DSP is more or less doubling, and then we have TIA that we did not add before," chief executive Kishore Seendripu told investors that day. The chip index had already fallen eight straight sessions into 16 October, its longest streak since 2008, on bond yields and the cost of debt-financed data-center build-outs.
The end-market weakness that does exist is narrower than the shelf-wide story. ON Semiconductor, which builds power and sensing silicon for electric vehicles, charging, solar and energy storage, grew June-quarter revenue 9.2% on a 38.4% gross margin, against 63% to 67% margins at the other three, and trades at 22.9x forward earnings on consensus growth of about 9% this year. The weak socket is auto power, not automotive and industrial demand generally.
So the results account for very little of what happened to Microchip and NXP, down 12.4% and 14.7% over ninety days while each compounded four consecutive quarters of accelerating growth and widening operating margin. Analog Devices is flat over the same stretch and up 60.5% on the year, which means its premium rests on a multiple that has stopped expanding rather than on anything in the October data. October was a financing and valuation event in the names attached to artificial-intelligence capital spending, and the analog cycle was collateral.
NXP reports on 27 October, the first of the three to print after all this. Whether that eleven weeks of channel inventory grew again is the only disclosure on the shelf capable of making the bearish case.