

Applied Digital Collects More From Building Data Centers Than From Renting Them
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Applied Digital's leases are repricing upward and its newest project notes priced 225 basis points cheaper than last year's, yet the shares have lost more than a third of their value in three months. The disclosures say why both can be true at once.
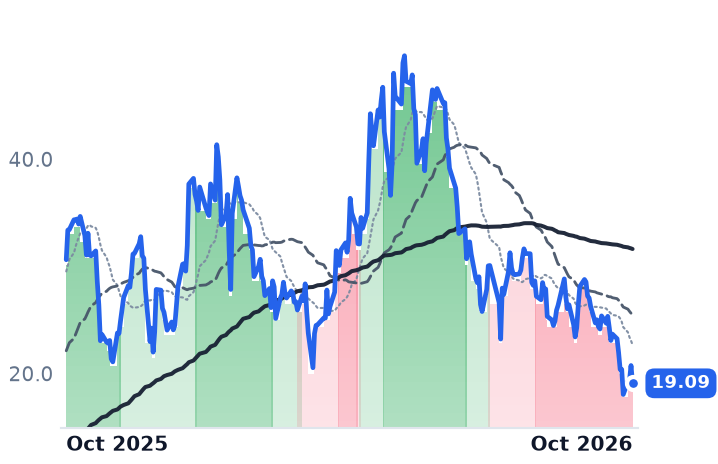
Of $341.9m of revenue in the quarter ended 31 August, $183.5m was fit-out construction performed for tenants and only $65.8m was base rent, pulling group gross margin to 15.3% from 42.5% two quarters earlier. Nothing in the leasing explains the fall. Applied Digital and Core Scientific run trailing free-cash-flow yields of -77.2% and -22.8%, which makes them claims on a financing market that repriced in the third quarter; Equinix and Digital Realty, funding from investment-grade balance sheets, fell a fraction as far.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
APLD | Applied Digital | Cloud & Computing Infrastructure | 🔴 Cont. Bear | −33.1% | −37.7% |
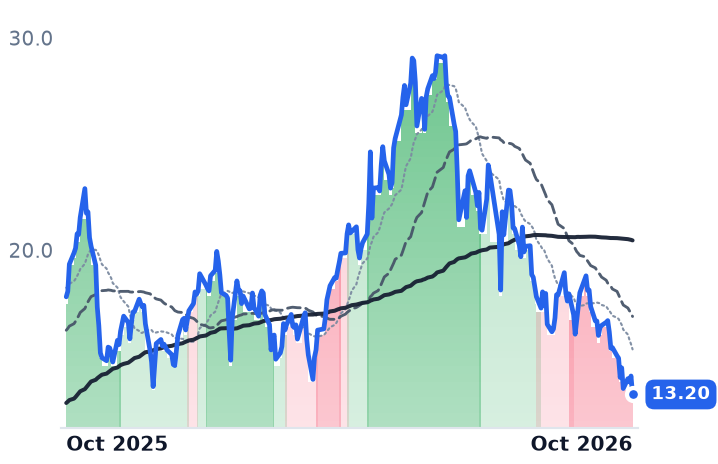
CORZ | Core Scientific | Vertical Industry Software | ⚠️ Emerging Bear | −29.7% | −25.8% |
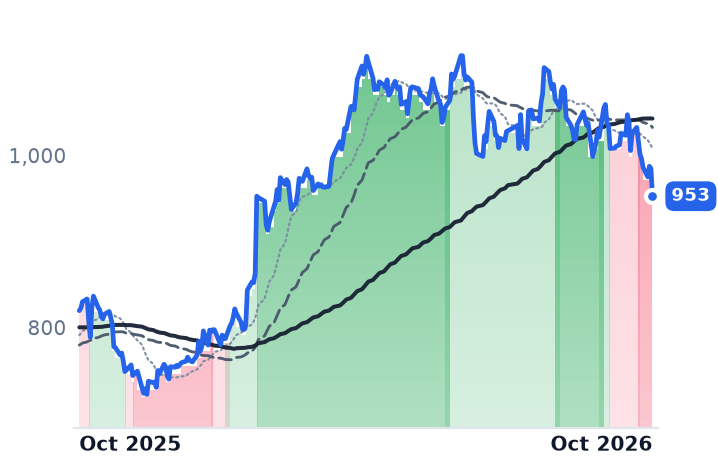
EQIX | Equinix | Data Center Operators | ⚠️ Emerging Bear | −10.1% | +16.2% |
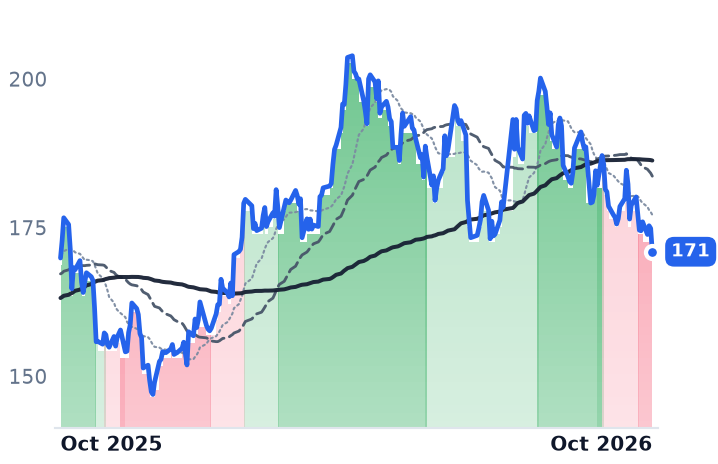
DLR | Digital Realty Trust | Data Center Operators | ⚠️ Emerging Bear | −7.9% | +0.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APLD | $5.8B | n/m | — | 6.8x | 6.1x | 33.4x | 30.2x | n/m | -77.2% |
CORZ | $4.2B | n/m | — | 9.6x | 6.2x | 34.1x | 22.0x | n/m | -22.8% |
EQIX | $94.0B | 61.1x | 55.5x | 9.6x | 9.1x | 18.5x | 17.7x | 25.9x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DLR | $63.4B | 78.8x | 60.9x | 9.3x | 8.9x | 67.3x | 64.7x | 23.4x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APLD | Revenue | +98.7% | +121.0% | +105.0% |
| EPS | −24.3% | +125.1% | −41.3% | |
CORZ | Revenue | +90.2% | +66.6% | +45.1% |
| EPS | +154.1% | −104.9% | +175.5% | |
EQIX | Revenue | +11.1% | +10.7% | +11.5% |
| EPS | +16.3% | +10.3% | +9.9% | |
DLR | Revenue | +17.5% | +11.0% | +14.5% |
| EPS | −23.3% | −6.4% | +22.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Applied Digital, which designs and operates single-tenant data centers for artificial-intelligence and high-performance computing workloads in North America, booked $341.9m of revenue in the quarter ended 31 August. The largest line inside it was fit-out construction performed for tenants, at $183.5m, against $65.8m of base rent and $37.8m of legacy bitcoin hosting. That mix pulled group gross margin to 15.3% from 42.5% two quarters earlier, even as adjusted earnings before interest, taxes, depreciation and amortization reached $64.4m against $0.5m a year earlier.
The shares have been read as a verdict on whether AI capacity is still worth what tenants agreed to pay for it. The company's own October disclosures describe the opposite happening on both sides of its economics: the leases repriced up and the debt repriced down. What moved against the equity was the price of the money that funds the gap between pouring concrete and sending an invoice.
The coupon fell 225 basis points while the stock fell by a third
"Our first Polaris Forge 1 related notes placed last year carry a 9.25% coupon. This tranche priced at 7%," chief financial officer Mohammad Saidal L. Mohmand told investors on 7 October, on $1.59bn of senior secured notes due 2031. The improvement was attributed to the investment-grade credit quality of CoreWeave, the company's anchor tenant. On the same call, chairman and chief executive Wesley Cummins said the company was targeting roughly 250MW of expansion leases by year-end at "materially higher" pricing, meaning 15%-plus rate increases and potentially longer duration, and expects to place more than 600MW into service over the next twelve months against 250MW in the prior twelve.
The contracted book is not speculative. As of 31 May the company disclosed 1,410MW of contracted critical IT load and approximately $36.2bn of take-or-pay leases with CoreWeave and investment-grade hyperscalers on initial 15-year terms.
What the equity is funding is construction
Trailing free cash flow runs at -77.2% of market value. That is the mechanism. A company placing 600MW into service spends the capital first and collects rent afterward, so its equity is a claim on the terms of the next financing rather than on the last quarter's leases. Those terms changed. The 10-year Treasury yield rose 87 basis points in the third quarter and touched its highest level since 2002 on 7 October, and the window for new data-center paper narrowed with it: listings for a Blackstone-backed AirTrunk vehicle, an Nvidia-backed developer, Firmus, and a SoftBank-backed developer, SB Energy, were pulled or paused, and a Korean data-center listing fell 30% on debut on 20 October.
The valuation has finally done work. With no earnings to anchor against, the usable measure is price to gross profit, at 33.4x trailing against 60.7x in late August; trailing price to sales is 6.8x and 6.1x forward, down from 14.3x in August and 28.7x in early May. The thin margin on fit-out revenue is why the sales multiple flatters this business and the gross-profit multiple does not.
Core Scientific's version of the problem is one payer
Core Scientific, which runs data-center facilities for digital-asset mining and colocation hosting for third parties, grew second-quarter revenue 108.8% to $164.2m with gross margin recovering to 42.7% from 6.4%, and still posted a $1.155bn net loss and negative book value. Its trailing free-cash-flow yield is -22.8%. CoreWeave supplied about 77% of first-half revenue under a 12-year colocation contract worth roughly $850m of average annualized revenue, take-or-pay, with no unilateral termination right. Durable terms, one counterparty, whose debt has traded toward distressed levels. Shareholders rejected CoreWeave's acquisition of the company in 2025, leaving it standalone. Its $13.20 close on 22 October was its low for the year, against a high of $29.16.
The split sorts by who needs outside capital
Over three months Applied Digital fell 36.5% and Core Scientific 44.1%, while Equinix fell 7.4% and Digital Realty 4.2%. Both incumbent landlords raised 2026 guidance in late July and de-rated anyway: Equinix, whose interconnection-rich colocation campuses connect carriers, clouds and enterprises, to roughly 22.2x the midpoint of guided adjusted funds from operations of $42.69–$43.29, against the 25–30x that franchise has historically commanded; Digital Realty, the wholesale and hyperscale landlord, to roughly 20.9x guided core funds from operations of $8.15–$8.20 against a 22–25x band. They fund from investment-grade balance sheets. The two operators fund from the market that just tightened.
So almost none of the four-to-tenfold difference in the fall is leasing. Applied Digital's rates are going up by its own account, and Digital Realty's second-quarter renewals repriced cash rents 25.4% higher. What repriced is the cost of capital spent before a tenant's first payment, plus, at Core Scientific, the standing of a single payer. The remaining question is political: investors now see the 3 November midterms as a channel for data-center backlash, through hearings and investigations that analysts doubt could materially stall construction.
"Put simply, our view is that every new restriction elsewhere makes what we already own harder to replicate and more valuable," Cummins said on 7 October. He is describing a moat that only pays once the megawatts are energized, and the next 600 of them have to be financed before a single invoice goes out.