

Kodiak's Compression Pricing Keeps Rising; Its Data-Center Power Schedule Is What Slipped
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
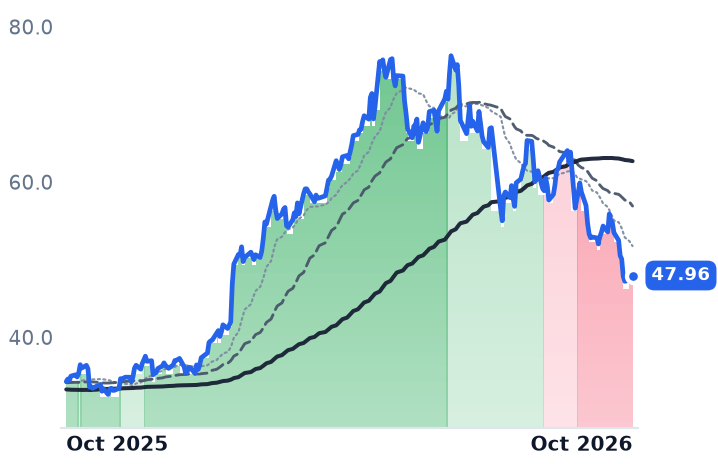
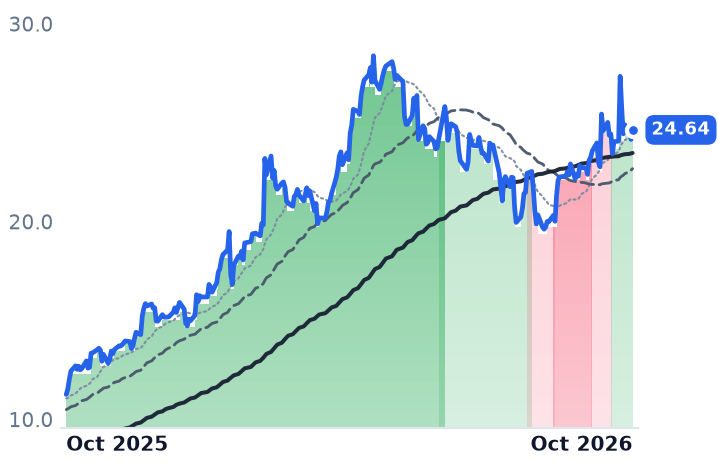
A quarter of Kodiak Gas Services' market value has gone since July, and the reading on offer is that the compressor shortage which set its rates has broken. Its own disclosures point the other way: the average monthly rate reached $23.80 per revenue-generating horsepower on 98.2% fleet utilisation, and second-quarter revenue growth accelerated to 21.1% year on year.
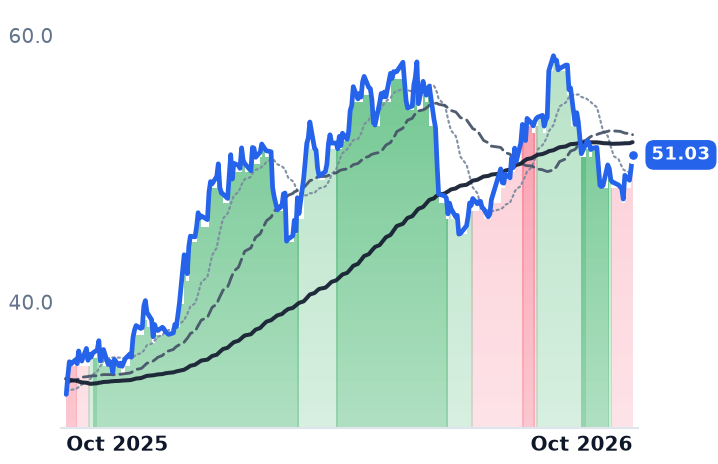
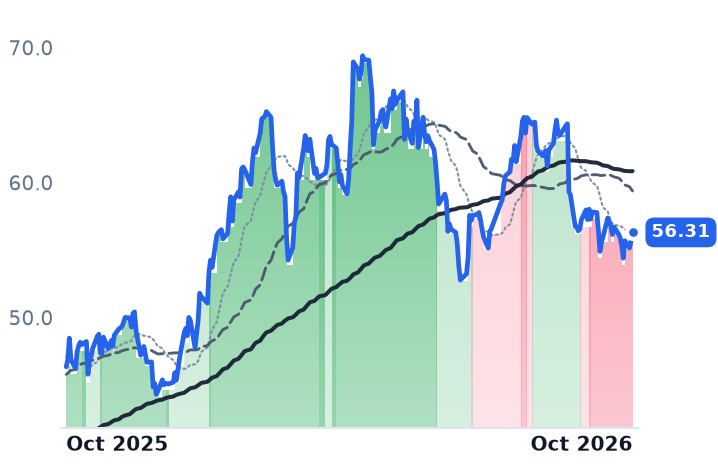
What was marked down in mid-October was the other business — roughly 395MW of behind-the-meter gas generation sold to data centers, where two brokers cut their targets citing deployment timing, not compression. Archrock is the single name on this shelf where the business itself weakened, its aftermarket book down 35%. USA Compression, whose average fleet grew to 4.45m horsepower, barely moved.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
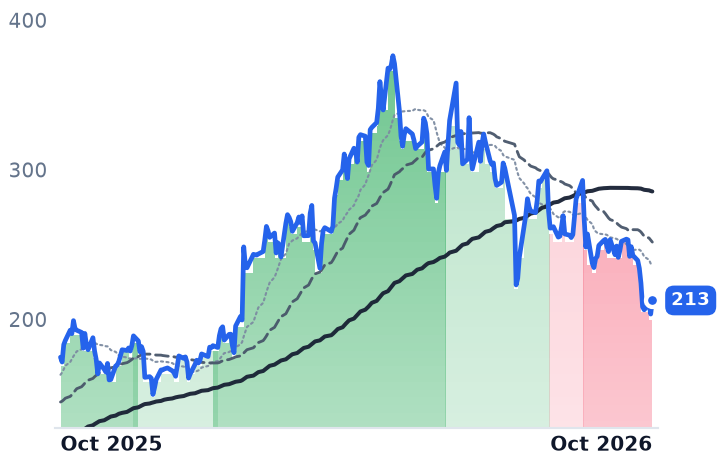
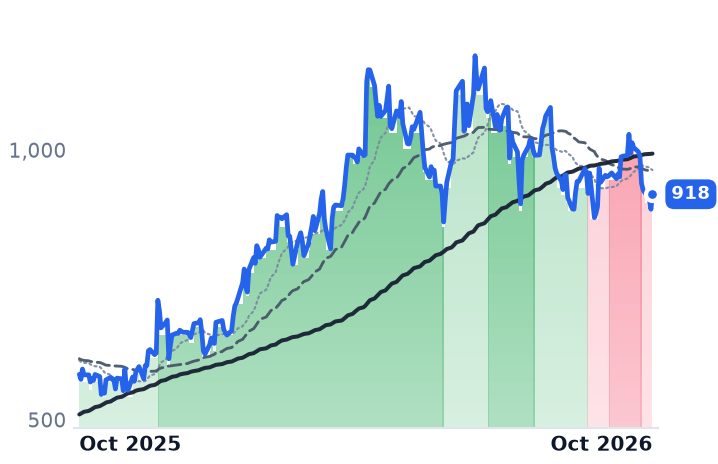
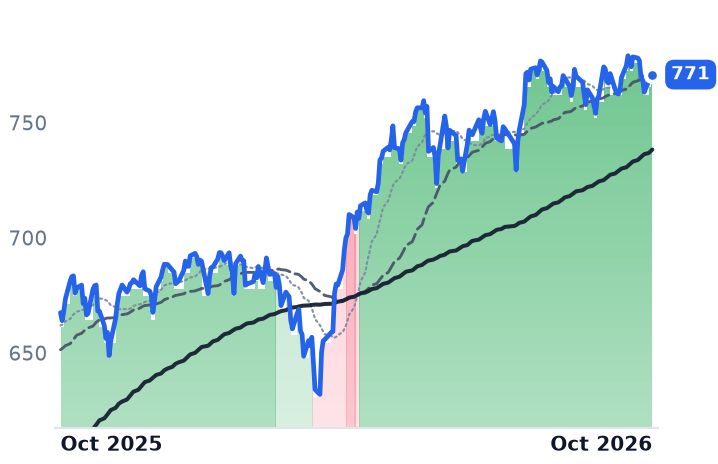
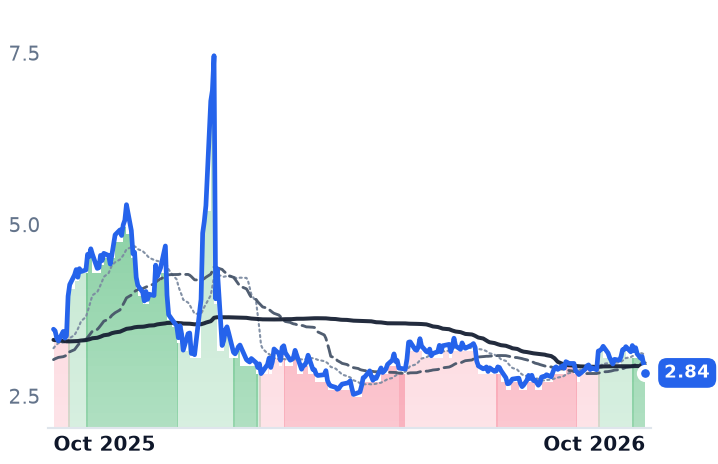
KGS | Kodiak Gas Services | Gas Compression & Processing | ⚠️ Emerging Bear | −15.8% | +39.8% |
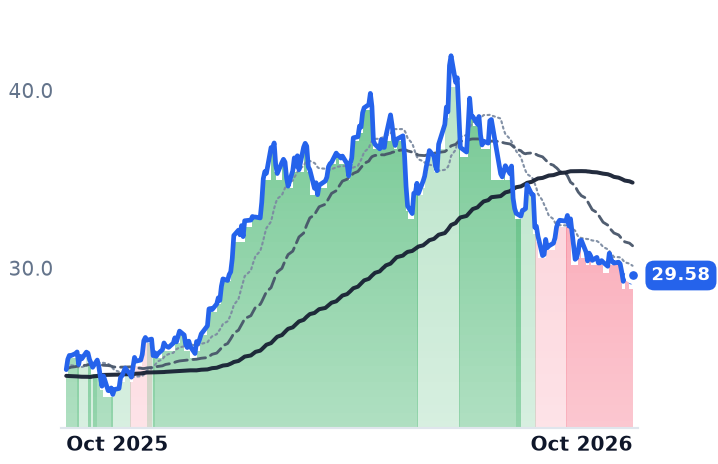
AROC | Archrock | Gas Compression & Processing | ⚠️ Emerging Bear | −4.3% | +21.8% |
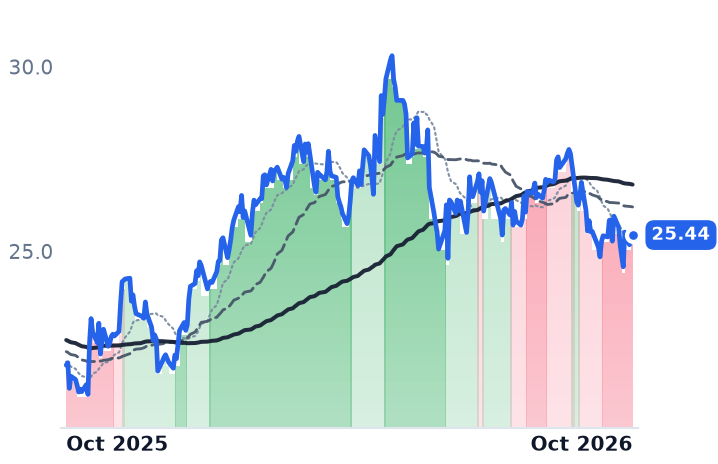
USAC | USA Compression Partners | Compression & Gas Processing | ⚠️ Emerging Bear | −2.5% | +16.1% |
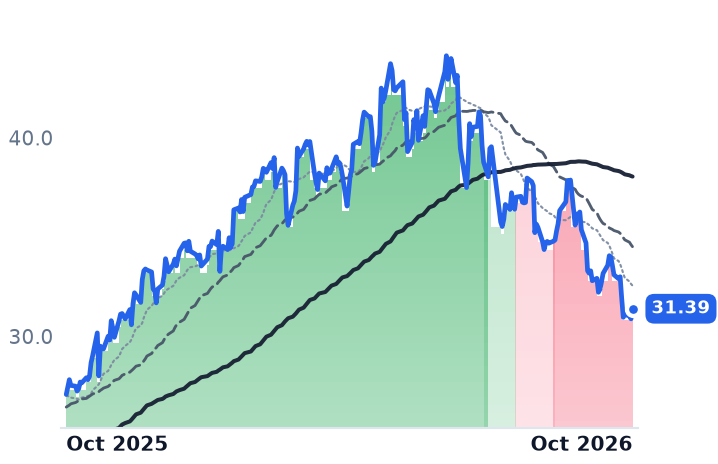
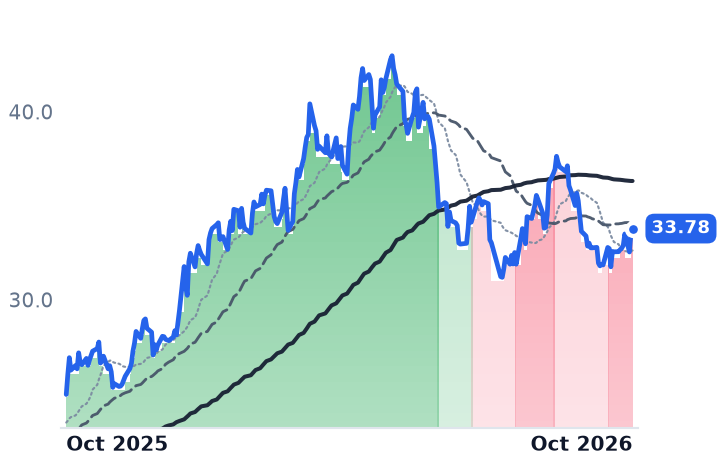
NGS | Natural Gas Services | Compression & Gas Processing | ⚠️ Emerging Bear | −9.5% | +15.9% |
| Compared against · context, not the story | |||||
EFXT | Enerflex | Gas Compression & Processing | ⚠️ Emerging Bear | +8.5% | +118.7% |
SLB | Slb | Integrated Oilfield Services | 🟢 Cont. Bull | −1.6% | +54.3% |
BKR | Baker Hughes | Integrated Oilfield Services | ⚠️ Emerging Bear | −2.9% | +21.5% |
HAL | Halliburton | Integrated Oilfield Services | 🔴 Cont. Bear | +1.2% | +35.4% |
VRT | Vertiv | Advanced Power Systems | ⚠️ Emerging Bear | −15.9% | +21.7% |
GEV | GE Vernova | Power Generation & Propulsion | ⚠️ Emerging Bear | −3.7% | +57.1% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.4% | +15.5% |
NG=F | NG=F | — | 🔴 Cont. Bear | −1.6% | −18.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KGS | $5.0B | 55.7x | 24.7x | 3.6x | 3.3x | 8.9x | 8.1x | 8.1x | 0.1% |
AROC | $5.2B | 16.0x | 17.3x | 3.5x | 3.4x | 6.0x | 5.9x | 9.4x | 5.6% |
USAC | $3.7B | 23.7x | 19.7x | 3.1x | 2.7x | 7.0x | 6.0x | 9.9x | 8.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NGS | $407.6M | 19.4x | 18.2x | 2.2x | 1.9x | 4.9x | 4.3x | 8.8x | -7.7% |
EFXT | $3.1B | 47.8x | 13.3x | 1.1x | 0.9x | 4.8x | 4.0x | 7.8x | 9.6% |
SLB | $75.9B | 24.6x | 20.6x | 2.1x | 2.1x | 12.6x | 12.4x | 12.0x | 6.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BKR | $62.0B | 19.9x | 23.7x | 2.2x | 2.2x | 9.5x | 9.4x | 13.2x | 5.0% |
HAL | $27.3B | 17.1x | 14.0x | 1.2x | 1.2x | 8.1x | 8.1x | 8.1x | 6.3% |
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GEV | $267.6B | 28.5x | 33.0x | 6.5x | 5.8x | 32.0x | 28.6x | 28.5x | 4.6% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
NG=F | — | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
KGS | Revenue | +16.3% | +14.4% | +18.0% |
| EPS | +78.4% | +41.3% | +40.0% | |
AROC | Revenue | +1.9% | +7.6% | +7.7% |
| EPS | +9.4% | +19.2% | +15.9% | |
USAC | Revenue | +37.8% | +6.9% | +4.6% |
| EPS | +38.5% | +26.7% | +20.0% | |
NGS | Revenue | +25.8% | +18.8% | +8.3% |
| EPS | +7.2% | +45.8% | +14.5% | |
EFXT | Revenue | +0.8% | +11.7% | +31.6% |
| EPS | +23.0% | +37.5% | +39.5% | |
SLB | Revenue | +4.1% | +7.8% | +6.7% |
| EPS | −13.9% | +28.6% | +15.5% | |
BKR | Revenue | +2.3% | +10.9% | +7.5% |
| EPS | +6.7% | +14.6% | +20.0% | |
HAL | Revenue | +2.0% | +5.4% | +4.6% |
| EPS | +3.0% | +23.2% | +16.9% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
GEV | Revenue | +24.0% | +14.6% | +14.9% |
| EPS | +319.0% | −19.6% | +41.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Kodiak Gas Services, which leases large-horsepower compressors to Permian producers and the midstream companies that gather their gas, rented that equipment at the best rates in its history last quarter and accelerated its revenue growth while doing it. Its shares have lost roughly a quarter of their value since July.
The fall has been read as the compression tightness cycle topping out — new large-horsepower units finally arriving in volume, capping the monthly rate per horsepower that is a contract compressor's entire earnings engine. Every input that thesis needs moved the wrong way for it. Rates rose, utilisation held near full, and the engines that would have to arrive to break the squeeze are ordered years out. What actually changed in October was the delivery schedule on Kodiak's second business: about 395MW of distributed gas generation, two-thirds of it contracted to data centers.
The rate card went up, not sideways
Kodiak's average monthly rate reached $23.80 per revenue-generating horsepower, up 4.5%, on 98.2% fleet utilisation and record quarterly adjusted earnings before interest, tax, depreciation and amortisation of $216.8m. Second-quarter revenue of $391.1m was 21.1% higher year on year, against 4.9% growth in the first quarter. "Strong demand for large horsepower compression continued to drive improvements in pricing and utilization," chief executive Mickey McKee said on the second-quarter call in August. New-unit horsepower is already fully contracted for 2026 and into 2027.
The supply side is worse, not better, for anyone hoping to add fleet: packaged gas-engine lead times have stretched from a historical 40-to-60 weeks out to 200 weeks as generator buyers compete for the same blocks. "New large horsepower lead times remain extended, and that reality is driving customers to make compression decisions further out than they historically have," USA Compression chief executive Micah Green told Gas Compression Magazine on October 12. The demand behind it is also still building: Permian dry gas supply passed 26 Bcf/d for the first time on September 6, and the Energy Information Administration projects 29.6 Bcf/d in 2027.
The markdown was aimed at the megawatts
In September Kodiak signed a six-year agreement to supply roughly 76MW of baseload power behind the meter at a West Texas data center using about 40 reciprocating gas units — its second long-term primary-power contract, taking about half the power portfolio under long-term contract. That is the part analysts repriced. On October 16 RBC Capital's Elvira Scotto cut her target to $82 from $88 while keeping her Outperform rating, citing "a reduced Power Infrastructure EBITDA multiple due to equipment deployment timing" with long-term estimates unchanged; Mizuho went to $72 on a more back-weighted deployment schedule.
The company Kodiak fell with says the same thing. Over three months its 25.6% decline sat beside Vertiv's 27.1% and GE Vernova's 11.0%, while Schlumberger rose 10.0% and Baker Hughes 2.1%. Mid-October brought a financing shock to the AI buildout, with hotter inflation data pushing AI-linked issuers to delay fundraising — which reprices anyone whose growth depends on data-center capital spending. Kodiak now trades at 8.13x trailing EV/EBITDA, against roughly 9.8x for both large lessors in late August, and at 24.7x forward earnings versus 55.7x trailing.
Archrock is where the business genuinely weakened
One name on this shelf earns its de-rating. Archrock, the largest US contract compression provider, has seen revenue fall sequentially for three straight quarters, with second-quarter revenue down 3.1% year on year and operating income down 53.7%. The lease book is fine — contract operations margin held at 71%, a seventh consecutive quarter above 70%. The damage is in aftermarket services, the parts-and-overhaul book, where revenue fell 35% to $42.0m from $64.8m. Consensus 2026 earnings of $1.72 a share sit below the $1.84 Archrock earned in 2025, which is why its 17.3x forward multiple is above its 16.0x trailing. Chief executive Brad Childers still called the market "structurally tight," and guided $1.4bn to $1.6bn of growth capital for 2027 through 2030.
So the shelf splits on cause rather than on sentiment. Kodiak, Natural Gas Services and USA Compression all grew revenue at double digits or better into the drawdown — USA Compression's average fleet rose to 4.45m revenue-generating horsepower from 3.55m, with distributable cash flow covering its distribution 1.65x and leverage at 3.72x, and it fell only 4.9%. The gap between that and Kodiak's quarter is not operating: it is the share of enterprise value sitting in power megawatts whose in-service dates moved. Archrock's is operating, and concentrated in one line. Front-month gas slipping below $3/MMBtu on October 20 thins sentiment across all four, though compression revenue is contracted and rate-based.
Archrock reports third-quarter results after the close on October 27 against consensus of $385.95m, essentially flat on a year ago; Kodiak follows on November 3. Those prints will say whether the rate per horsepower is still climbing. They will say nothing about when a gas turbine arrives at a West Texas data center, which is the question the market has actually been answering.