

IES Holdings Bolted $1.5bn of Structural Steel Onto Its Record-Margin Electrical Business
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A month that erased more than a quarter of IES Holdings' market value has been read as the end of the skilled-trade labor scarcity behind contractors' best margins ever. The company's June quarter points the other way: revenue up 39.6% year on year, operating margin wider at 14.37%, and signed backlog up 91% since fiscal year-end.
The one visible margin reset is self-administered. The $691m DBM Global close on 5 October adds structural-steel fabrication revenue to an electrical contractor that just earned a 27.41% gross margin, and the sell-side fiscal-2027 EBITDA margin drops to 12.99% from 16.53%. Comfort Systems is the mirror image: its forward multiple fell to 28.7x while estimates still assume margins widen. APi Group, whose work is mostly recurring inspection, rose over the same month.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
IESC | IES | Building Systems | ⚠️ Emerging Bear | −28.0% | −41.0% |
FIX | Comfort Systems USA | Building Systems | ⚠️ Emerging Bear | −13.8% | +70.7% |
APG | APi | Building Systems | 🔴 Cont. Bear | +7.8% | +15.8% |
| Compared against · context, not the story | |||||
EME | EMCOR | Power Grid & Distribution | ⚠️ Emerging Bear | −7.9% | +1.4% |
PWR | Quanta Services | Power Grid & Distribution | 🟢 Cont. Bull | −5.4% | +38.8% |
MTZ | MasTec | Energy Solutions | ⚠️ Emerging Bear | −16.9% | −10.9% |
DY | Dycom Industries | Digital & Communications | ⚠️ Emerging Bear | −17.8% | −17.0% |
STRL | Sterling Infrastructure | Civil Infrastructure | ⚠️ Emerging Bear | −19.6% | +13.6% |
MYRG | MYR | Power Grid & Distribution | ⚠️ Emerging Bear | −2.6% | +32.7% |
AAON | AAON | HVAC & Refrigeration Systems | ⚠️ Emerging Bear | −3.9% | −27.9% |
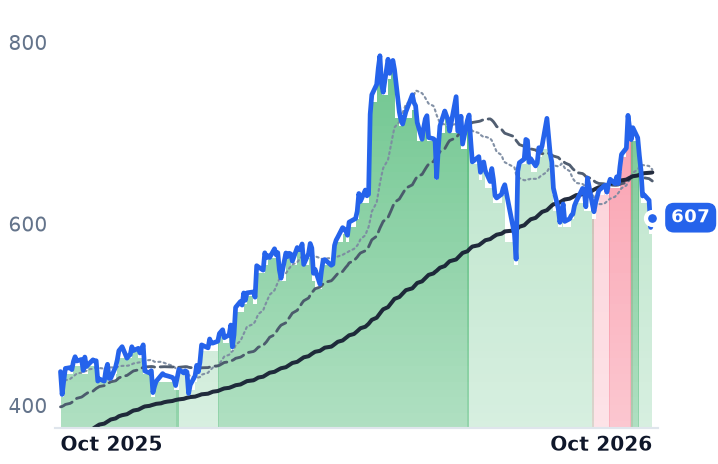
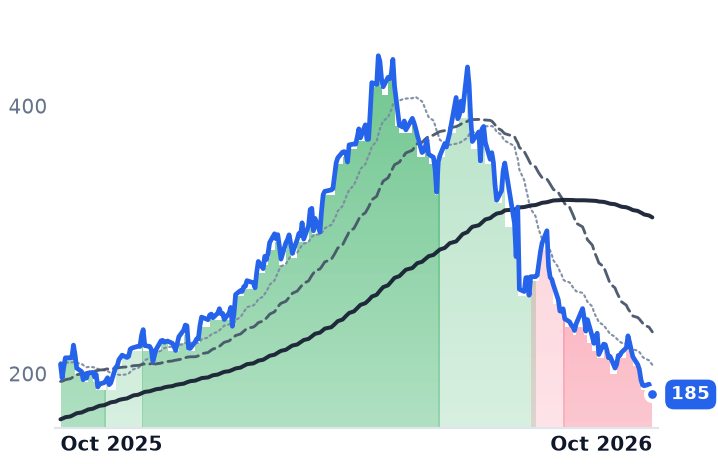
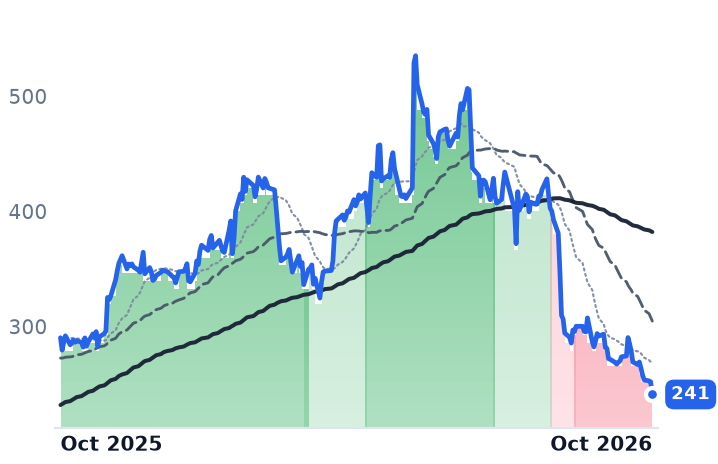
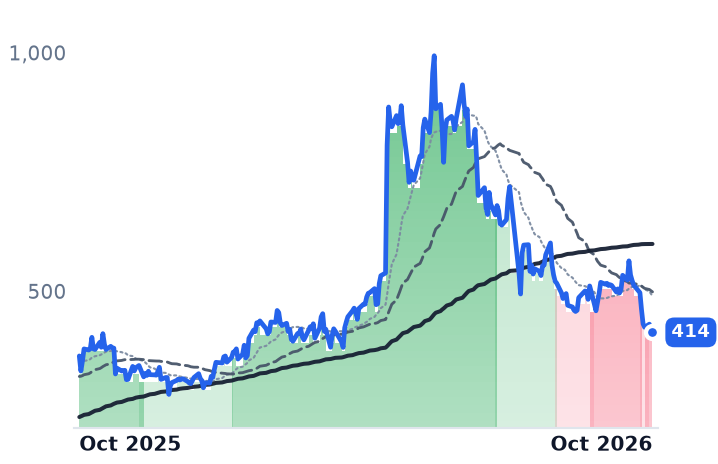
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IESC | $9.5B | 20.6x | 17.4x | 2.4x | 1.5x | 9.2x | 5.8x | 15.5x | 2.4% |
FIX | $49.5B | 34.6x | 28.7x | 4.4x | 3.8x | 17.2x | 14.8x | 24.1x | 4.4% |
APG | $17.4B | n/m | 23.3x | 2.1x | 1.9x | 7.1x | 6.6x | 22.8x | 3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EME | $34.8B | 24.6x | 24.0x | 1.9x | 1.7x | 9.5x | 8.7x | 15.3x | 3.4% |
PWR | $101.7B | 76.5x | 40.4x | 3.1x | 2.6x | 21.5x | 17.8x | 35.5x | 2.4% |
MTZ | $17.3B | 34.0x | 23.2x | 1.1x | 1.0x | 9.4x | 8.3x | 15.4x | 1.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DY | $8.1B | 24.3x | 15.8x | 1.2x | 1.1x | 6.2x | 5.6x | 9.2x | 5.8% |
STRL | $16.4B | 38.0x | 26.9x | 4.8x | 4.0x | 20.2x | 17.0x | 22.6x | 2.9% |
MYRG | $4.7B | 28.7x | 25.0x | 1.2x | 1.1x | 9.6x | 8.7x | 15.8x | 4.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAON | $7.1B | 44.4x | 36.2x | 3.7x | 3.1x | 14.3x | 12.0x | 25.2x | -1.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IESC | Revenue | +27.7% | +48.1% | +18.8% |
| EPS | +76.1% | +16.8% | +17.2% | |
FIX | Revenue | +47.8% | +19.0% | +17.3% |
| EPS | +86.8% | +22.8% | +23.5% | |
APG | Revenue | +14.1% | +7.9% | +7.0% |
| EPS | +19.7% | +15.0% | +13.5% | |
EME | Revenue | +21.4% | +10.9% | +8.3% |
| EPS | +30.1% | +13.0% | +13.2% | |
PWR | Revenue | +41.1% | +16.2% | +13.8% |
| EPS | +57.6% | +17.8% | +17.9% | |
MTZ | Revenue | +29.2% | +18.9% | +15.4% |
| EPS | +44.9% | +34.5% | +31.0% | |
DY | Revenue | +17.1% | +39.6% | +12.7% |
| EPS | +39.5% | +51.2% | +19.7% | |
STRL | Revenue | +71.5% | +21.2% | +17.3% |
| EPS | +91.2% | +28.0% | +20.6% | |
MYRG | Revenue | +22.9% | +15.5% | +11.4% |
| EPS | +72.5% | +18.4% | +22.2% | |
AAON | Revenue | +65.6% | +17.6% | +16.3% |
| EPS | +68.8% | +51.4% | +26.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
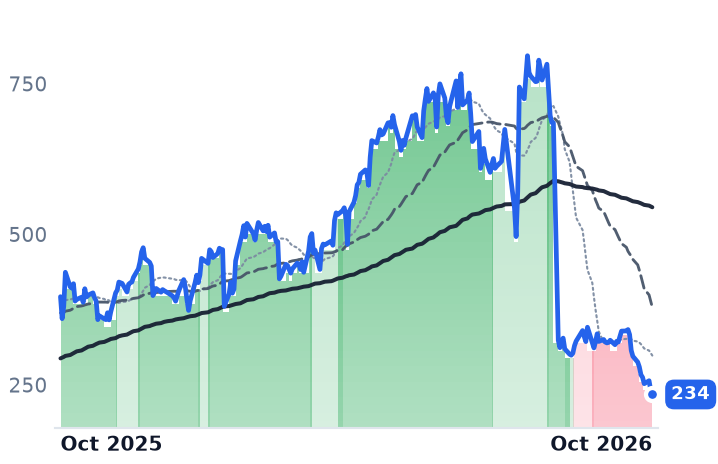
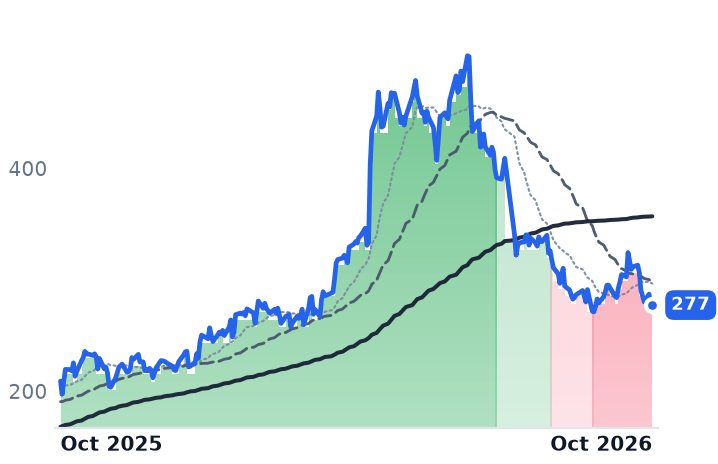
IES Holdings completed the largest acquisition in its history on 5 October, paying about $691m for DBM Global, a vertically integrated structural-steel fabrication, erection and industrial construction platform. The Houston electrical and technology-systems contractor buying it had just reported a record gross margin of 27.41%. DBM booked roughly $1.5bn of revenue in the twelve months to 30 June. From 6 October to 21 October, IES shares fell 31.5%, including a 9.7% drop on 7 October.
That markdown has been read as the end of the skilled-trade labor scarcity that let mechanical and electrical contractors price data-center work at the widest margins in their history. The operating numbers do not support that reading. June-quarter revenue of $1.24bn grew 39.6% year on year, operating margin widened to 14.37% from 12.57%, and non-GAAP backlog reached roughly $4.5bn, up 91% since fiscal year-end, with $2.289bn of the $2.8bn in signed performance obligations expected to convert to revenue inside twelve months.
The margin reset IES wrote itself
The one place a margin reset appears is the forward estimate, and the company put it there. Consensus has fiscal-2027 revenue growing 48.1% to $6.275bn while EBITDA margin falls to 12.99% from 16.53% and net margin to 8.69% from 11.03%, so earnings per share advance only 16.8%. Structural-steel fabrication does not earn what integrated electrical installation earns, and adding $1.5bn of it to a business running at a 27.41% gross margin changes the blend. That consensus rests on a single analyst, so the level is indicative.
IES was explicit about the trade. "As our largest acquisition to date, we were deliberate in how we financed the transaction, with a focus on maintaining our strong balance sheet by using a combination of cash, borrowings and IES equity," executive chairman Jeff Gendell said on 5 October. Chief executive Matt Simmes framed the roughly 4,000 incoming employees as a cross-sell into "data center, industrial and infrastructure markets."
At 20.6x trailing and 17.4x forward earnings, IES is the cheapest of the three Building Systems names on both measures. That discount now sits against a forecast that already assumes a thinner blend.
Comfort Systems' estimates never followed its multiple
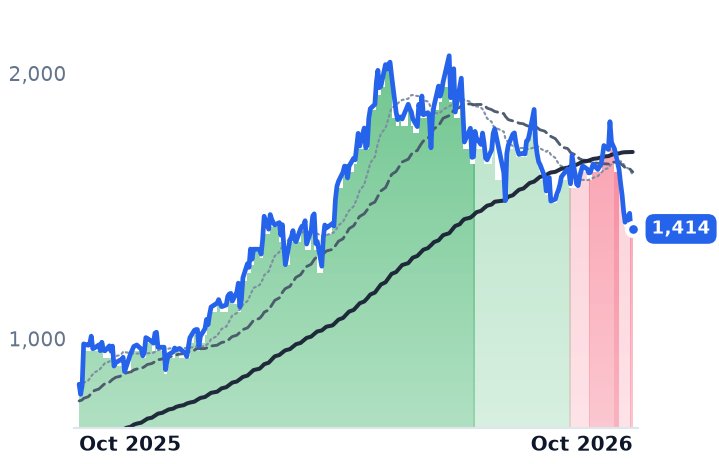
Comfort Systems USA, which installs and maintains heating, ventilation, piping, controls and electrical systems and fabricates modules off site, is the opposite arrangement. Its June quarter was a fifth consecutive period of gross-margin expansion, to 25.88%, on revenue up 50.3%, with backlog of $14.06bn and $13.70bn of that on a same-store basis — meaning the increase was overwhelmingly organic. "Demand remains strong, especially in technology, as we continue to book work with good margins and favorable working conditions for our valuable people," chief executive Brian Lane said on 23 July.
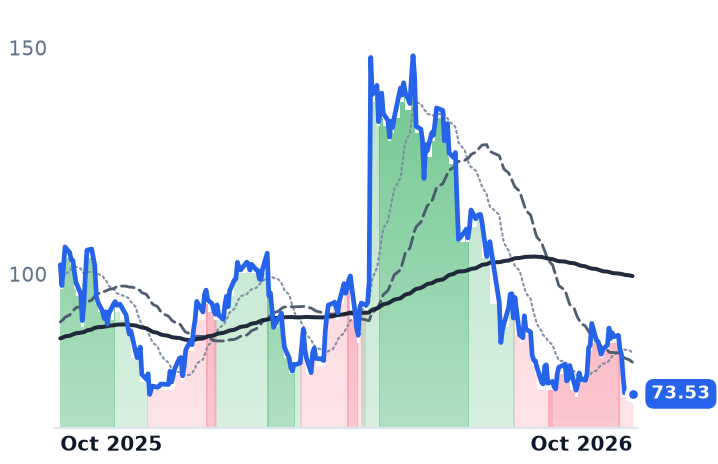
Shares are down 20.3% over three months and 31.6% below their June peak. The fiscal-2027 consensus still embeds an EBITDA margin of 17.58%, rising to 18.31% the year after. The forward multiple has gone to 28.7x from the 36x to 46x recorded in early May; the margin assumption inside the estimate has not moved.
What tightened in October was the financing for the jobs
The change sits outside both income statements. Yields on CoreWeave's unsecured notes flared to 15% and beyond as data-center bonds hit fresh lows. Nvidia-backed Firmus, Blackstone-backed AirTrunk and SB Energy, owned by SoftBank, all shelved or paused listings, and South Korean cloud company Elice fell 30% on its market debut on 20 October. Of roughly 140 US data-center projects slated to open in 2026, nearly half have been delayed or cancelled, with power infrastructure and parts availability the binding constraints.
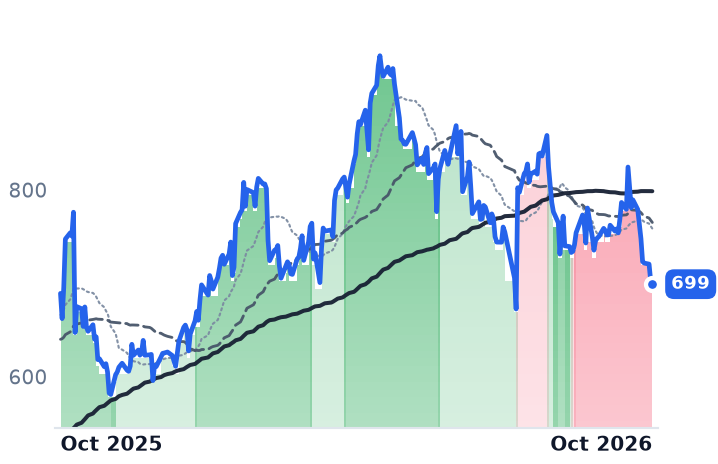
That is a timing problem for signed work, not a pricing problem for new bids, and it discounts a backlog by pushing out when it converts. The rest of the data-center builders were priced the same way: MasTec fell 47.5% over three months, Dycom 43.1% and Sterling Infrastructure 40.4%, while the two largest, EMCOR and Quanta, fell 8.1% and 5.1%.
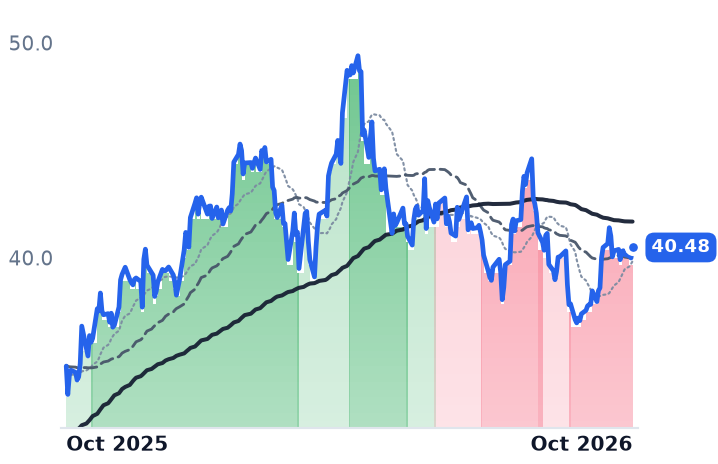
APi Group, the fire-protection and entry-systems contractor that targets more than 60% of revenue from inspection, service and monitoring, guided third-quarter organic growth of 8% to 10% and rose 7.8% over the past 30 days. Recurring inspection revenue carries no pad date to slip, which is why a single "Building Systems" label describes no shared operating trend here.
So the drawdown accounts for the duration of these order books and almost nothing about their profitability. At IES the thinner forward margin is disclosed, bought and dated; at Comfort Systems no one has marked the margin down anywhere except the share price.
Comfort Systems reports its September quarter after the close on 22 October. The gross-margin line will say whether the labor-pricing cycle broke in the third quarter, or whether the market simply decided it must have.