

Soybean Oil Became Half the Value of a Crushed Bean, and a Biofuel Rule Now Sets Its Price
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The fear on this shelf is that the crush plants built to feed renewable diesel have flooded the protein-meal market and destroyed the margin per bushel that is a processor's whole earnings engine. The flood is real and the margin survived it: the board crush spread stood at $2.67½ a bushel in mid-October while US meal output runs toward 65m short tons at $310-315 a ton, because oil's share of the bean's value has climbed toward 50% from about 35%.
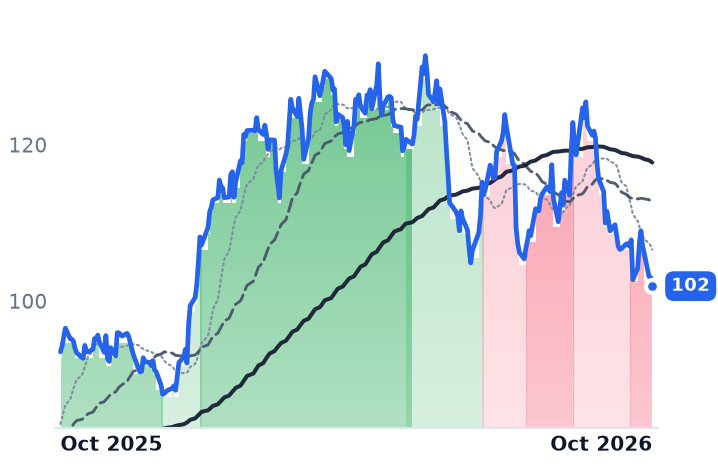
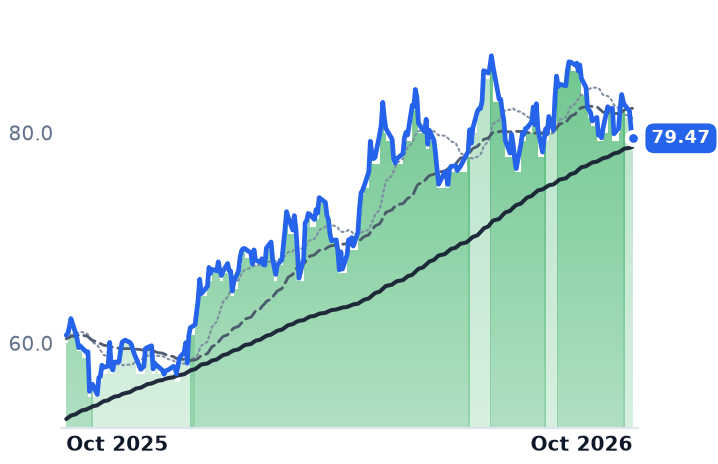
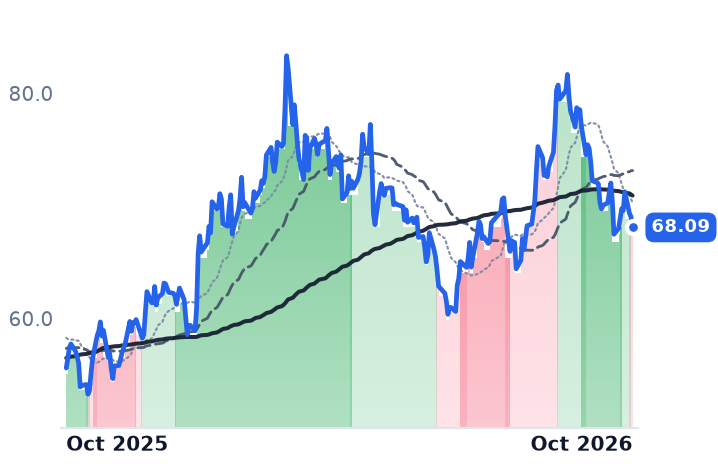
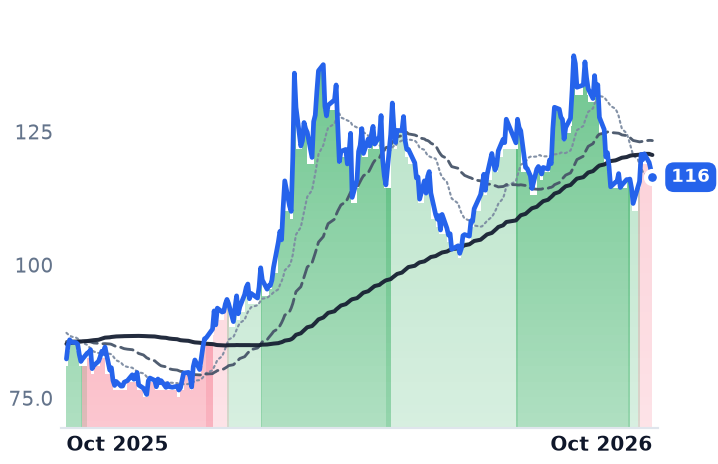
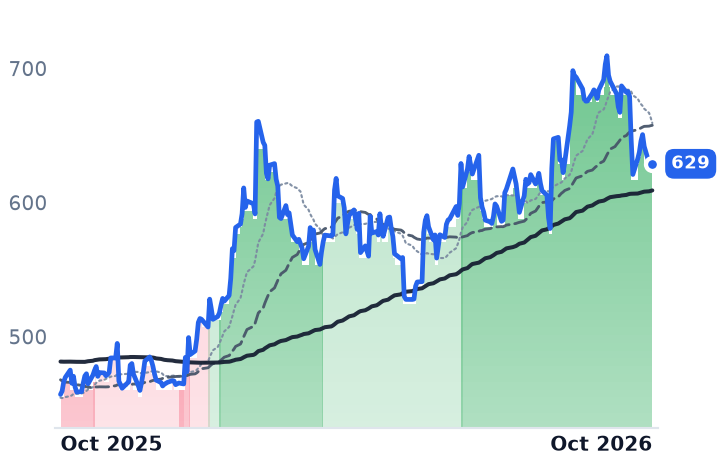
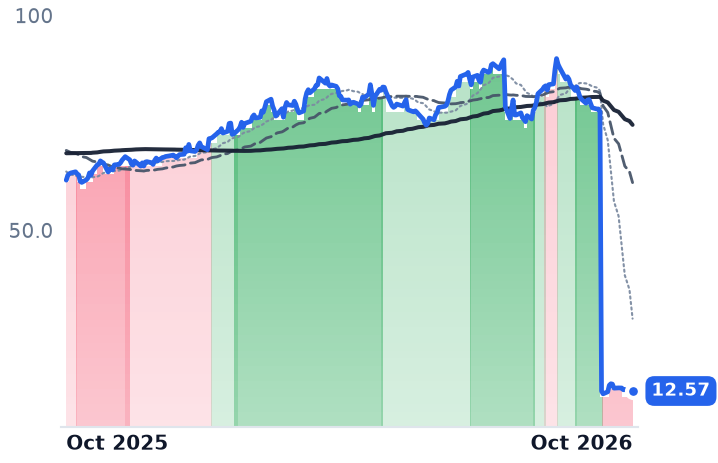
That shift moved the pressure point from the feed lot to Washington. Bunge, whose soybean and softseed processing produced $700m of $796m of adjusted segment earnings in the June quarter, has fallen 16% in three months after the Environmental Protection Agency left open whether reallocated refinery exemption volumes land in 2026 or 2027. Archer-Daniels-Midland, down 8%, is the less processing-levered of the two and held its uptrend longer.
Neither company's results explain the slide. Both raised expectations; Bunge now guides to $9.25-$9.75 of adjusted earnings per share.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BG | Bunge Global | Commodity Processors | 🔴 Cont. Bear | −10.6% | +9.0% |
ADM | Archer-Daniels-Midland | Commodity Processors | 🟢 Cont. Bull | −5.7% | +30.8% |
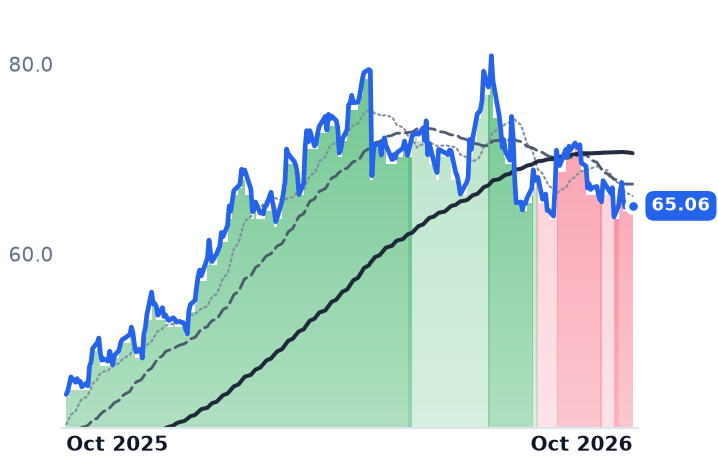
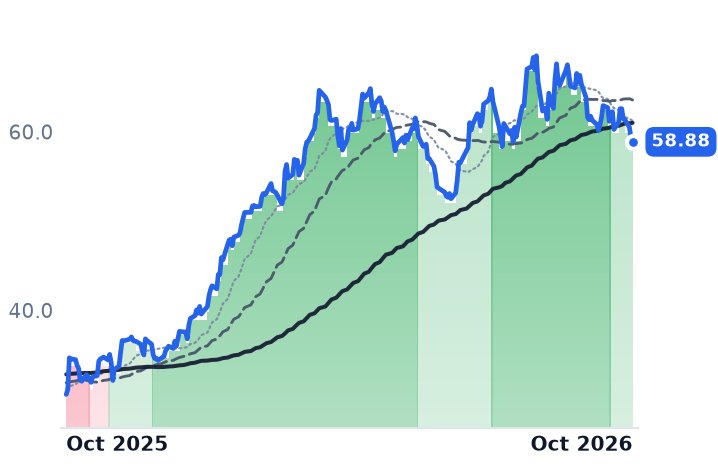
ANDE | The Andersons | Commodity Processors | ⚠️ Emerging Bear | −6.0% | +43.9% |
| Compared against · context, not the story | |||||
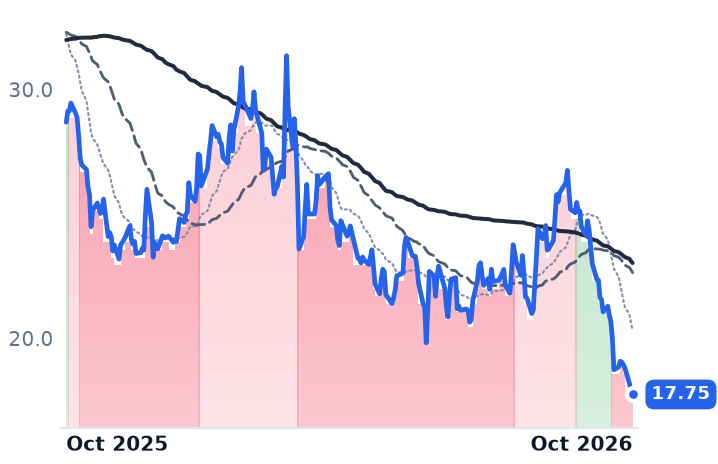
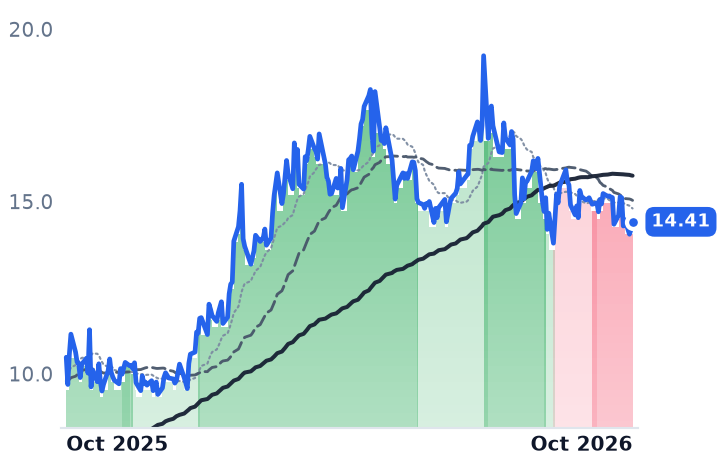
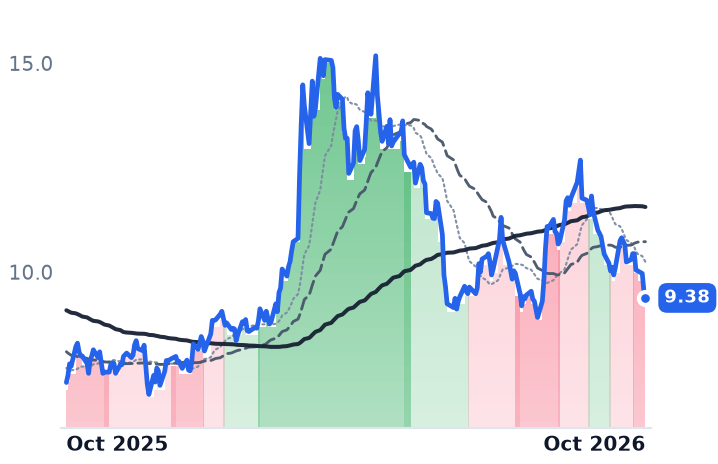
MOS | The Mosaic | Phosphate & Potash Nutrients | 🔴 Cont. Bear | −26.5% | −38.1% |
NTR | Nutrien | Diversified Input Distributor | ⚠️ Emerging Bear | −8.7% | +22.4% |
CF | CF Industries | Nitrogen Fertilizers | 🟢 Cont. Bull | −7.1% | +41.4% |
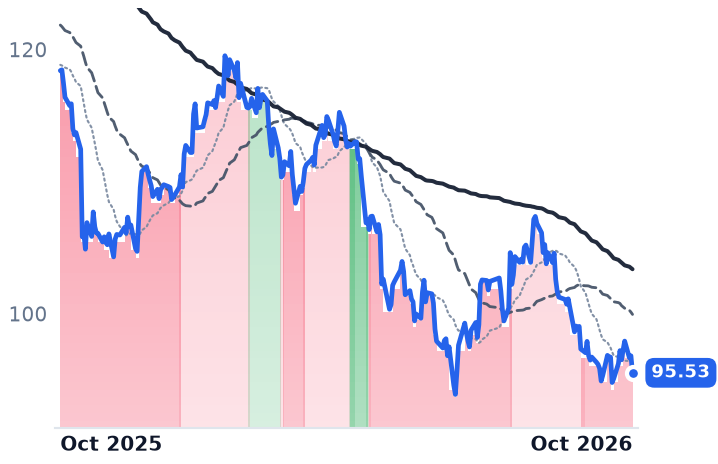
DAR | Darling Ingredients | Ingredient Solutions | 🟢 Cont. Bull | −7.8% | +92.7% |
GPRE | Green Plains | Biofuels | ⚠️ Emerging Bear | −4.2% | +37.5% |
DE | Deere | Farm Tractors & Equipment | 🟢 Cont. Bull | −9.1% | +37.6% |
AGRO | Adecoagro | Diversified Farming | ⚠️ Emerging Bear | −14.7% | +27.5% |
INGR | Ingredion Incorporated | Ingredient Solutions | 🔴 Cont. Bear | −1.6% | −19.3% |
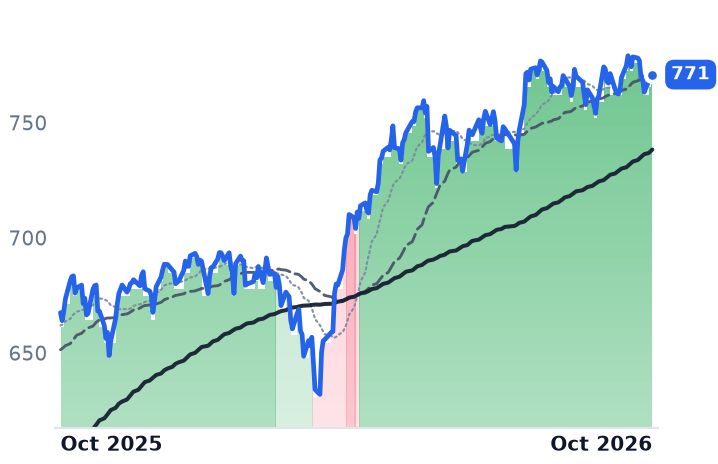
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.4% | +15.5% |
CTVA | Corteva | Integrated Seed & Crop | 🟢 Cont. Bull | −84.2% | −79.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BG | $19.6B | 19.6x | 10.8x | 0.2x | 0.2x | 4.3x | 4.3x | 11.5x | -3.6% |
ADM | $38.2B | 21.7x | 14.4x | 0.5x | 0.4x | 6.8x | 6.3x | 9.9x | 4.4% |
ANDE | $2.2B | 12.6x | 11.9x | 0.2x | 0.2x | 2.6x | 2.4x | 9.0x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MOS | $6.0B | 95.0x | 45.0x | 0.5x | 0.5x | 4.4x | 4.3x | 5.7x | -15.7% |
NTR | $37.0B | 15.6x | 15.6x | 1.3x | 1.3x | 4.2x | 4.3x | 7.7x | 5.7% |
CF | $18.1B | 8.8x | 8.0x | 2.3x | 2.2x | 5.5x | 5.2x | 4.6x | 10.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DAR | $10.7B | 17.9x | 10.6x | 1.6x | 1.6x | 6.5x | 6.3x | 9.9x | 8.2% |
GPRE | $1.0B | 8.3x | 7.1x | 0.6x | 0.5x | 5.7x | 5.5x | 6.0x | 11.3% |
DE | $175.4B | 36.1x | 36.0x | 3.7x | 4.2x | 10.3x | 11.8x | 19.7x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AGRO | $5.8B | 157.5x | 6.8x | 3.5x | 2.6x | 11.7x | 8.7x | 12.8x | 0.8% |
INGR | $6.4B | 10.8x | 9.6x | 0.9x | 0.9x | 3.7x | 3.7x | 6.4x | 10.3% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CTVA | $8.9B | 8.9x | 23.4x | 0.5x | 0.5x | 1.0x | 1.1x | 3.5x | 7.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BG | Revenue | +35.8% | +3.0% | −0.2% |
| EPS | +27.7% | +18.6% | +8.7% | |
ADM | Revenue | +5.9% | +6.0% | +5.2% |
| EPS | +63.1% | +6.1% | −0.6% | |
ANDE | Revenue | +0.2% | +3.3% | +10.6% |
| EPS | +131.6% | +16.2% | −100.0% | |
MOS | Revenue | +0.8% | +7.5% | −1.4% |
| EPS | −83.2% | +243.8% | +39.0% | |
NTR | Revenue | +5.2% | −1.3% | −1.1% |
| EPS | +6.8% | −0.3% | −8.0% | |
CF | Revenue | +16.6% | −9.6% | −6.1% |
| EPS | +67.9% | −24.7% | −20.6% | |
DAR | Revenue | +3.6% | +14.5% | +4.1% |
| EPS | −68.8% | +1308.0% | −7.4% | |
GPRE | Revenue | −14.6% | +5.6% | +2.2% |
| EPS | −206.4% | −18.1% | +21.4% | |
DE | Revenue | +8.2% | +8.7% | +8.0% |
| EPS | −1.8% | +25.4% | +19.6% | |
AGRO | Revenue | +62.6% | +3.1% | +0.5% |
| EPS | +467.1% | −21.4% | −1.4% | |
INGR | Revenue | −0.6% | +1.4% | +1.4% |
| EPS | −5.9% | +6.4% | +5.6% | |
CTVA | Revenue | −1.2% | −54.0% | +3.3% |
| EPS | +14.3% | +27.0% | +16.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Environmental Protection Agency proposed on 13 October to hand back to the fuel market all of the renewable fuel credits it had excused small refineries from in August, and put two timing options out for comment: split that volume between the 2026 and 2027 compliance years, or push every ton of it into 2027. The feedstock those obligations turn into demand reacted the next day, with Chicago December soybean oil at 67.11 cents a pound. Bunge Global, which crushes soybeans, rapeseed, canola and sunflower into vegetable oil and protein meal, has kept sliding since.
The explanation on offer for that slide has been a glut of crush capacity drowning the meal side of the bean and collapsing the margin per bushel. The supply half of that is true. Crushers are running at record rates toward 2.75bn bushels in 2026/27 and roughly 65m short tons of meal, and the Department of Agriculture sees meal pinned at $310-315 a ton through the marketing year. What the glut has not done is break the spread, because the same plants were built to make oil, and oil's share of a crushed bean's value has risen toward 50% from about 35%. The board crush was $2.67½ a bushel in mid-October, up five cents.
The margin moved from the feed lot to the rule book
When half the bean's value is a biofuel feedstock, a compliance calendar prices the crush. Domestic soybean oil going into biofuel is forecast to grow 25% to 17.8 billion pounds, demand the Agriculture Department attributes directly to federal volume obligations and state mandates. October's WASDE left that biofuel forecast unchanged. The quantity of demand did not deteriorate in the month the shares fell; the question of which year it is owed in did.
What the June quarters already banked
Bunge's soybean and softseed processing delivered $700m of $796m of adjusted segment earnings in the June quarter, 88% of the total, and the company raised full-year adjusted earnings guidance to $9.25-$9.75 from $9.00-$9.50. Soy processing margins were "the best we've seen in a while," chief executive Greg Heckman told the 29 July call, where management said meal demand "continues to really surprise quarter after quarter" — the opposite of a meal-driven squeeze. Archer-Daniels-Midland, which buys oilseeds and corn and sells vegetable oils, meals, sweeteners and ethanol, reported oilseeds segment profit up 129% with crush volumes up nearly 5%, credited to renewable volume obligation demand.
Most of a crusher's quarter is also bought before it begins. North American crushing was about 90% covered for the third quarter and 30% for the fourth, chief executive Juan Luciano said on ADM's 4 August call, so an October spot move reaches reported earnings with a lag.
A complex-wide de-rating with one levered name inside it
Shares tell a different story. Bunge is down 16.1% over three months and ADM 7.8%, against a 3.0% gain in an S&P 500 tracking fund, and the month's weakness ran through fertilizer and rendering alike: Mosaic fell 26.5%, Nutrien 8.7%, Darling Ingredients 7.8% and CF Industries 7.1% over 30 days while the index fund was flat. JPMorgan trimmed its ADM target to $75 from $77 on 12 October at underweight and Bunge's to $139; Barclays set $150 on Bunge two days later.
So almost none of the fall traces to the per-bushel economics, which accelerated. Bunge's larger drawdown follows from its mix: nine-tenths of segment earnings come from the leg a biofuel rule prices, while ADM spreads the same exposure across carbohydrate and nutrition businesses. The live doubt is the ramp both prices embed. Bunge earned $3.82 in the first half, and consensus full-year earnings of $9.42 require $5.60 in the second, 47% more; chief financial officer John Neppl guided crush margins to the "low 40s" in the third quarter and the "high 50s" in the fourth. At 10.8x forward earnings against 19.6x trailing and 1.24x book, Bunge is the cheaper of the pair, with the caveat that trailing free cash flow is negative 3.6% of market value on Viterra working capital. ADM's 14.4x forward against 21.7x trailing is only cheap if the consensus $5.52 of 2026 earnings arrives against $2.23 actually earned in 2025.
Luciano described ADM's four-plant crush expansion as a "phased approach to allow for offramps" — a careful way to build into the best margins the industry has seen, and a measure of how durable management treats legislated demand. The comment file on where the exemption volumes land stays open into December. Bunge reports on 29 October with a quarter that was largely priced before any of it.