

Powell's Record Switchgear Orders Are Intact; Its Buyers' Borrowing Costs Rose in October
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The electrical-equipment shelf fell hard in the middle of October, and the reading on offer is that scarcity pricing for switchgear has finally cracked. The dates point elsewhere: no supplier disclosed anything new, and the names that fell are the ones whose end customers finance construction with debt.
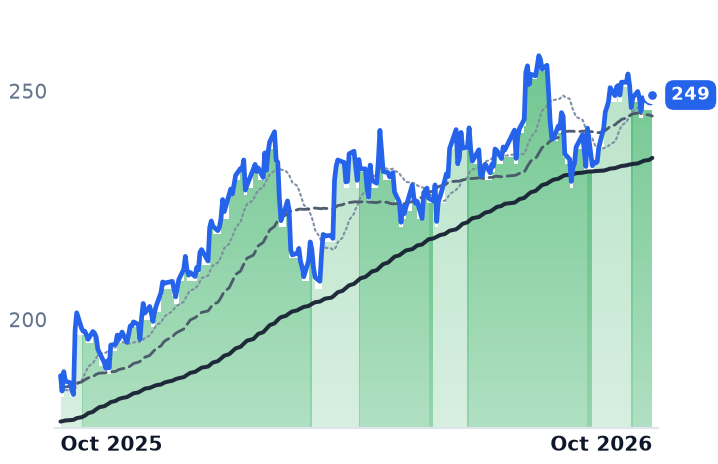
Powell Industries' last disclosure, on 4 August, was a record $934m of new orders, a book-to-bill of 3.0x for the quarter, and backlog up to $2.4bn from $1.4bn at the end of September 2025. Gross margin widened through the fiscal year to 30.6%. Hubbell, whose June-quarter sales were about 60% utility products, barely moved while Vertiv, nVent and Eaton fell double digits.
Powell now trades at 24.7x forward earnings against 49.2x trailing in May, on consensus earnings growth of 27.8% for fiscal 2027.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
POWL | Powell Industries | Power Distribution Systems | ⚠️ Emerging Bear | −10.5% | +44.7% |
HUBB | Hubbell Incorporated | Power Distribution Systems | ⚠️ Emerging Bear | +1.0% | +6.3% |
| Compared against · context, not the story | |||||
ETN | Eaton | Power Distribution Systems | 🟢 Cont. Bull | −10.1% | +5.5% |
VRT | Vertiv | Advanced Power Systems | ⚠️ Emerging Bear | −15.9% | +21.7% |
NVT | nVent Electric | Power Distribution Systems | 🟢 Cont. Bull | −10.1% | +44.7% |
GEV | GE Vernova | Power Generation & Propulsion | ⚠️ Emerging Bear | −3.7% | +57.1% |
PWR | Quanta Services | Power Grid & Distribution | 🟢 Cont. Bull | −5.4% | +38.8% |
ATKR | Atkore | Power Distribution Systems | 🟢 Cont. Bull | +0.5% | +42.8% |
AME | AMETEK | Industrial Components & Services | 🟢 Cont. Bull | +3.0% | +32.7% |
EMR | Emerson Electric | Industrial Automation & Motion Control | 🟢 Cont. Bull | +7.0% | +23.9% |
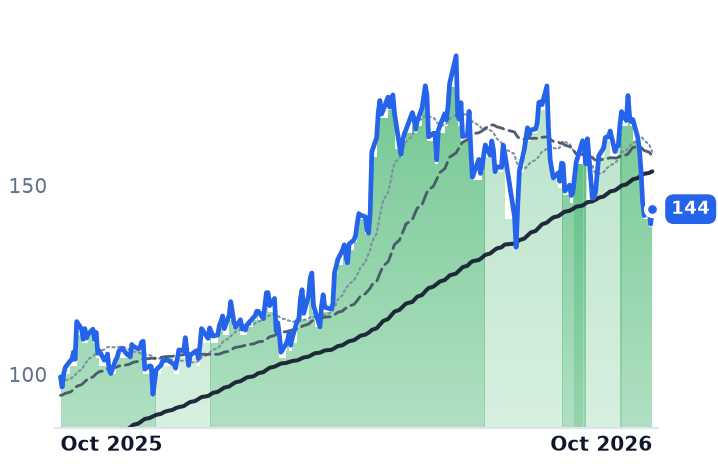
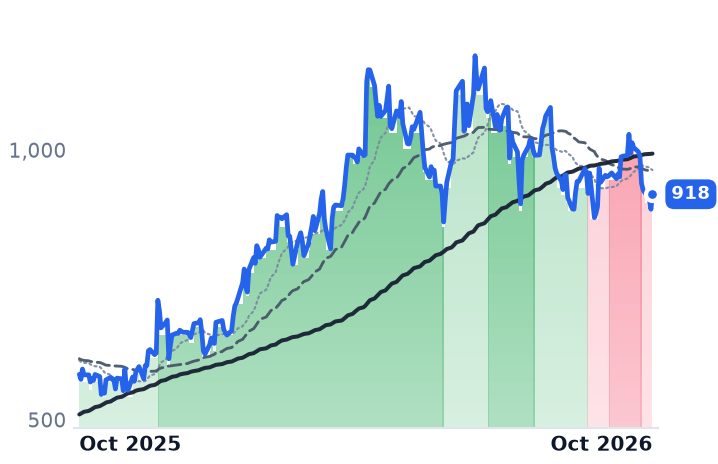
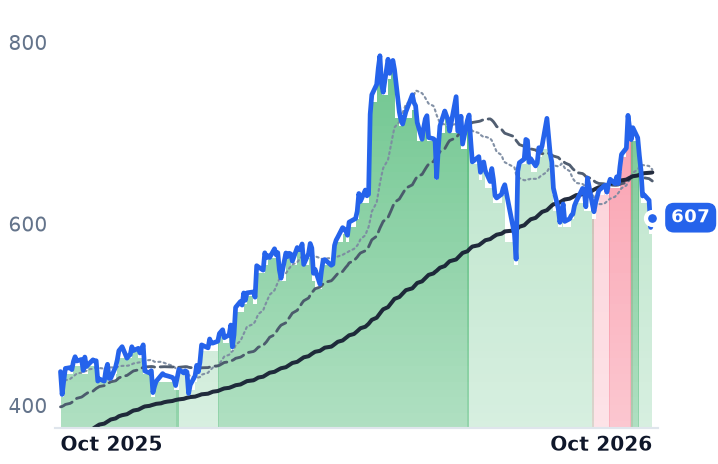
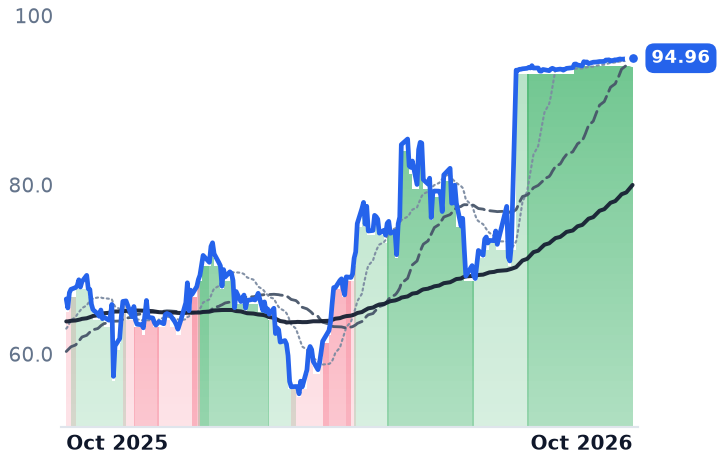
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWL | $6.2B | 32.4x | 24.7x | 5.4x | 4.1x | 17.8x | 13.7x | 22.4x | 3.9% |
HUBB | $24.3B | 27.2x | 22.5x | 3.9x | 3.5x | 11.1x | 10.1x | 20.0x | 3.7% |
ETN | $168.6B | 44.0x | 32.0x | 5.6x | 5.1x | 15.6x | 14.2x | 29.3x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
NVT | $27.4B | 46.0x | 33.0x | 5.7x | 5.0x | 15.3x | 13.6x | 28.6x | 2.1% |
GEV | $267.6B | 28.5x | 33.0x | 6.5x | 5.8x | 32.0x | 28.6x | 28.5x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $101.7B | 76.5x | 40.4x | 3.1x | 2.6x | 21.5x | 17.8x | 35.5x | 2.4% |
ATKR | $3.2B | n/m | 14.9x | 1.1x | 1.0x | 5.6x | 5.2x | n/m | 1.8% |
AME | $54.9B | 34.9x | 28.8x | 7.0x | 6.7x | 19.1x | 18.3x | 23.4x | 3.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EMR | $90.5B | 35.2x | 22.1x | 4.9x | 4.5x | 9.1x | 8.5x | 19.9x | 3.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
POWL | Revenue | +8.8% | +25.8% | +14.4% |
| EPS | +12.1% | +27.8% | +19.8% | |
HUBB | Revenue | +17.7% | +10.4% | +6.4% |
| EPS | +12.7% | +12.3% | +10.9% | |
ETN | Revenue | +20.0% | +11.2% | +9.7% |
| EPS | +12.6% | +19.3% | +17.2% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
NVT | Revenue | +42.8% | +21.1% | +15.3% |
| EPS | +54.3% | +27.3% | +19.0% | |
GEV | Revenue | +24.0% | +14.6% | +14.9% |
| EPS | +319.0% | −19.6% | +41.4% | |
PWR | Revenue | +41.1% | +16.2% | +13.8% |
| EPS | +57.6% | +17.8% | +17.9% | |
ATKR | Revenue | +5.0% | +4.7% | +6.6% |
| EPS | −13.4% | +11.5% | +13.6% | |
AME | Revenue | +11.3% | +6.3% | +6.1% |
| EPS | +12.8% | +9.7% | +8.7% | |
EMR | Revenue | +4.5% | +5.6% | +5.4% |
| EPS | +9.4% | +11.2% | +10.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
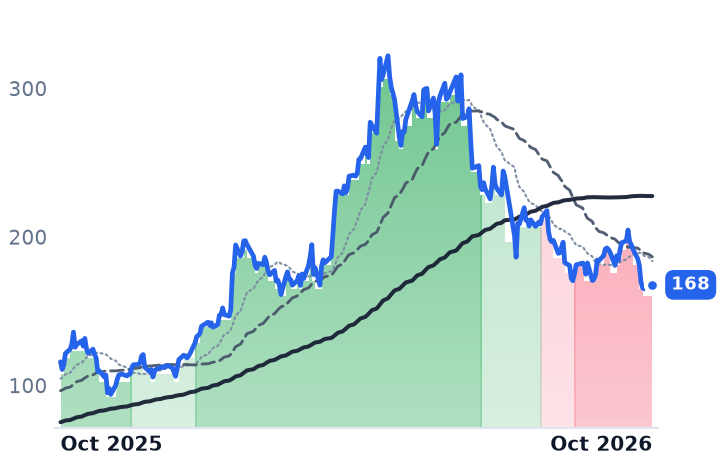
Powell Industries, the Houston builder of custom switchgear and modular "E-House" substation packages for refineries, liquefied natural gas terminals, utilities and data centers, has given back a quarter of its value since July without reporting a single new order. What it reported in August was a record.
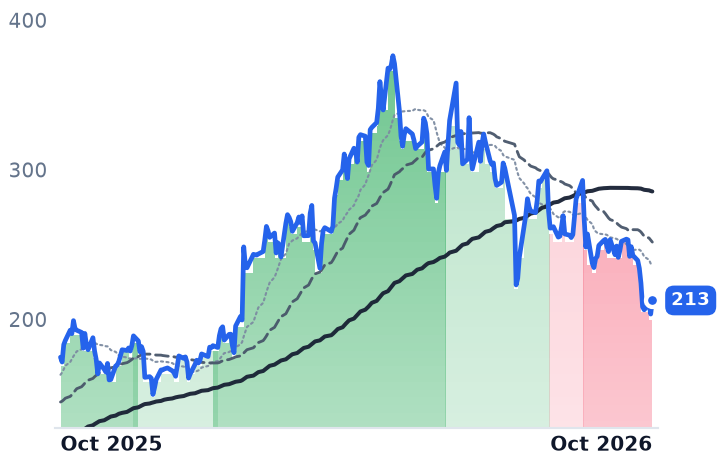
The October slide across power-equipment shares has been read as the moment switchgear scarcity pricing cracks. The calendar argues against that. September consumer prices rose 3.7% against 3.6% expected and producer prices jumped 6.3% annually, the largest annual gain since March 2022, with Fed officials signalling another hike; Treasuries slumped on 14 October as the S&P 500 fell 1.11%. What moved was the price of money, and it moved at the customer rather than in the supplier's price list.
The shelf sorted itself by who borrows
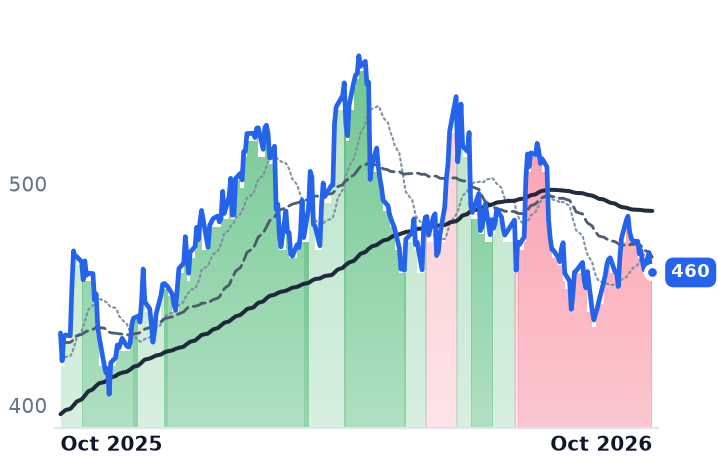
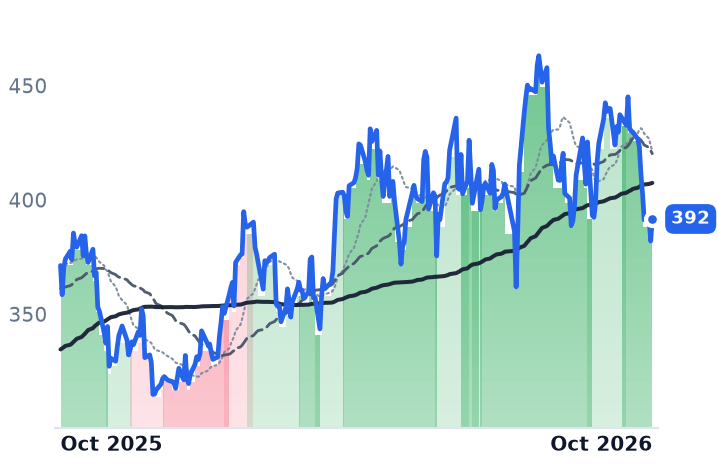
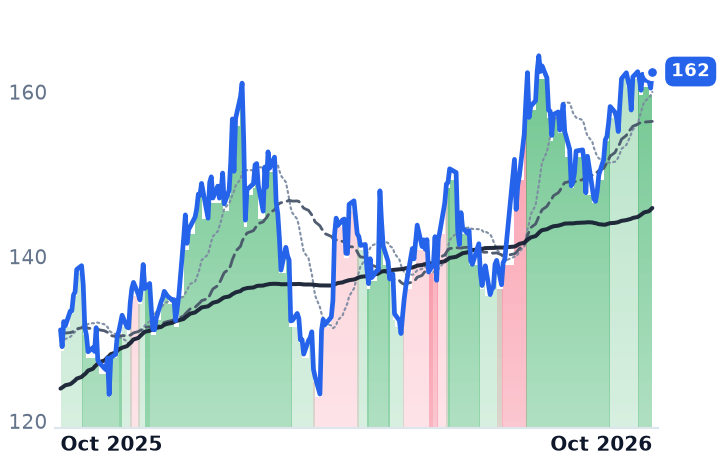
Over the 22 sessions to 21 October, Vertiv, which sells data-center power and cooling systems, fell 16.1%; Powell fell 12.6%; nVent, which makes electrical enclosures and connections, fell 11.6%; and Eaton, the largest listed power-management supplier, fell 11.5%. Diversified industrials went the other way, with Emerson up 5.4% and Ametek up 1.5%. Hubbell, the Shelton, Connecticut maker of utility distribution and substation products and of wiring and lighting, was flat at +0.3%.
The stress is visible where the buildout is funded. CoreWeave fell 15.5% on 14 October as its bond yields surged, and listings for a Blackstone-backed AirTrunk real-estate trust, Nvidia-backed Firmus and SoftBank-backed SB Energy were pulled or paused.
Powell's last number was two months old and the biggest it has printed
In the June quarter Powell booked $934m of new orders, up 158%, for a book-to-bill of 3.0x in the quarter and 2.2x for the fiscal year to date. Backlog reached nearly $2.4bn, against $1.4bn at the end of September 2025. Three mega orders did it: a data-center award above $400m, a $75m petrochemical order for a fertiliser plant, and roughly $60m of liquefaction work on the Gulf Coast.
"Commercial momentum across our key end markets continues to accelerate as Powell was awarded a record $934 million of new orders in the quarter," chairman and chief executive Brett Cope said on the 4 August call, where he also described the backlog passing $2bn for the first time in the company's 79-year history.
The mix inside that book has turned toward the buyers whose financing just got dearer. Commercial and other industrial work rose from 29% of backlog at the end of March to 40% at the end of June, while oil and gas excluding petrochemicals fell from 29% to 24%. Pricing has not normalized either: gross margin widened through fiscal 2026, from 28.4% to 29.6% to 30.6%. Powell is spending against the constraint, adding 335,000 square feet at Jacintoport that management said could support well above $100m of incremental annualized revenue.
It was not a clean quarter. Earnings of $1.42 a share missed the $1.49 consensus on revenue of $311.7m against $316.7m expected. But revenue growth accelerated across the year to 8.9%, and the shares now cost 24.7x forward earnings against 32.4x trailing, and against 49.2x trailing in May, on consensus fiscal 2027 earnings of $6.88 a share, up 27.8%.
Lead times that have not shortened
The supply relief that would end scarcity pricing is not in the quotes. In 2026, 15kV medium-voltage switchgear still quotes 52 to 80 weeks, 38kV equipment reaches 104 weeks, and power and substation transformers run beyond 160 weeks, two to four times pre-pandemic norms. New plants are years out: Hitachi Energy's $528m Mississippi transformer works is scheduled to start production in 2029. Eaton's June-quarter backlog was up 33% year on year with an Americas book-to-bill of 1.3.
Why Hubbell sat still
Hubbell's June quarter gives the mechanism its test. Utility Solutions sales rose 10% to $1,026m on 5.5% organic growth, while Electrical Solutions rose 25% to $686m on 18.3% organic growth led by data centers, where sales rose about 65%. On those figures, derived, utility products were roughly 60% of group sales, and utility capex is recovered through rates rather than raised in credit markets. The faster leg is the one giving back margin: Electrical Solutions' adjusted operating margin fell to 21.2% from 22.5%.
"Strong first half order trends provide visibility to our second half outlook," chairman and chief executive Gerben Bakker said on 28 July, as Hubbell raised full-year guidance to 16-18% sales growth and $20.25 to $20.55 of adjusted earnings per share. Reported net income still fell 1.6%, the interest cost of a $3.0bn acquisition closed in June rather than a demand problem. At 22.5x forward earnings against 27.2x trailing, Hubbell is cheaper than Powell on the forward line but carries roughly 12% consensus earnings growth to Powell's 27.8%.
So the business results account for none of October on the order line, and some of it on the valuation line: Powell's miss was real and its May multiple was extreme. What the month priced is the cost of capital behind a backlog that books work into fiscal 2028 and is increasingly owed by borrowers. Hubbell's position is the inverse, with slower growth bought at a steadier source of funding.
Hubbell reports on 27 October, the nearer test. Powell's next order number does not land until 8 December, which leaves seven weeks in which the only new information about the switchgear shortage will come from the bond market.