

Texas Pacific Land Set Royalty and Water Records in a Quarter That Missed on Revenue
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A West Texas landowner that drills nothing and operates almost nothing has lost a third of its market value since February while every meter inside the business improved. Texas Pacific Land's royalty production reached a record 39,700 barrels of oil equivalent a day in the June quarter, up 20% from a year earlier, produced-water royalty volumes hit a record, operating margin widened to 78.0%, and revenue growth has accelerated for four straight quarters to 31.2%. The reported revenue line still came in under consensus, and the shares fell 12.1% in two sessions.
With oil near $94 a barrel, the commodity does not explain the de-rating; what has been taken out is the un-contracted data-center land premium added in February. LandBridge, which owns the same basin's surface and almost none of its minerals, is up 60% over twelve months and is now priced against gross profit almost identically to the company with the royalty barrels.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
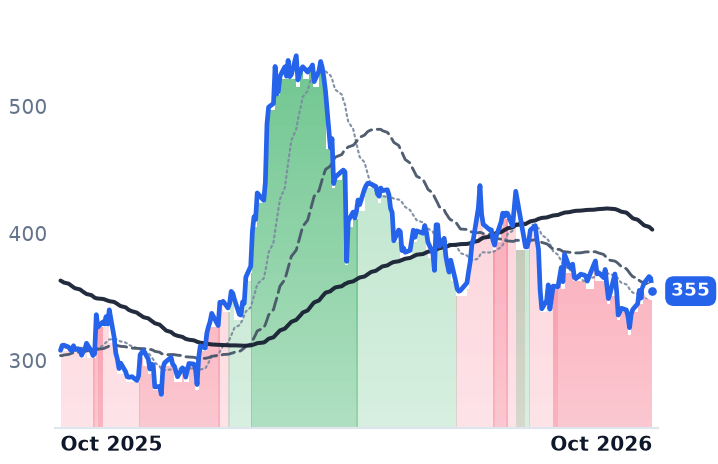
TPL | Texas Pacific Land | Royalty & Mineral Interests | 🔴 Cont. Bear | −4.6% | +15.1% |
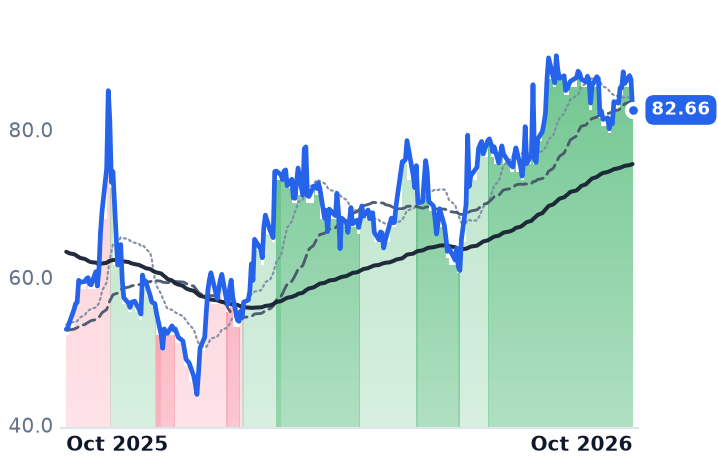
LB | LandBridge Company LLC | Production Infrastructure | 🟢 Cont. Bull | −5.2% | +56.1% |
| Compared against · context, not the story | |||||
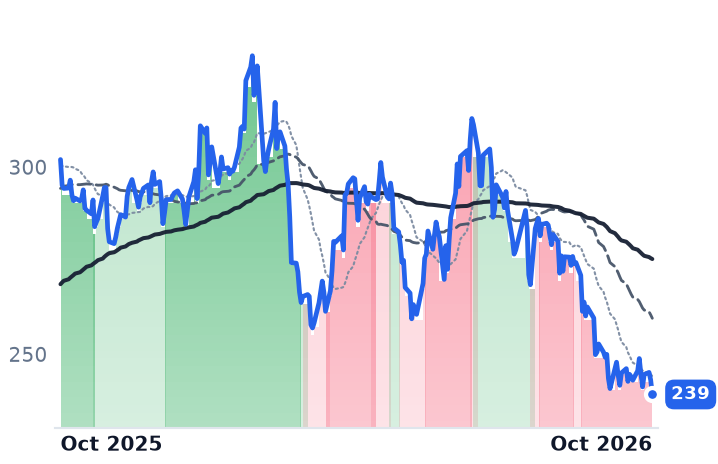
VMC | Vulcan Materials | Aggregates & Concrete | ⚠️ Emerging Bear | −4.0% | −20.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TPL | $24.5B | 45.2x | 38.1x | 27.2x | 24.2x | 31.8x | 28.2x | 31.5x | 2.2% |
LB | $6.4B | 36.6x | 44.6x | 28.3x | 25.1x | 30.6x | 27.2x | 46.1x | 2.7% |
VMC | $31.3B | 28.4x | 27.0x | 3.9x | 3.9x | 14.1x | 14.1x | 14.1x | 3.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TPL | Revenue | +27.2% | +12.0% | +8.4% |
| EPS | +33.3% | +11.0% | −100.0% | |
LB | Revenue | +73.3% | +30.5% | +24.1% |
| EPS | +37.6% | +32.5% | +26.4% | |
VMC | Revenue | +1.9% | +5.4% | +6.1% |
| EPS | +6.4% | +15.7% | +14.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Texas Pacific Land owns roughly 880,000 acres of West Texas surface and a perpetual, cost-free royalty on much of the oil and gas produced beneath it. In August the company reported the best quarter in its history on every operating measure it discloses, and the shares fell 12.1% across the two sessions that followed.
The gap was in the top line. Revenue of $246.1m came in under a consensus near $255.5m because water-services revenue slipped and a land-sale gain that had lifted the prior quarter did not repeat. Underneath it, net income was $153.9m, free cash flow $155.5m, and royalty production averaged a record 39,700 barrels of oil equivalent a day, up 20% from a year earlier.
The de-rating is longer than one print. From a $531.95 close on 24 February the stock reached $354.57 on 14 October, a third lower, and it has been in a downtrend since mid-August. February's run — 85% in under two months from the end of 2025 — followed the company's $50m commitment to Bolt Data & Energy, co-founded by former Google chief executive Eric Schmidt, for which it took equity, warrants, the right to supply land, and first refusal on water for Bolt's data centers; KeyBanc initiated at Overweight with a $1,050 target. What the past eight months have removed is that un-contracted land option, while the royalty business accelerated beneath it.
Three unlike dollars in one line
The revenue line cannot settle the question because three different businesses report into it. The royalty is a fractional interest — about 85,000 acres at a 1/128th rate and 371,000 acres at 1/16th — with no vote over when a well gets completed. Water is a separate dollar: brackish sales ran 663,000 barrels a day in the quarter, down 19% sequentially but up 38% year on year, and produced-water royalties on disposal volumes reached a record 4.9m barrels a day, generating $37.1m. Across the first half, water was $165.5m against $317.4m of land and resource revenue.
The contracted land dollar barely registers at all. Easements and surface income doubled to $5.4m. The June agreement to supply land and water to Chevron's Project Kilby, a 2.67 GW gas plant in Reeves County built with Microsoft, carries aggregate consideration of $42.5m — a nominal cash payment plus annual payments running through 2046. A twenty-year annuity is close to invisible in any single quarter.
Fewer rigs, more barrels
The obvious volume worry does not hold either. The Permian rig count was 242 on 30 January, down 20% from 303 a year earlier, and Texas permit applications fell to 570 in April, the fewest since February 2021. Royalty production on Texas Pacific Land's acreage rose 20% anyway. Nor is this the oil tape: WTI traded near $94 a barrel on 14 October after strikes on Saudi facilities and tankers in Hormuz. "Our unhedged royalty position allowed us to benefit fully from the strong oil price environment," chief executive Tyler Glover said on the 6 August call.
The same dirt, bought at a different price
LandBridge, which manages over 325,000 surface acres in and around the Delaware Basin and holds only a small royalty collection, reported the same day and rose 6.0% the next session. Its quarter: revenue $66.8m, up 41%, with surface-use royalties and revenue of $52.2m against $34.2m a year earlier — 78% of the top line, driven mainly by produced-water handling volumes. Free cash flow of $40.2m grew 11%. Growth is partly bought: full-year 2025 revenue of $199.1m was up 81%, and the company agreed to pay $20m for 560 acres under a Lea County landfill. Five Point's holding vehicle still controls about 63.1% of the vote after a November secondary at $71.00, and a Class A reporting change makes its own earnings-per-share series non-comparable quarter to quarter.
Both run near-pure land margins, 88.5% gross at Texas Pacific Land and 96.3% at LandBridge, so price against gross profit is the comparison that survives the structural differences: 31.8x and 30.6x trailing. The quarry operator Vulcan Materials sits at 14.1x. Eight months of trading have brought the royalty owner and the surface owner to the same price for a dollar of land profit, having taken it from the one that collects barrels and given it to the one that does not.
That is where the results stop explaining the move. Earnings grew while the trailing multiple fell from 61.8x in early May to 45.2x, and market value from $29.7bn to $24.5bn; consensus still carries $1,010m of 2026 revenue and $9.30 of earnings per share. A business compounding at 31% with zero debt, $247.6m of cash and a 12.5% dividend increase is not the thing being marked down. The asset being marked down is a gigawatt pipeline no one has signed — and LandBridge's version of it, a long-term option on up to 3,400 Reeves County acres with PowerBridge, is being paid for in full.
Glover told investors on 6 August: "I would be disappointed if we don't announce at least one or more major definitive agreements in the near term." The acreage either converts into signed leases or it goes back to being what it has been since 1888 — ground other people's capital pays to cross.