

Evercore's Record First Half Was Paid on Deals Signed Before Global Dealmaking Stalled
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
An independent adviser collects almost nothing when a merger is signed and nearly everything when it closes, so the fee line reports the past and the de-rating is a bet on the closing calendar. Evercore's June-quarter advisory fees rose 11% year on year, with year-to-date advisory fees up 61%, and its compensation ratio improved to 64.8% from 65.8% — the opposite of a firm whose hiring outran its revenue. Moelis's revenue rose 12% with an announced pipeline up more than 80%.
Then announced global M&A fell 41% in the third quarter to $993bn, the first quarter under $1tn since mid-2025. Evercore and Moelis have de-rated into 13.3x and 18.2x trailing earnings against roughly 23x each a year ago. Lazard is the exception: its advisory revenue actually fell 9%, and asset management carried the half.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
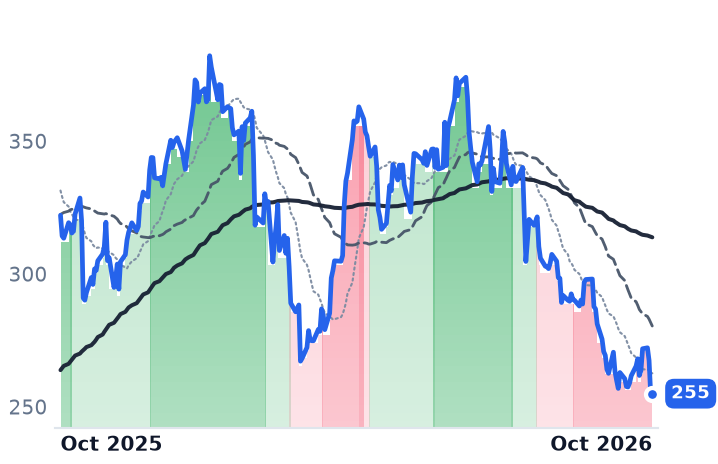
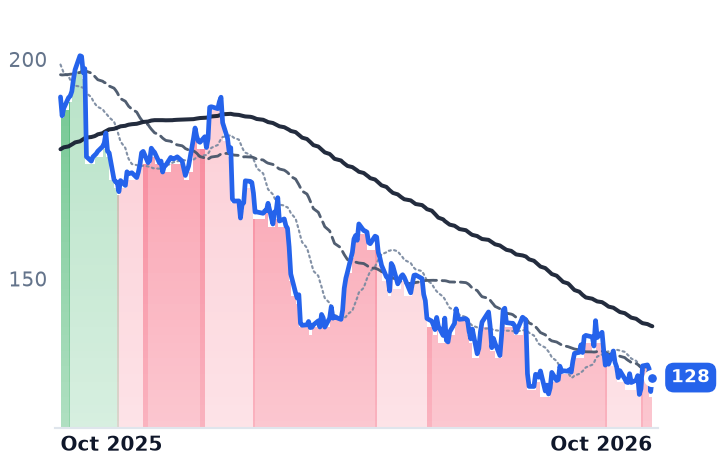
EVR | Evercore | Investment Banking | ⚠️ Emerging Bear | −5.9% | −20.8% |
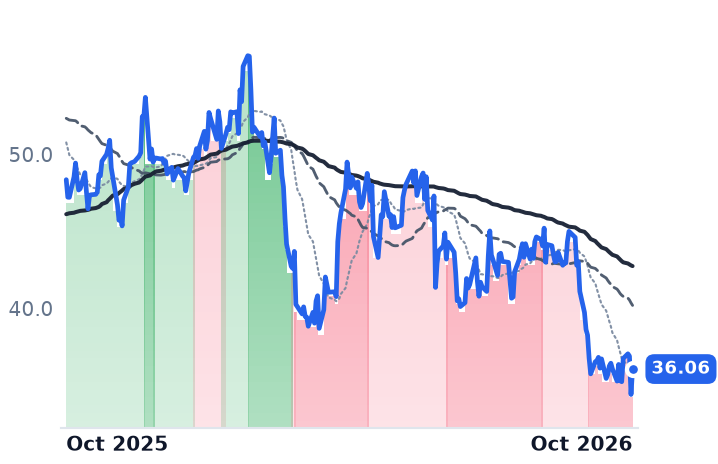
LAZ | Lazard | Investment Banking | 🔴 Cont. Bear | −6.7% | −25.4% |
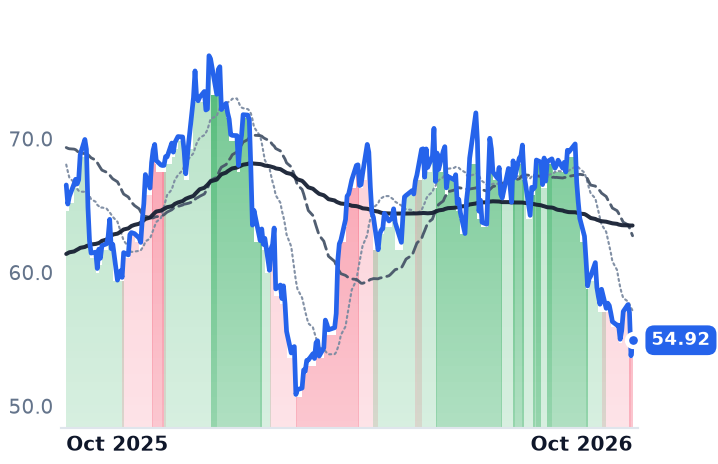
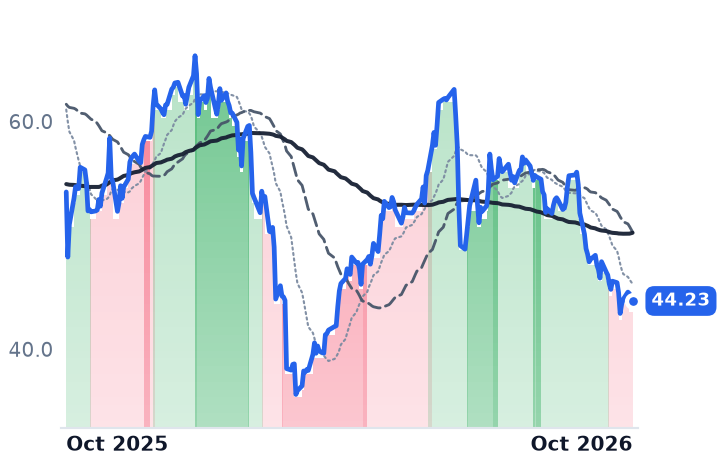
MC | Moelis | Investment Banking | ⚠️ Emerging Bear | −9.9% | −17.5% |
| Compared against · context, not the story | |||||
PJT | PJT Partners | M&A & Restructuring Advisory | 🌱 Emerging Bull | −12.7% | −22.8% |
HLI | Houlihan Lokey | M&A & Restructuring Advisory | 🔴 Cont. Bear | −4.7% | −33.4% |
JEF | Jefferies Financial | Investment Banking | 🌱 Emerging Bull | −9.4% | −17.8% |
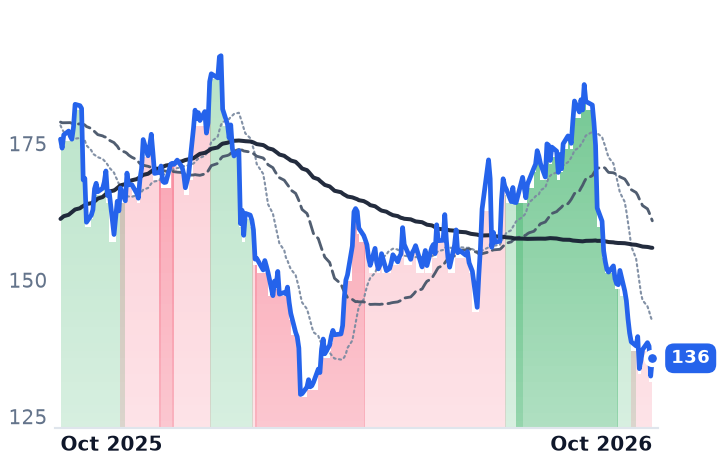
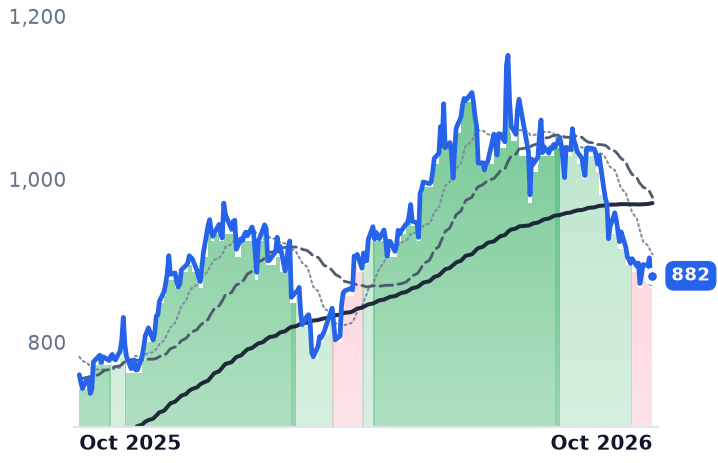
GS | The Goldman Sachs | Investment Banking | 🟢 Cont. Bull | −9.7% | +16.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EVR | $9.9B | 13.3x | 14.2x | 2.1x | 2.1x | 2.1x | 2.2x | 9.2x | 16.5% |
LAZ | $4.1B | 15.9x | 17.7x | 1.2x | 1.2x | 2.6x | 2.6x | 12.5x | 17.2% |
MC | $4.1B | 18.2x | 18.3x | 2.6x | 2.4x | 3.7x | 3.4x | 13.2x | 10.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PJT | $4.1B | 17.9x | 20.1x | 2.2x | 2.1x | 3.4x | 3.2x | 10.0x | 16.1% |
HLI | $9.1B | 21.4x | 18.8x | 3.6x | 3.5x | 7.1x | 6.8x | 14.9x | 5.3% |
JEF | $8.3B | 11.2x | 12.0x | 0.7x | 1.0x | 1.0x | 1.3x | 7.3x | 50.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GS | $306.6B | 15.8x | 14.9x | 2.6x | 4.3x | 4.5x | 7.5x | 27.4x | -13.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EVR | Revenue | +25.1% | +14.6% | +5.8% |
| EPS | +34.6% | +17.3% | +10.2% | |
LAZ | Revenue | +12.3% | +17.8% | +6.2% |
| EPS | −12.9% | +74.8% | +17.4% | |
MC | Revenue | +14.9% | +17.4% | +7.2% |
| EPS | +9.7% | +28.3% | +5.1% | |
PJT | Revenue | +14.4% | +10.6% | +4.4% |
| EPS | +18.2% | +13.4% | +10.4% | |
HLI | Revenue | +13.2% | −1.2% | +18.7% |
| EPS | +28.7% | −9.9% | +25.2% | |
JEF | Revenue | +17.3% | +8.8% | +7.2% |
| EPS | +24.9% | +27.7% | +15.6% | |
GS | Revenue | +20.6% | +2.7% | +1.8% |
| EPS | +42.8% | +4.7% | +5.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
An independent adviser's revenue line cannot say whether the merger cycle got better or worse, because the money lands on the day a transaction closes. Evercore, which sells strategic advice on mergers, defenses, restructurings and capital raising and runs a smaller wealth and asset-management arm, reported record first-half net revenues of $2.4bn, up 56%. Those fees belong to a deal book assembled earlier. The quarter that followed is the one the market is now pricing.
Global M&A announced in the third quarter totaled $993bn, down 41% from the prior quarter and the first sub-$1tn quarter since the second quarter of 2025, with only 10 deals above $10bn, as rising borrowing costs stalled buyers. Year to date, worldwide volume is still up 28% at $3.9tn. The advisory shelf was read through the summer as proof the cycle was intact, because reported fees kept setting records. Those records are a closing calendar, and the calendar that fills 2027 stopped growing in a single quarter.
The clearest proof is in a bank that barely does advisory
Goldman Sachs's advisory revenues set an all-time quarterly record of $1.654bn on closing more deals in that same September quarter. Advisory was 8.9% of its $18.68bn of third-quarter net revenues, a side business at a trading and financing house; what carries here is the direction. A fee line based on completions hit a record while the activity measure based on announcements fell by two-fifths.
Evercore hired ahead of its fees and still paid out less
Evercore's second-quarter advisory fees rose $77.9m, or 11%, year on year, with year-to-date advisory fees up 61%, on record quarterly revenue of $1.0bn. Compensation, the expense a firm sets after it already knows its revenue, took 64.8% of net revenues against 65.8% a year earlier. Adjusted non-compensation expenses ran at a 17.5% ratio in the quarter, leaving roughly 18 points of operating margin.
Capacity is a headcount. Investment-banking senior managing directors rose to 188 at June 30 from 159 a year earlier; dividing first-half net revenues by those counts gives $12.76m a head against $9.67m. Nineteen new senior managing directors joined year to date and more than 50 are still ramping their practices, with guaranteed pay landing before their fees do.
"The timing of backlog conversion into revenue can vary from quarter-to-quarter, and it is best to evaluate our business on a longer-term basis," chairman and chief executive John Weinberg said on the July 29 call, with backlogs described as near-record.
Moelis pays out more than it earned
Moelis & Company, a pure advisory firm with no asset management and no balance sheet, grew June-quarter revenue 12% to $409.4m and cut its compensation ratio to 65.8% from 69.0%. Its announced pipeline was up more than 80% year on year, a record total pipeline, with liability management dominating activity as lenders turn selective. The $0.65 quarterly dividend exceeds the $1.10 of first-half GAAP diluted earnings against $1.30 declared, so an interrupted closing calendar hits the distribution, not a securities book.
Lazard's advisory fell while its fee on assets did not
Lazard, which pairs advisory with an asset manager, is the one name where the de-rating matches the accounts. Financial Advisory net revenue fell 9% to $450m in the quarter it achieved its strongest announced league-table position since 2014, while Asset Management revenue rose 20% on average assets under management of $279bn, up 17%, with the best first-half net inflows in nearly two decades. Consolidated operating margin fell to 4.5% from 11.5%. Lazard trades at 15.9x trailing earnings but 17.7x forward, because consensus for this year, $2.05 a share, sits below last year's actual $2.17.
So one of the three sets of accounts explains its own share price.
What the markdown is actually underwriting
Evercore has fallen 27.9% over three months, Moelis 21.6% and Lazard 19.9%, alongside PJT's 19.5%, Jefferies' 22.6% and Houlihan Lokey's 10.8%; Evercore left its uptrend in mid-July and Moelis only in mid-September, while Lazard was already weak in June. Over twelve months Goldman is up 15.3% and Morgan Stanley 18.3%, and the advisory-pure names all lost ground. On October 14 both boutiques fell about 4% after bank commentary on rate uncertainty dampening client activity, with no company news attached.
The reported results explain none of the Evercore and Moelis declines and most of Lazard's. Evercore sits at 13.3x trailing earnings and a 16.5% free-cash yield against roughly 23x on last year's earnings a year ago; Moelis at 18.2x from roughly 23x. Both carry forward multiples at or above trailing, meaning consensus already assumes earnings stop rising. What the price is paying for is the conversion rate: how much of a record announced book survives financing costs to reach a closing date. Credit itself is not signalling trouble, with high-yield spreads around 3.16% in mid-October, which is why restructuring here is a retainer business rather than a boom.
Lazard reports on October 22, Evercore and Moelis on October 28. Those are the first statements that contain the quarter in which the signing stopped, and a fee recognized at closing will take longer than one print to tell anyone whether it mattered.