

Rocket Lab Now Earns Four-Fifths of Its Revenue From Satellite Hardware, Not Launch
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Shareholders in the two listed rocket companies are paying for launch, and launch is where almost none of the revenue comes from. Rocket Lab's Space Systems segment billed $189.5m of a record $234.1m in the June quarter, while Launch Services billed $44.6m, down 30% sequentially even though six Electrons flew. At Firefly, spacecraft and defense software were 92% of $117.7m.
The October decline traces to the launch side anyway: Neutron's first flight slipped into 2027 on a carbon-composite dome defect, disclosed on 14 October, and Rocket Lab still trades at 35.7x forward sales after issuing 29.3m shares to fund its Iridium purchase. Firefly fell nearly as hard the same day with no company news, at roughly a third of Rocket Lab's forward price-to-gross-profit.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
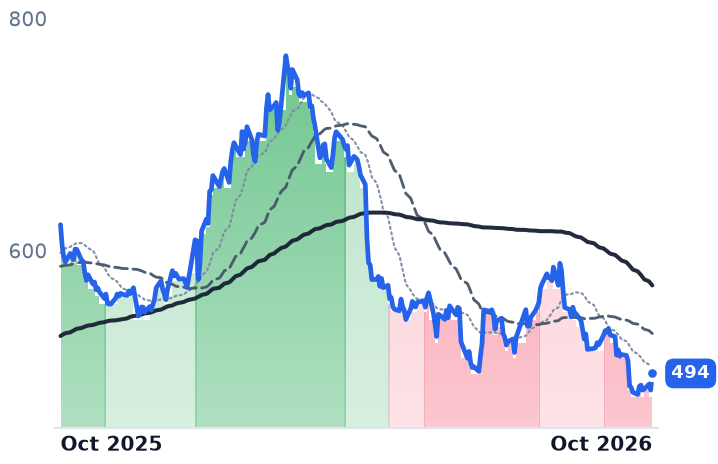
RKLB | Rocket Lab USA | Unmanned Systems & ISR | ⚠️ Emerging Bear | −3.2% | −11.0% |
FLY | Firefly Aerospace | Space Systems & Launch | 🔴 Cont. Bear | −19.4% | −42.8% |
| Compared against · context, not the story | |||||
ASTS | AST SpaceMobile | Satellite & Broadband Services | 🔴 Cont. Bear | −28.7% | −54.7% |
PL | Planet Labs PBC | Unmanned Systems & ISR | 🔴 Cont. Bear | −11.5% | −3.0% |
LUNR | Intuitive Machines | Space Systems & Launch | 🔴 Cont. Bear | −18.8% | −18.6% |
MNTS | Momentus | Aerospace & Defense | 🔴 Cont. Bear | −30.3% | −90.8% |
KTOS | Kratos Defense & Security Solutions | Missiles, Weapons & Fire Control | 🔴 Cont. Bear | −16.1% | −58.1% |
LMT | Lockheed Martin | Large Diversified Primes | 🔴 Cont. Bear | −1.9% | +4.1% |
NOC | Northrop Grumman | Large Diversified Primes | 🔴 Cont. Bear | −6.3% | −20.6% |
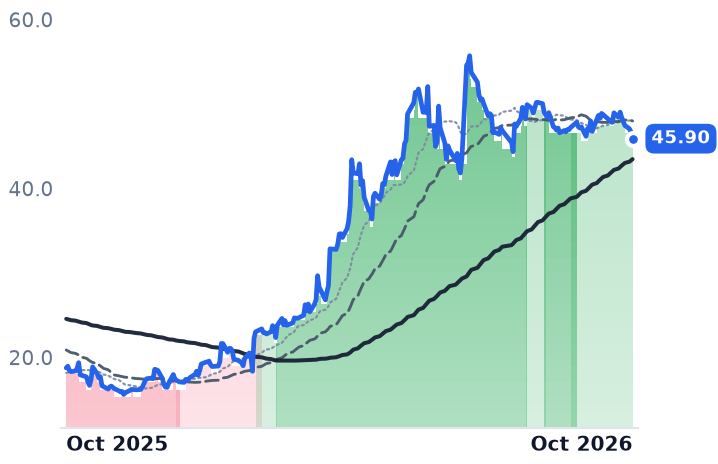
IRDM | Iridium Communications | Specialty & Small Carriers | 🟢 Cont. Bull | −0.6% | +144.6% |
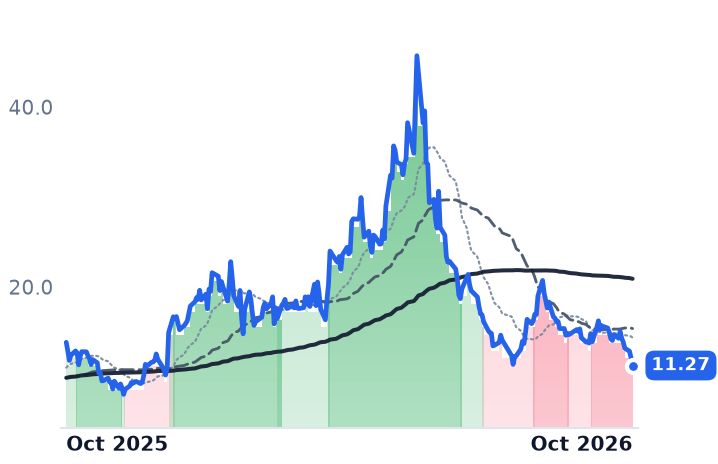
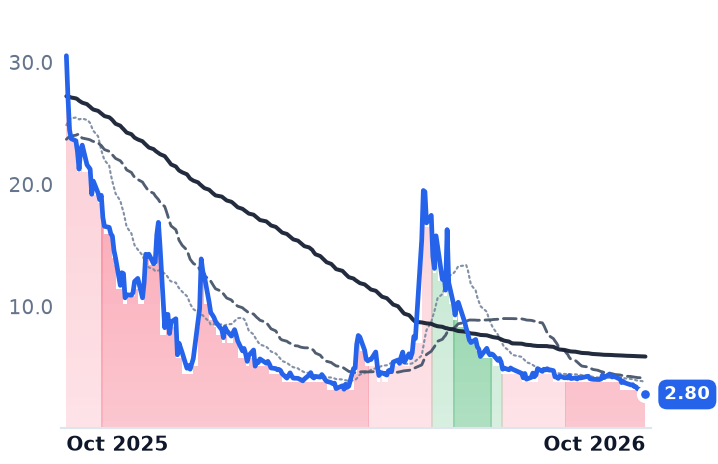
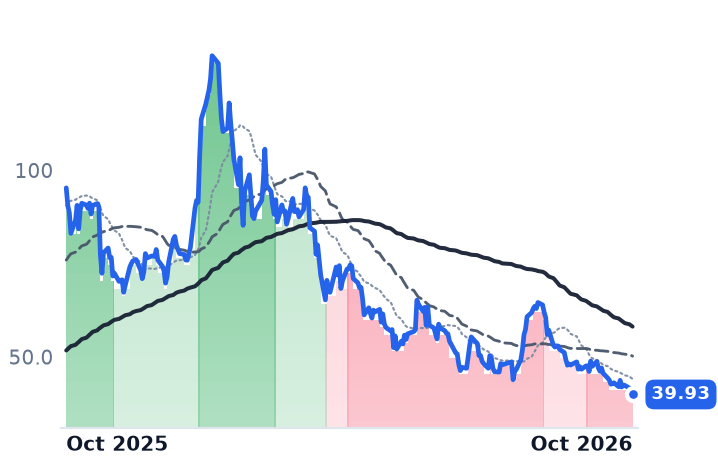
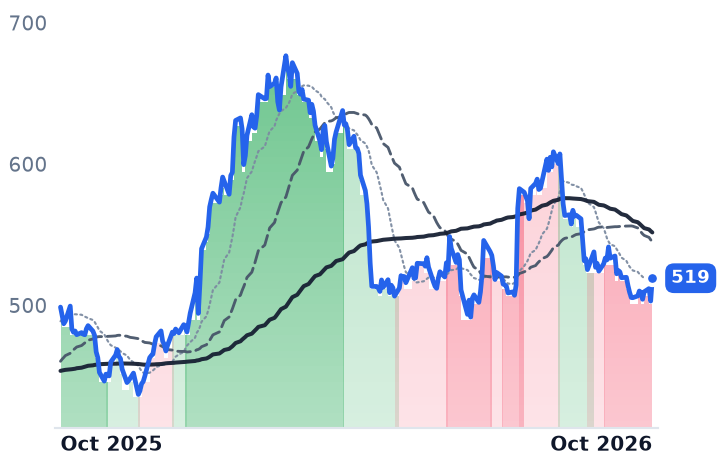
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RKLB | $34.3B | n/m | — | 44.5x | 35.7x | 119.5x | 95.8x | n/m | -1.1% |
FLY | $2.8B | n/m | — | 9.9x | 6.5x | 51.5x | 33.7x | n/m | -11.5% |
ASTS | $23.7B | n/m | — | 205.7x | 147.8x | — | — | n/m | -6.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PL | $5.8B | n/m | — | 15.4x | 13.3x | 27.8x | 24.0x | n/m | 0.4% |
LUNR | $2.3B | n/m | — | 4.7x | 2.5x | 17.1x | 9.1x | n/m | -8.3% |
MNTS | $31.9M | n/m | — | 8.0x | 0.2x | 12.2x | 0.3x | n/m | -78.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KTOS | $9.8B | 302.5x | 62.0x | 6.4x | 5.5x | 29.1x | 24.8x | 71.8x | -1.3% |
LMT | $119.0B | 24.8x | 17.2x | 1.6x | 1.5x | 16.1x | 15.3x | 17.0x | 4.8% |
NOC | $76.8B | 16.8x | 19.3x | 1.8x | 1.7x | 8.8x | 8.5x | 12.2x | 4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IRDM | $5.1B | 54.8x | 50.7x | 5.8x | 5.5x | 8.2x | 7.9x | 15.8x | 5.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RKLB | Revenue | +59.9% | +45.4% | +32.6% |
| EPS | −27.9% | −91.6% | −1346.5% | |
FLY | Revenue | +184.8% | +55.9% | +56.9% |
| EPS | −26.5% | −23.6% | −56.0% | |
ASTS | Revenue | +174.7% | +344.1% | +146.7% |
| EPS | +98.2% | −45.8% | −119.7% | |
PL | Revenue | +21.9% | +46.7% | +30.2% |
| EPS | −55.9% | −40.8% | −129.2% | |
LUNR | Revenue | +322.6% | +23.3% | +21.2% |
| EPS | +69.3% | −67.8% | −152.9% | |
MNTS | Revenue | +1970.0% | — | — |
| EPS | +139.6% | — | — | |
KTOS | Revenue | +34.7% | +23.3% | +21.7% |
| EPS | +57.7% | +34.4% | +28.7% | |
LMT | Revenue | +6.1% | +5.4% | +5.5% |
| EPS | +38.4% | +7.1% | +6.2% | |
NOC | Revenue | +5.1% | +6.7% | +6.1% |
| EPS | +7.2% | +7.9% | +8.6% | |
IRDM | Revenue | +5.0% | +5.2% | +5.2% |
| EPS | −11.2% | +41.7% | +7.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Six Electrons flew and the launch bill got smaller
Rocket Lab flew six Electron rockets in the quarter ended 30 June and billed less for launch than it had three months earlier. Launch Services recorded $44.6m, a 30% sequential decline, against $189.5m from Space Systems — solar cells, reaction wheels, satellite platforms and separation systems sold to prime contractors and government programs — out of record revenue of $234.1m. Two of the six were HASTE suborbital hypersonic-target missions, and the company's quarterly filing attributes the decline to revenue recognized over time and already booked in earlier periods. Flight rate itself is rising: the 16th Electron of 2026 went up on 11 September, against 21 in all of 2025.
So the segment that names the business was 19% of its sales, and group revenue grew 62% year on year with gross margin at 36.1% against 32.1% a year earlier. What the share price has been paying for is the part that bills almost nothing: Neutron, the 8-ton-class medium-lift vehicle built to contest the roughly $10bn market Falcon 9 holds. On 14 October Rocket Lab disclosed that Neutron's inaugural flight slips from the fourth quarter into 2027 after inspections found voids in a newly cured carbon-composite forward propellant dome. The shares fell 7.85% that session.
"They don't necessarily mean that the dome would fail on flight, but our practice is to proceed only when we believe the system has the appropriate margins. Possible success isn't our standard," chief executive Peter Beck said in a video update on 14 October. It is the vehicle's third public slip: to late 2026 in February after a January tank failure, then an August recasting of the Q4 commitment as reaching the pad.
Firefly's revenue arrives when a milestone is certified
Firefly Aerospace, which sells the Alpha small-lift rocket, the Blue Ghost lunar lander, Elytra servicing vehicles and the SciTec defense-software line, is the same shape in sharper relief. Spacecraft Solutions produced $108.3m of Q2 revenue of $117.7m, leaving roughly $9.4m from selling rides. Chief financial officer Darren Ma told the 11 August call that most contracts, particularly on the spacecraft side, are milestone-driven and release cash as progress is made — which is why gross margin swings with cost incurred, falling to 20.3% from 25.7% a year earlier.
Alpha has flown once in eighteen months, returning to flight on 11 March 2026 with a Lockheed Martin demonstrator after a 2025 in-flight breakup and a destroyed ground-test stage. The Block 2 debut was pushed to the fourth quarter, and medium-lift Eclipse is now no earlier than 2027. Backlog is a record $1.5bn, from $1.3bn a quarter earlier, and liquidity of $940.3m covers about eight quarters at a free-cash outflow that widened to $106.3m.
How much of the fall the businesses explain
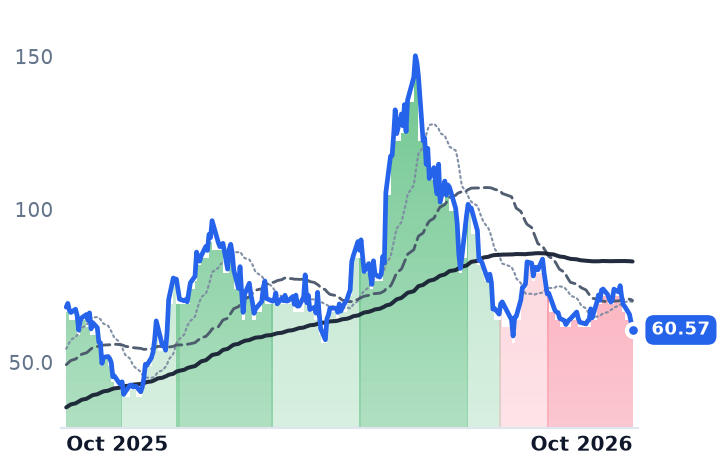
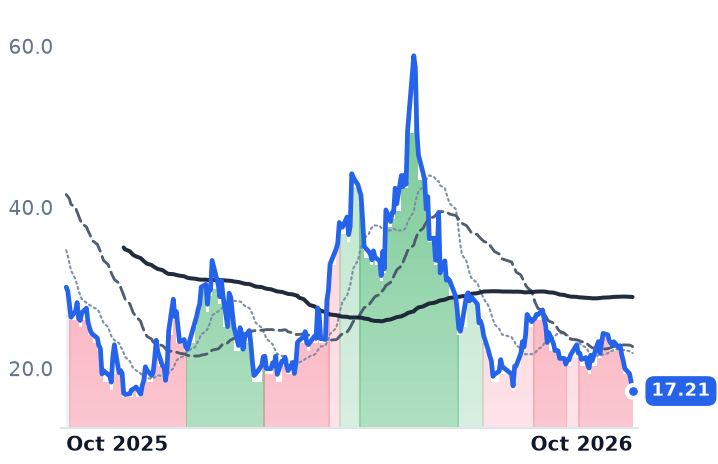
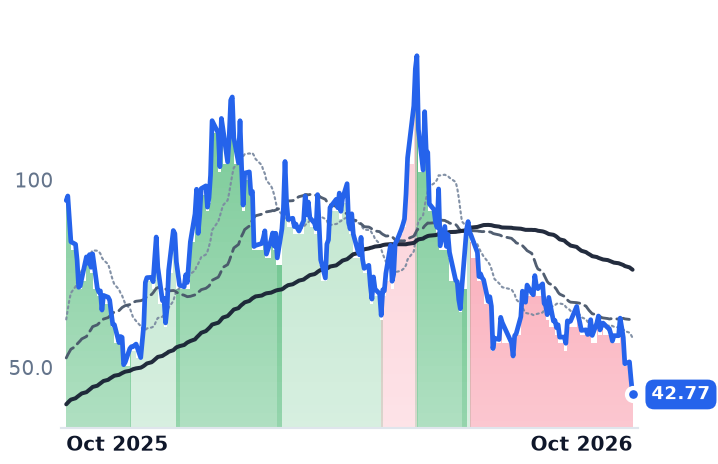
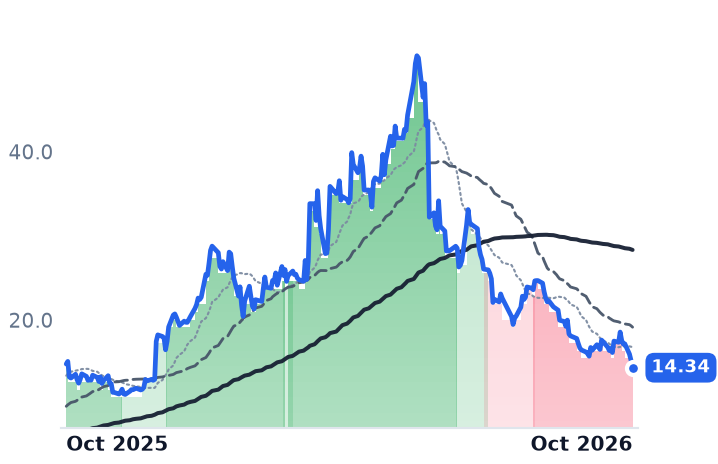
Rocket Lab's reported results argue against the decline; its one unbilled asset argues for it. Both names broke down in July, long before the 8-K, and the complex fell with them — Planet Labs 43.9% and AST SpaceMobile 37.9% over three months against Rocket Lab's 23.1% — while Lockheed Martin rose 0.8%. The anchor itself moved: SpaceX closed its 11 June debut at $161.11 above $2tn, then gave back roughly $1.2tn from its peak after an August lock-up expiry, removing the reason to own a proxy.
At Rocket Lab the de-rating is doing rational work. Trailing price-to-sales of 44.5x compares with 75.5x in early May, and the 35.7x forward figure still prices consensus revenue of $959m this year with no positive net income expected before 2028 — against 629.7m diluted shares, up 22% in a year, plus the 29.3m issued in a $1.944bn program to fund the $8bn Iridium purchase. Third-quarter gross margin is guided to 29–31%.
Firefly's case is thinner and cheaper. Its 51.5x trailing price-to-gross-profit compares with 110x in mid-May, and at 33.7x forward it sits near a third of Rocket Lab's 95.8x on faster growth — with its margin sixteen points lower, gross profit is the only fair cross-read. Nothing company-specific landed on the day it fell 7.2% beyond a 10 November earnings date, and its SciTec unit expanded an Air Force contract on 8 October. The likelier reading is sector sympathy and burn.
Beck described Neutron's first-stage tank as the largest pressurized structure ever built from carbon composite, too large for an autoclave, forcing new curing processes — the three-step remediation finishes in the first quarter of 2027, and only then does a launch date come back. Until it does, both companies are judged on the one thing neither sells much of.