

Salesforce Booked 14% More Future Revenue and No More Operating Profit Than a Year Ago
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Salesforce's forward order book improved last quarter while its profit engine stood still, and that combination is what the August re-rating has been asked to carry. Contracted revenue due within a year reached $33.5bn, up 14% in constant currency and faster than the prior quarter, against reported revenue growth of 10.8%.
The income statement tells the other half: GAAP operating income was flat year on year, margin slipping to 20.5% from 22.8%, with reported earnings per share lifted by a 14.7% cut in the diluted share count. Agentforce passed $1.5bn of annual recurring revenue but is roughly 3% of guided group revenue, too small to move a ratably recognized seat book.
The same bargain shows up one layer down at Twilio and Braze, where winning consumption volume costs gross margin. Salesforce, Twilio and Braze are now moving in three different directions.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
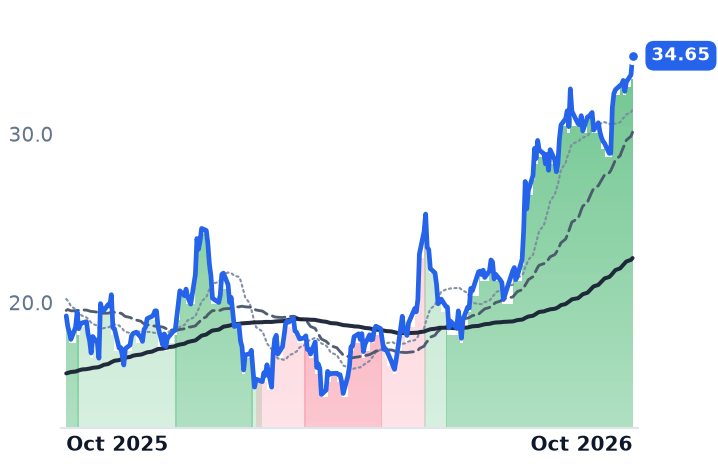
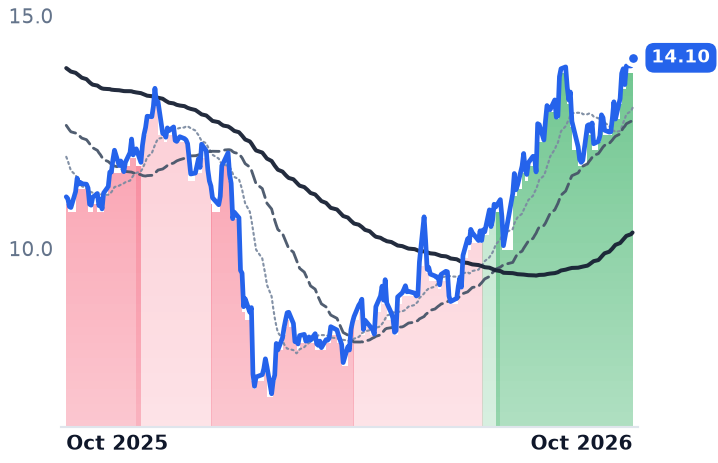
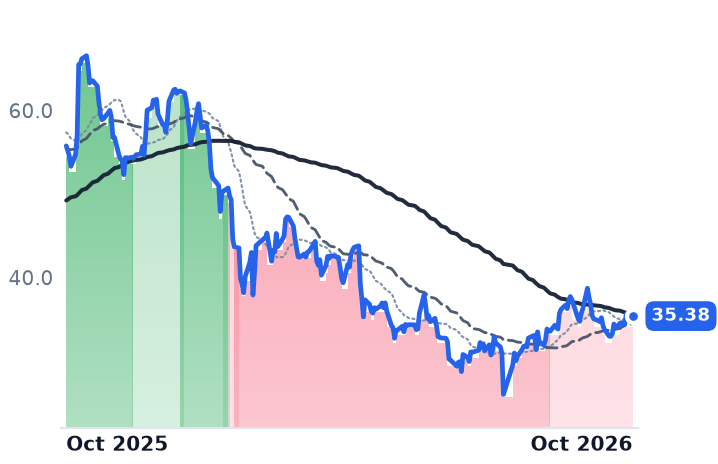
CRM | Salesforce | Customer Experience & CRM | 🌱 Emerging Bull | −7.9% | +0.3% |
TWLO | Twilio | Communications & Messaging Platforms | 🟢 Cont. Bull | +22.9% | +163.6% |
BRZE | Braze | Customer Experience & CRM | 🌱 Emerging Bull | +12.5% | +10.9% |
| Compared against · context, not the story | |||||
HUBS | HubSpot | Customer Experience & CRM | 🔴 Cont. Bear | −10.6% | −50.9% |
ZETA | Zeta Global | Marketing & Advertising Technology | 🟢 Cont. Bull | +11.7% | +80.3% |
FRSH | Freshworks | Security & Compliance | 🟢 Cont. Bull | +11.5% | +26.9% |
PEGA | Pegasystems | Low-Code & Process Automation | 🔴 Cont. Bear | −8.6% | −36.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRM | $195.9B | 21.7x | 14.3x | 4.5x | 4.2x | 5.8x | 5.5x | 13.7x | 7.7% |
TWLO | $43.2B | 37.9x | 48.0x | 7.8x | 7.2x | 16.0x | 14.8x | 130.0x | 2.6% |
BRZE | $3.2B | n/m | 44.8x | 3.9x | 3.6x | 5.9x | 5.4x | n/m | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HUBS | $11.5B | 79.1x | 16.8x | 3.3x | 3.1x | 4.0x | 3.7x | 32.3x | 6.7% |
ZETA | $8.4B | n/m | 34.4x | 5.3x | 4.6x | 8.7x | 7.5x | 109.4x | 2.7% |
FRSH | $3.8B | 21.2x | 20.8x | 4.3x | 4.0x | 5.0x | 4.7x | 47.3x | 6.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PEGA | $5.6B | 17.8x | 14.0x | 3.2x | 3.0x | 4.2x | 4.0x | 26.0x | 9.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CRM | Revenue | +9.3% | +11.5% | +9.9% |
| EPS | +17.4% | +42.3% | −4.1% | |
TWLO | Revenue | +19.6% | +11.5% | +10.6% |
| EPS | +23.6% | +14.4% | +14.5% | |
BRZE | Revenue | +24.3% | +24.7% | +17.2% |
| EPS | +281.2% | +52.5% | +51.9% | |
HUBS | Revenue | +18.3% | +14.0% | +13.7% |
| EPS | +38.4% | +26.9% | +20.3% | |
ZETA | Revenue | +41.1% | +16.0% | +14.5% |
| EPS | +47.6% | +23.7% | +19.4% | |
FRSH | Revenue | +15.6% | +14.2% | +15.4% |
| EPS | +5.4% | +24.0% | +18.4% | |
PEGA | Revenue | +7.4% | +8.5% | +8.4% |
| EPS | +16.1% | +7.7% | +11.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Salesforce's forward booking meter improved last quarter and its profit engine did not. The software company behind the sales, service and marketing clouds used by large enterprises disclosed current remaining performance obligation of $33.5bn as of 31 July, contracted revenue due within a year, up 14% and up 14% in constant currency, an acceleration from 13% in constant currency a quarter earlier. Reported revenue grew 10.8%, to $11.345bn.
That gap is the whole argument for owning the shares here: bookings outrunning a subscription book recognized ratably means demand arrives in revenue a year late. The August quarter was read as proof that grafting consumption pricing onto seat licenses has restarted growth. It has restarted the order book. What it has not done is produce operating leverage.
The order book moved; the income statement stood still
GAAP operating income was $2.331bn, flat against the year before, so operating margin fell to 20.5% from 22.8%. Net income rose 86.9% to $3.526bn while diluted shares fell 14.7% to 821m — reported earnings per share of $4.29 is the arithmetic of a $25bn accelerated repurchase and items below the operating line, not of a business converting growth into profit. Free cash flow did rise 81%, to $1.1bn.
The consumption lines are real and small. Agentforce annual recurring revenue passed $1.5bn, up more than 240%, with Agentforce and Data 360 together near $3.9bn. Against guided fiscal-2027 revenue of $46.1–46.4bn, the Agentforce line is roughly 3% of the company; Morgan Stanley put it at 2.6%. Subscription revenue of $10.8bn grew 12%, and included $440m from the Informatica acquisition. Attrition, excluding Slack self-service and recent acquisitions, held at about 8%.
The billing change is short-cycle rather than contractual: customers draw down Flex Credits and, as management described it, "when they want more, they raise their hand", while six of the quarter's top ten deals were unlimited enterprise license agreements. "As customer zero, we are putting Agentforce to work across our own business," chair and chief executive Marc Benioff said on the 26 August call.
One session, then a fade, then the upgrade
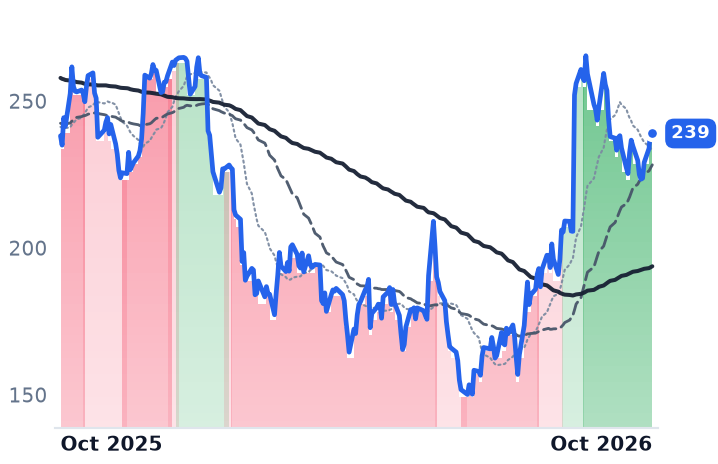
The re-rating was a single print. Salesforce closed at $205.62 on 26 August and $252.05 the next day, a 22.6% session, peaked at $265.44 on 3 September, and has since given back 10.0% to $238.97. Bank of America's Tal Liani upgraded the stock two notches, Underperform to Buy, raising his target to $285 from $160, on 12 October — after the fade, not before it.
At 14.3x forward earnings against 21.7x trailing, the shares already discount roughly 52% earnings growth this fiscal year. Consensus then has fiscal-2028 earnings per share 4.1% lower, at $16.07: the curve flattens the moment the forward year the multiple is struck on rolls off. A 7.7% trailing free-cash-flow yield is the cushion.
The same bargain, one layer down
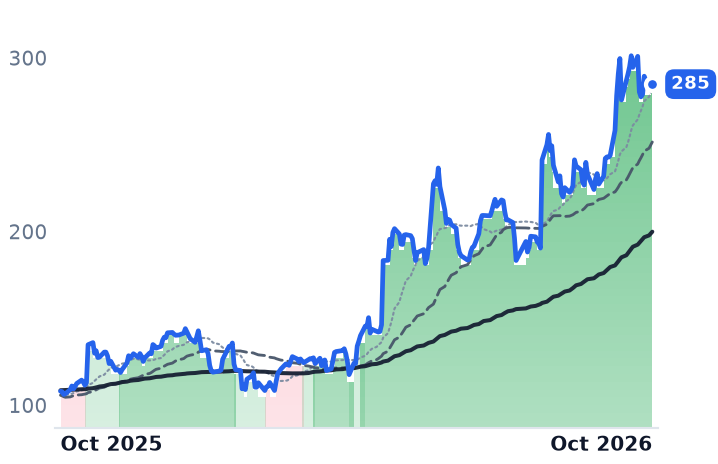
Twilio, which sells messaging and voice interfaces billed per message and per minute, is living the consumption model Salesforce is adopting, and it costs margin. Revenue grew 22% in the June quarter while gross margin slipped to 48.4% from 49.1%, because US carrier surcharges are billed on at near-zero margin; 5 of its 116 points of dollar-based net expansion were those fees, and messaging grew 28% reported but 18% excluding them. Its own third-quarter guide steps organic growth to 11–12% from 17%, and at 16.0x trailing gross profit the shares sit above the $265.71 street average target.
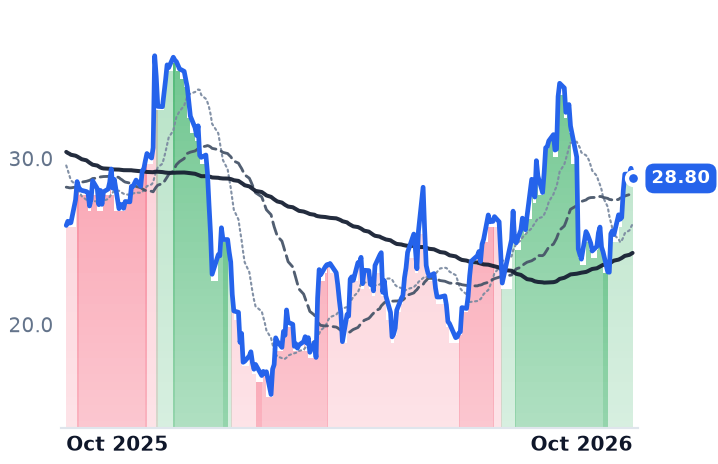
Braze, which orchestrates push, in-app and SMS messaging inside brands' own apps, shows the mechanism with the cleanest meters: net retention of 110%, up from 108%, and 112% among the 361 customers above $500,000 of annual recurring revenue, with gross margin down 70 basis points to 66.8% on premium messaging volumes. It trades at 5.86x trailing gross profit, essentially Salesforce's 5.77x, while growing gross profit 24.6% against Salesforce's 8.8%. "For every one example that I have where people are chasing their vibe coding dreams, we've got 10 more for whom Braze is their AI bet," chief executive William Magnuson said on the 8 September call.
What the quarter does and does not pay for
The booking data supports the view that front-office software is being expanded rather than replaced: raised full-year guidance, accelerating contracted revenue, steady attrition. It does not support the view that consumption pricing is yet paying the bill. At Salesforce the agent lines are too small to carry a $46bn book, the margin went backward, and the per-share line was bought. At Twilio and Braze, each incremental unit of metered volume arrives with its own cost of goods attached.
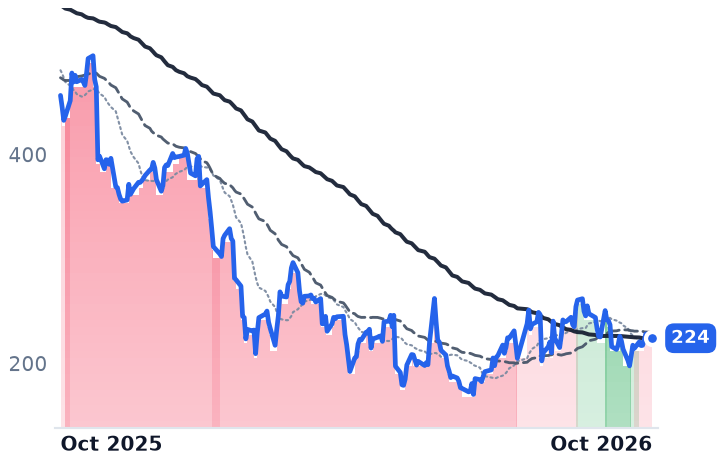
Treating the group as one trade also flatters it. Across the seven front-office names, the twelve-month advance is two stocks — Twilio up 163.6% and Zeta up 83.4% — against HubSpot down 50.2% and Pegasystems down 35.5%. HubSpot, at 4.0x trailing gross profit with revenue up 19.8%, is the cheapest of the group and the one that has been left out.
Twilio reports on 29 October with organic growth guided down by five points or more. That print, not an upgrade letter, is where consumption pricing gets its next invoice.