

ESAB Paid More Interest on Its Inspection Acquisition Than the Acquisition Earned
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
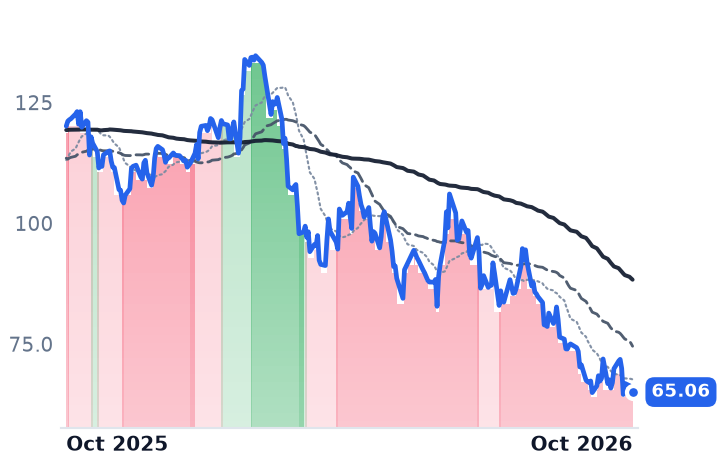
A welding company whose gross profit grew faster than its sales has lost nearly half its market value in a year, and the quarter that triggered the slide showed the business improving on every line above interest expense. ESAB's June quarter carried gross margin expansion of 86 basis points to 38.0%, and management lifted full-year core adjusted operating profit guidance to $615m-$625m from $575m-$595m.
In the same August release it cut per-share guidance, to $5.40-$5.50 from $5.70-$5.90. The cause is the $1.45bn Eddyfi purchase: in its first month inside ESAB it added seven cents of adjusted earnings while the debt and equity raised to buy it took sixteen.
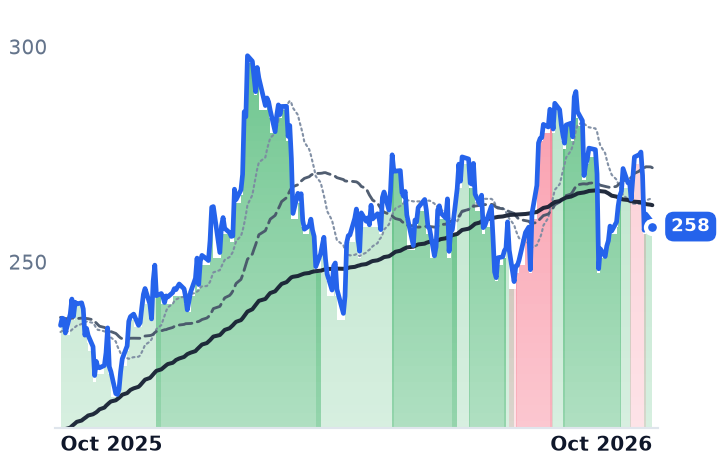
The welding end market is not the problem. Lincoln Electric, the closest listed comparison, is up 6.7% over twelve months with consumable volumes still growing. The pressure at ESAB sits in EMEA and APAC, and in a balance sheet that now carries more than $2.4bn of debt.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ESAB | ESAB | Welding & Cutting Solutions | 🔴 Cont. Bear | −3.7% | −45.8% |
MEC | Mayville Engineering | Welding & Cutting Solutions | ⚠️ Emerging Bear | −19.8% | +8.6% |
| Compared against · context, not the story | |||||
LECO | Lincoln Electric | Welding & Cutting Equipment | 🟢 Cont. Bull | +2.8% | +9.8% |
KMT | Kennametal | Metal Cutting Tools | 🔴 Cont. Bear | +5.7% | +44.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ESAB | $4.0B | 23.8x | 12.0x | 1.3x | 1.3x | 3.7x | 3.6x | 13.0x | 5.0% |
LECO | $14.3B | 26.0x | 23.4x | 3.2x | 3.0x | 8.9x | 8.4x | 17.1x | 3.6% |
KMT | $2.4B | 7.0x | 6.3x | 1.0x | 0.7x | 2.5x | 1.7x | 4.9x | -3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
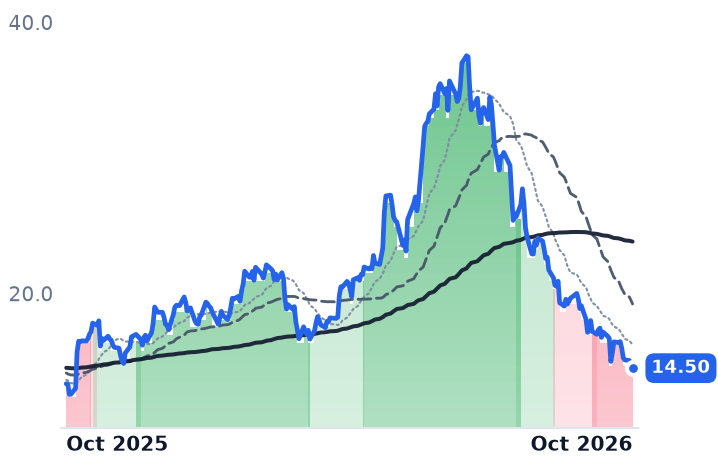
MEC | $304.8M | n/m | 56.1x | 0.5x | 0.5x | 6.0x | 5.6x | 19.0x | -1.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ESAB | Revenue | +13.2% | +9.0% | +4.9% |
| EPS | +2.4% | +17.7% | +13.8% | |
LECO | Revenue | +10.7% | +6.2% | +6.4% |
| EPS | +14.9% | +11.8% | +10.0% | |
KMT | Revenue | +18.6% | +44.0% | +3.0% |
| EPS | +180.0% | +27.2% | −52.9% | |
MEC | Revenue | +16.5% | +14.1% | +8.1% |
| EPS | +121.9% | +293.2% | +40.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
ESAB, which sells welding wire, electrodes, flux and cutting equipment through independent industrial distributors, raised its full-year operating profit guidance in August and cut its per-share earnings guidance in the same release. The gap between the two is an interest bill.
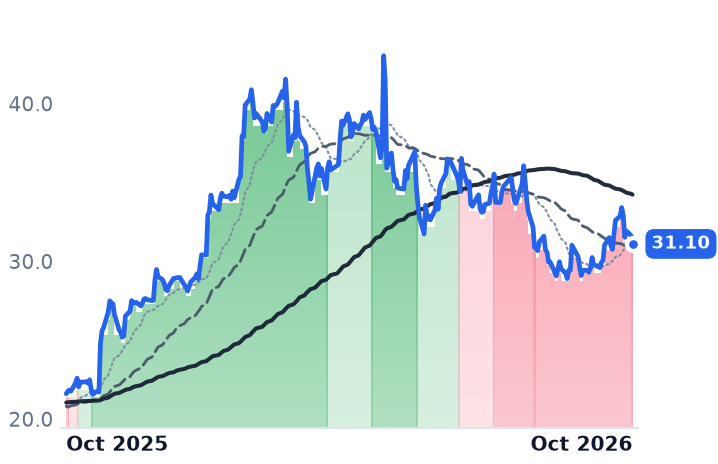
The company lifted core adjusted EBITDA guidance to $615m-$625m from $575m-$595m, and reduced core adjusted earnings per share guidance to $5.40-$5.50 from $5.70-$5.90 — a midpoint moving from $5.80 to $5.45. The shares have since been handled as though the welding market turned over. It did not: Lincoln Electric, the Cleveland arc-welding and consumables maker founded in 1895 and the closest listed analogue to ESAB's book, is up 6.7% over twelve months and reported Americas consumable volumes growing at a low-double-digit rate in the same quarter, with mid-single-digit growth continuing into the third. Kennametal, which makes tungsten carbide cutting tools for the same metal-fabrication customers, is up 44.5% over twelve months.
Seven cents acquired, sixteen cents financed
ESAB closed the purchase of Eddyfi Technologies, a Québec non-destructive testing and inspection business, on 1 June 2026 for $1.45bn, roughly 14.5 times Eddyfi's expected 2026 EBITDA of about $100m including $20m of anticipated run-rate synergies. It paid with cash, new 5.625% senior notes due 2031 and $318m of equity placed the same day: 175,000 shares of 6.50% mandatory convertible preferred for about $175m, plus 1,254,255 common shares.
One month of ownership added $0.07 to adjusted earnings per share and the financing removed $0.16 — thirteen cents of debt cost and three of share and preferred dilution. Reported adjusted EPS of $1.33 came in below the $1.43 consensus; excluding Eddyfi and its funding it was $1.41. The welding business came within two cents. The miss was the deal.
The debt stack behind it is now $1,700m of senior unsecured notes, $350m of term loans and $360m drawn on the revolver, and interest expense and other, net rose $18.4m in the first six months of 2026, including $4.8m of bridge loan commitment fees. Chief executive Shyam Kambeyanda called the purchase "a defining step that positions ESAB for faster organic growth and higher margins" on the 6 August call.
Where the operating margin actually gave way
Above interest, the quarter reads well. Gross profit rose 15.5% on 12.9% revenue growth and gross margin expanded 86 basis points to 38.04%, helped by consumable list prices resetting against input costs — hot-rolled coil averaged about $1,213 a short ton in September against roughly $800 a year earlier — with the 10-Q attributing $14.9m of customer pricing to tariff-driven materials costs and higher oil prices.
But group adjusted EBITDA margin fell 90 basis points to 19.5% while the Americas segment margin expanded 20 basis points to 20.3% on 5% organic growth. The drag is EMEA and APAC: core sales there grew 14% but only 1% organically, with Middle East revenues down roughly 10-11% and regional logistics costs roughly tripling. Chief financial officer Brent Jones attributed the margin decline to "transitory price/cost neutrality and deliberate targeted commercial investments to accelerate growth".
The equity is cheaper than the enterprise
ESAB hit a 52-week low of $64.47 on 8 October against a 52-week high of $137.42, falling 7.1% on 28 September and 7.7% on 8 October; it closed at $65.06 on 14 October, down 25.4% in three months and 45.1% in twelve. JPMorgan cut its target to $95.00 from $125.00 on 8 October while keeping an overweight rating.
On price to trailing gross profit — the comparison that matters when revenue is a metal index multiplied by pounds somebody else burns — ESAB trades at 3.69x against Lincoln Electric's 8.86x, on near-identical gross margins of 38.0% and 36.8%.
Move to the enterprise and most of that discount disappears: 13.0x trailing EV/EBITDA against Lincoln's 17.1x. The difference is the $2.4bn of debt, which sits inside enterprise value and not inside the share count. ESAB's 23.8x trailing price-to-earnings is on GAAP earnings of roughly $2.73 a share, depressed by deal and financing charges, while the 12.0x forward figure is on consensus adjusted earnings of $5.41 — a definitional gap, not a growth expectation.
The operating results do not account for a 45% decline. A five-percent cut to a per-share midpoint, with gross profit and operating profit guidance both moving up, is not a de-rating of that size. What can account for part of it is the shape of the earnings ahead: consensus has 2026 revenue up 13.2% to $3.057bn while EBITDA sits flat at $619.1m against $619.8m, which is 270 basis points of margin bought with acquired sales, and all of the guidance raise to 11.0%-14.0% core sales growth is acquisition, with organic held at 2.0%-4.0%. The market is being asked to fund a levered earnings pause and trust the $6.37 consensus for 2027.
Third-quarter results come before the open on 4 November, the first period carrying three full months of Eddyfi's profit and of the interest raised to buy it. Until then the cheapest reading of ESAB is also the most literal one: a welding business that worked, attached to a balance sheet decision that has not paid for itself yet.