

Berkshire's Union Tank Car Wants Duties on the Mexican Plants Greenbrier and Trinity Use
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A trade petition filed on the last day of September put a tax risk on the one place North America's two listed railcar builders assemble tank cars, and it landed in the same weeks their forward order books were getting better. Greenbrier booked 3,400 orders worth about $600m in the quarter to 31 August, against 2,200 worth $340m three months earlier; its reported May quarter showed revenue down 31.4% and operating margin halved to 5.5%. Trinity's earnings leapt on a $132m non-cash gain from moving roughly 17,025 cars into an investor-owned structure while segment operating income fell 31.5%. US rail traffic is up 3.5% through 38 weeks, so the builders' weakness is about delivery slots and where cars are welded. Greenbrier trades at 0.77x book; Trinity's trailing earnings multiple sits below its forward one.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
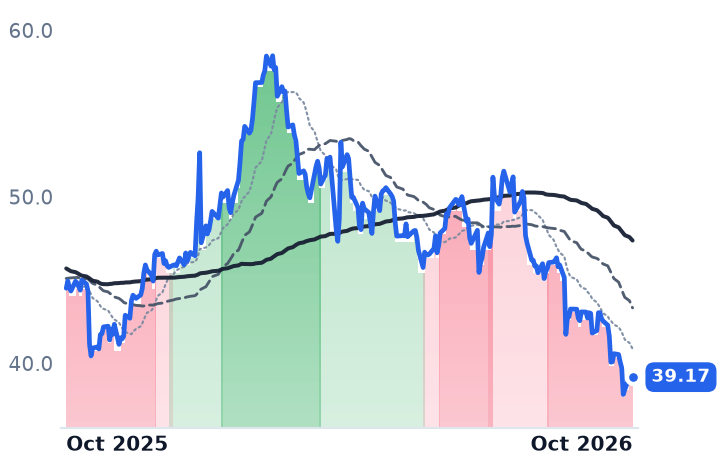
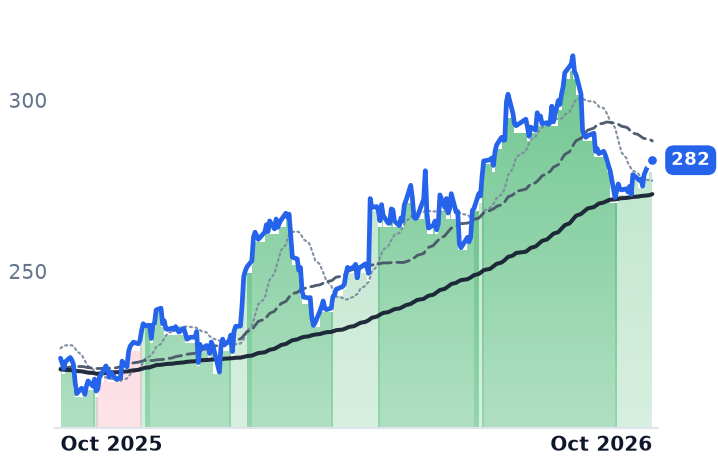
GBX | The Greenbrier Companies | Railcar Manufacturing | 🔴 Cont. Bear | −9.1% | −12.0% |
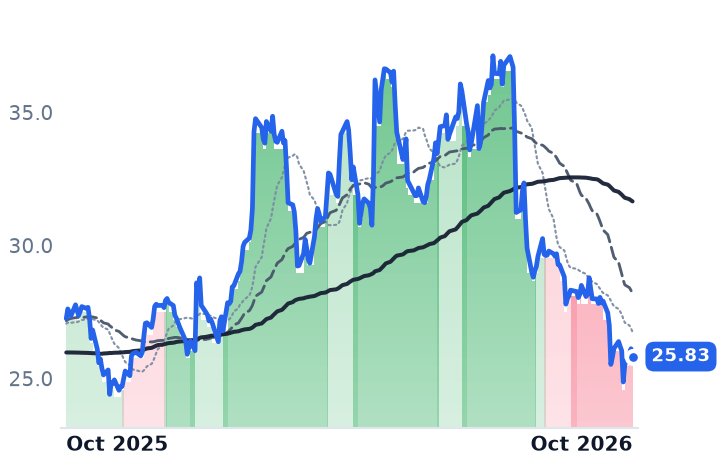
TRN | Trinity Industries | Railcar Manufacturing | ⚠️ Emerging Bear | −8.0% | −5.2% |
| Compared against · context, not the story | |||||
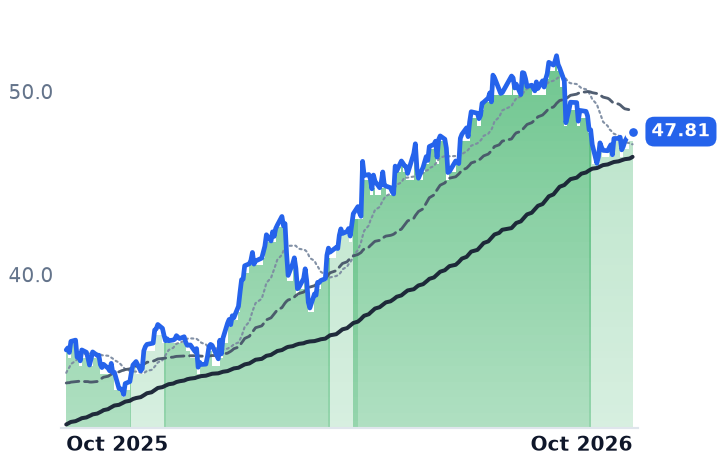
CSX | CSX | Class I Railroads | 🟢 Cont. Bull | −2.3% | +33.2% |
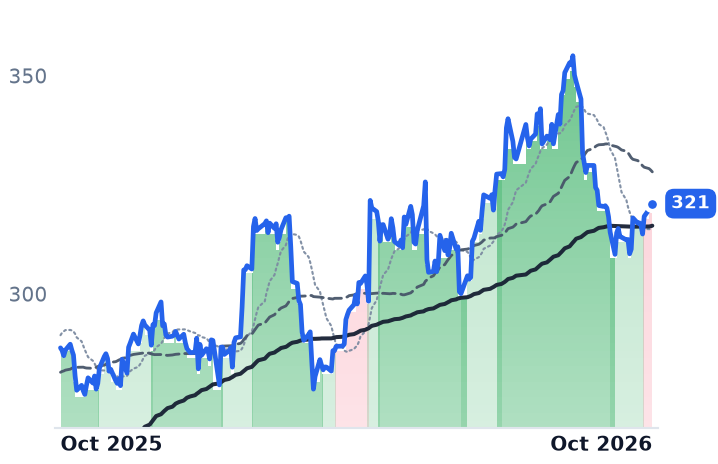
NSC | Norfolk Southern | Class I Railroads | 🟢 Cont. Bull | +0.2% | +11.5% |
UNP | Union Pacific | Class I Railroads | 🟢 Cont. Bull | −0.9% | +25.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GBX | $1.2B | 11.2x | 10.4x | 0.5x | 0.4x | 3.1x | 3.0x | 8.4x | -9.9% |
TRN | $2.1B | 6.0x | 11.6x | 1.0x | 0.9x | 3.9x | 3.6x | 6.8x | -17.1% |
CSX | $87.5B | 27.3x | 23.6x | 6.0x | 5.7x | 17.1x | 16.3x | 15.8x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NSC | $71.4B | 27.1x | 24.6x | 5.7x | 5.4x | 10.6x | 10.0x | 16.0x | 5.4% |
UNP | $165.4B | 22.5x | 21.3x | 6.5x | 6.1x | 14.3x | 13.4x | 14.6x | 3.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
GBX | Revenue | −23.5% | +8.5% | −0.4% |
| EPS | −53.2% | +23.6% | +34.7% | |
TRN | Revenue | +4.9% | +14.1% | −28.4% |
| EPS | −28.8% | +0.0% | +7.9% | |
CSX | Revenue | +8.0% | +5.2% | +3.4% |
| EPS | +22.4% | +14.1% | +10.3% | |
NSC | Revenue | +9.1% | +4.6% | +4.0% |
| EPS | +7.3% | +11.2% | +9.7% | |
UNP | Revenue | +10.3% | +4.7% | +11.5% |
| EPS | +11.9% | +8.8% | +9.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A Berkshire Hathaway subsidiary has asked Washington to tax railway tank cars built in Mexico, which is where both listed North American railcar builders assemble them. The request landed while their forward order books were improving: Greenbrier booked 3,400 orders worth $600m in the quarter to 31 August, against 2,200 worth $340m three months earlier.
The reported income statements say the opposite. Greenbrier's revenue fell 31.4% year over year in its May quarter and it has cut full-year delivery guidance to 15,650-15,850 cars from an original 17,500-20,500. Trinity's earnings jumped on a $132m non-cash gain from moving about 17,025 railcars into an investor-owned structure, while its segment operating income fell 31.5%.
US rail traffic is rising. What is in question is where the cars get built and which quarter they ship.
UTLX Manufacturing, a wholly owned Berkshire Hathaway subsidiary, filed antidumping and countervailing duty petitions on 30 September with the US Commerce Department and the International Trade Commission covering railway tank cars and parts imported from Mexico. Both listed builders with Mexican plants fell that session: Greenbrier, which engineers and builds freight and tank cars across North America, Europe and South America, by 3.8%, and Trinity Industries, which builds freight and tank cars and leases them to shippers, by 5.4%. Greenbrier closed at a twelve-month low eight days later.
The builders' long slide has been read as the railcar cycle rolling over. Carloads say something else: the Association of American Railroads reported combined US traffic for the first 38 weeks of 2026 up 3.5% year over year, and the week to 3 October up 5.1%. Industry deliveries are running near 25,000 cars this year against normalized replacement demand of 35,000 to 40,000. What the petition threatens is the thing that actually sets a builder's year: where a car is assembled, and which quarter the customer takes it.
The petition's argument is a market share
UTLX alleges dumping margins of 12.70% to 32.58% and cites Mexico's share of the US tank car market rising from 70.4% to 95.4% of a 7,841-unit market. Union Tank Car president Neil Finn said the domestic industry filed because it believes unfairly traded imports are causing significant harm to US manufacturing. Trinity has built railcars at Monclova for nearly three decades. Greenbrier countered that it runs a purpose-built tank car plant at Marmaduke, Arkansas and has invested more than $500m at Marmaduke and Paragould since 2019, and said it "will vigorously defend its record". Trinity, on 5 October, said it would "participate fully and actively" in both proceedings and that the petition "is not supported by the evidence or the law". Commerce faces an initiation deadline around 16 November.
Greenbrier's order book turned up as its revenue came apart
In the quarter to 31 May, Greenbrier delivered 3,600 railcars and booked 2,200 new orders worth $340m, leaving backlog at 13,800 units and $2.0bn. Revenue of $576.5m was down 31.4%, operating margin halved to 5.5%, and the company cut full-year aggregate gross margin guidance to 13.8%-14.2% from 14.8%-15.2%.
Then the forward meter moved. In the quarter to 31 August, Greenbrier announced 3,400 orders worth about $600m. On those disclosed totals, average order value rises from roughly $155,000 a car to about $176,000, because mix changed. The book includes 780 cars for Saudi Arabia Railways: tank cars for phosphoric acid and molten sulfur, plus Greenbrier's first intermodal sale to that customer.
A second, unlike dollar sits in the same ticker. Greenbrier's owned lease fleet grew 23% sequentially to 20,600 cars at 99% utilisation and roughly $1.7bn net book value, and it intends to spend about $300m a year on the fleet and double recurring revenue by 2028. Leasing and fleet management revenue was $47m at a 60.3% gross margin, about 8% of the quarter. Every car diverted to the fleet suppresses sales and lifts margin. Of $1,551m net funded debt, $1,086m is non-recourse lease-fleet borrowing against $465m recourse.
Trinity's year was decided by one transaction
Trinity's second-quarter net income of $102.2m, up 625%, included a $132m non-cash pre-tax gain on completing a Napier Park partnership that moved about 17,025 railcars to investor-owned status. Leasing segment margin was 79.8% with the gain and 33% without. Operating income fell 31.5% to $58.8m; deliveries were 1,570 cars and backlog $1.6bn. The lease book, meanwhile, is intact: utilisation 97.3%, renewal success 75%, and $30m of year-to-date gains on lease portfolio sales. The future lease rate differential, the gap between expiring and renewal rates, was positive 3.5%, a twentieth consecutive positive quarter, though down from 18.3% a year earlier.
"Inquiry levels for new rail cars are strong, reflecting growing customer conviction that the cycle has turned, demand side signals continue to be stronger than supply side signals," chief executive E. Jean Savage said on the 30 July call. The shares fell 14.9% over the two sessions that followed and have not regained that level.
The small builder proves the clock
The Chicago hopper, gondola and boxcar builder FreightCar America took about 45% of second-quarter industry orders and lifted backlog 121% to 3,972 units worth $344m — in the same quarter its gross margin fell to 5.5% from 15.0% and operating income swung to minus $4.3m on $113.1m of revenue. Management attributed its cut to 3,500-3,900 deliveries to a late production ramp driven by customer delivery timing, not lost demand. With no meaningful earnings multiple, the stock is judged on 0.4x trailing sales.
What the numbers account for
The reported results explain the de-rating through May and little after it. Greenbrier has lost 17.3% over three months and 25.6% over six, against declines of 4.2% at CSX, 2.0% at Union Pacific and 1.9% at Norfolk Southern over three months — the carriers whose volumes are growing. Two of Greenbrier's heaviest sessions have named causes: a 7.6% fall on 1 September, when the board disclosed its chief executive succession, and the petition day. The split between the two builders has a cause of its own. Trinity's 6.0x trailing earnings sits below its 11.6x forward multiple because the market declines to capitalise management-timed portfolio gains, with consensus 2026 earnings per share down 28.8% on revenue up 4.9%. Greenbrier trades at 0.77x book and 8.4x trailing EV/EBITDA with a lease fleet carried near $1.7bn at 99% utilisation, and its trailing and forward multiples are nearly identical, so no recovery is priced against a consensus that has next year's earnings rising about 24%.
Greenbrier reports its fiscal fourth quarter after the close on 26 October, Trinity three days later. Both will show order books that improved into the autumn and income statements still converting the thin slots of a deferred year.
Commerce decides around the middle of November whether to open the tank car case at all. Until then, the one line of business whose richer mix was lifting order values is also the line whose cost base sits in a country a Berkshire subsidiary is asking Washington to tax.