

Ralph Lauren Cut Promotions and Collected 15% More Per Garment
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Three premium apparel companies broke months-long uptrends within weeks of each other in September, and only one of them has a worse business to show for it. In this industry revenue is the least informative line a company prints: the same sales figure can mean fewer, dearer garments sold at the ticket price or the identical garments cleared on promotion.
Ralph Lauren's June quarter grew 14% with gross margin at 73.7% and inventory down 5%, promotions running below plan. Oxford Industries shrank entry-price dresses to 35% of the Lilly Pulitzer line, lost the customer and cut full-year earnings guidance to $1.60-$2.00 from $2.30-$2.70. PVH sits between them, its largest region's growth set by European department-store buyers two seasons ahead.
The autumn slide was a shelf-wide de-rating. Oxford's de-rating is the one the results earn.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
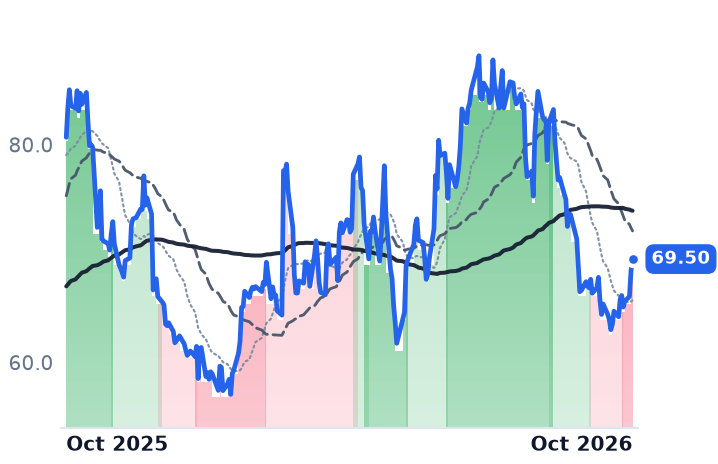
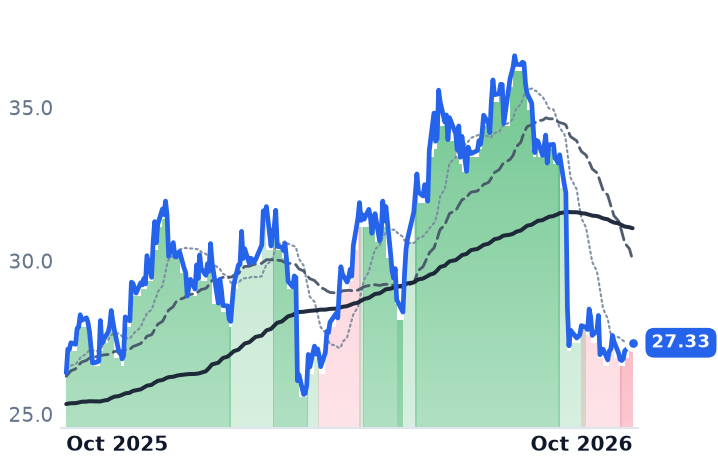
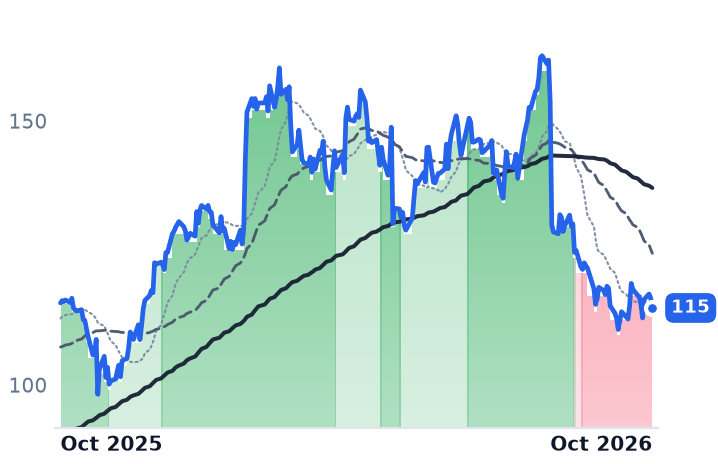
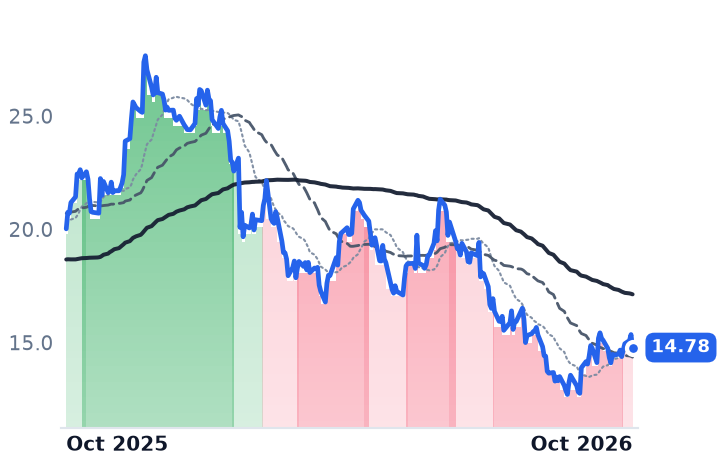
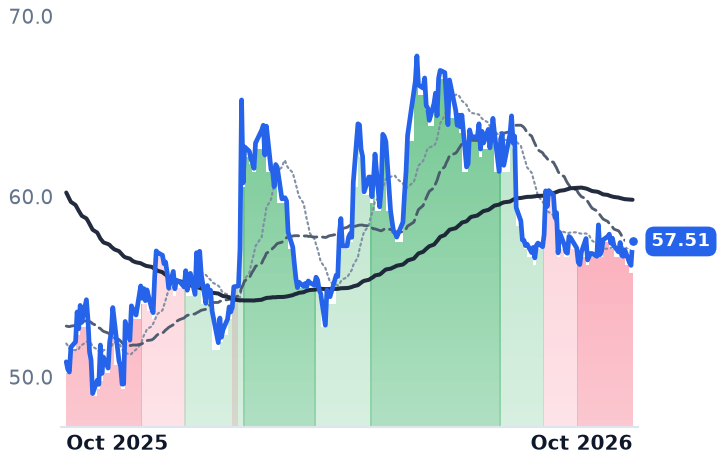
RL | Ralph Lauren | Premium Lifestyle | ⚠️ Emerging Bear | +9.4% | +18.1% |
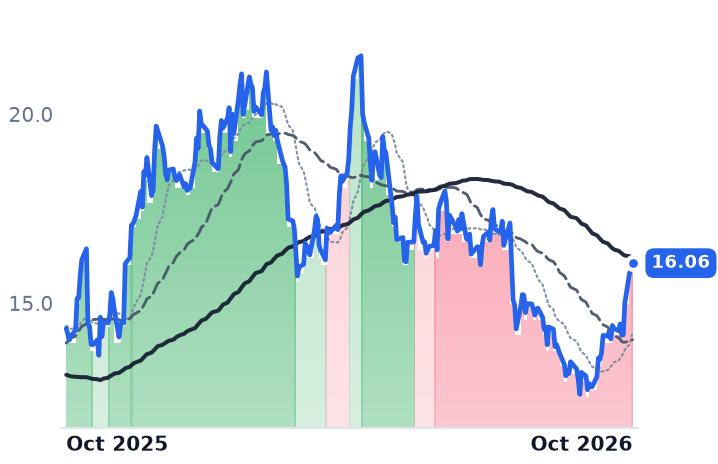
PVH | PVH | Premium Lifestyle | ⚠️ Emerging Bear | +11.7% | −1.8% |
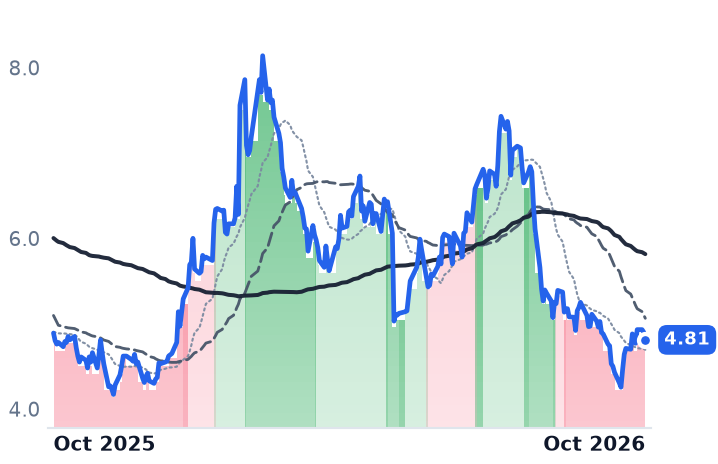
OXM | Oxford Industries | Premium Lifestyle | 🔴 Cont. Bear | −16.3% | −27.8% |
| Compared against · context, not the story | |||||
LEVI | Levi Strauss | Denim & Casual | ⚠️ Emerging Bear | −3.9% | −7.3% |
KTB | Kontoor Brands | Denim & Casual | 🟢 Cont. Bull | +3.1% | −13.9% |
GIII | G-III Apparel | Denim & Casual | ⚠️ Emerging Bear | −1.8% | +3.7% |
TPR | Tapestry | Handbags & Accessories | ⚠️ Emerging Bear | −2.8% | −0.8% |
CPRI | Capri | Handbags & Accessories | 🔴 Cont. Bear | +4.4% | −26.2% |
COLM | Columbia Sportswear | Performance & Sports | ⚠️ Emerging Bear | −0.3% | +13.1% |
VFC | V.F | Outdoor & Adventure | 🔴 Cont. Bear | +22.9% | +12.0% |
UAA | Under Armour | Performance & Sports | 🔴 Cont. Bear | −4.4% | −1.6% |
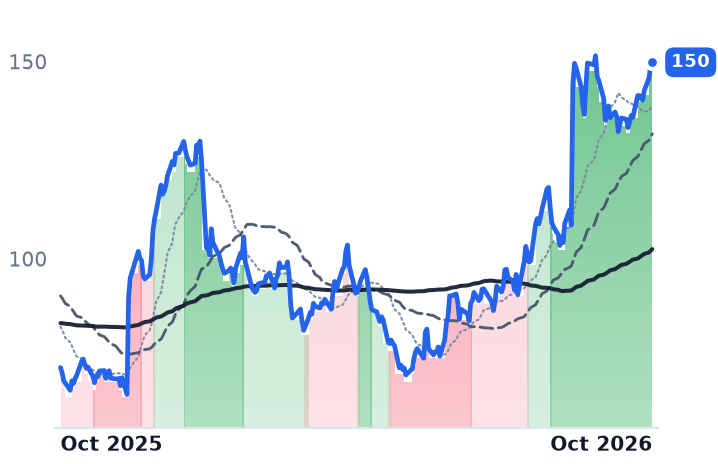
ANF | Abercrombie & Fitch | Specialty Apparel | 🌱 Emerging Bull | +6.5% | +106.8% |
BURL | Burlington Stores | Off-Price Retailers | ⚠️ Emerging Bear | +12.1% | −5.0% |
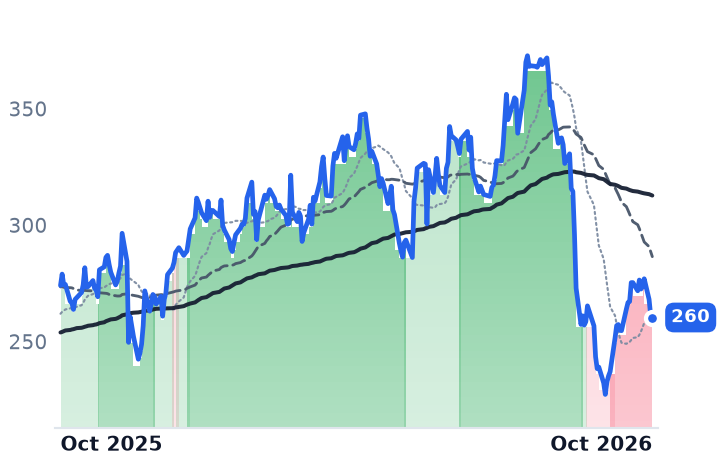
12-month price & trend
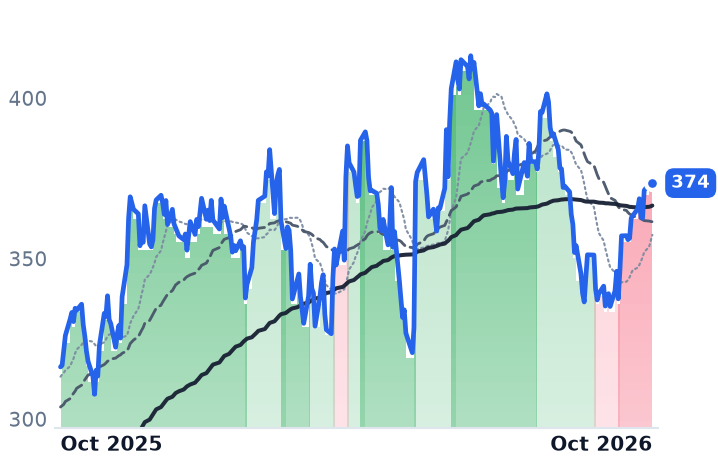
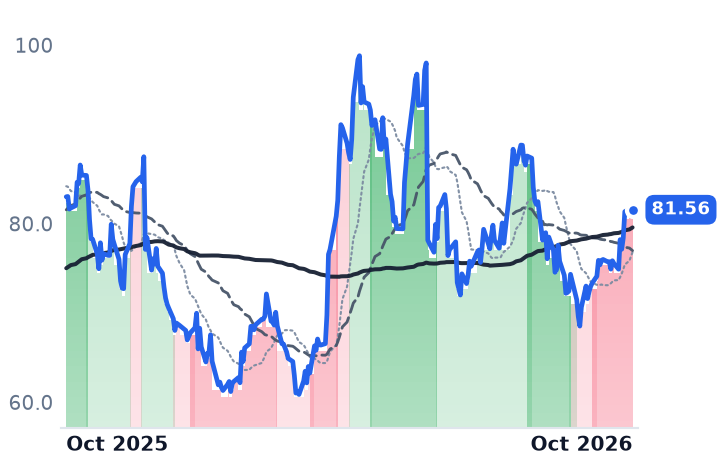
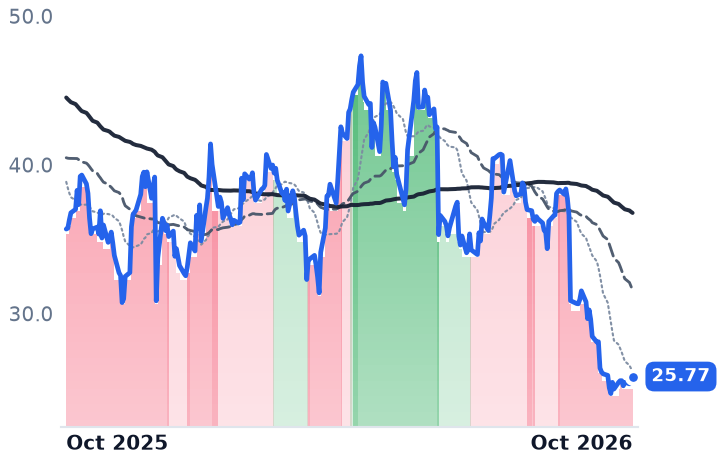
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RL | $22.9B | 23.3x | 19.8x | 2.7x | 2.6x | 3.9x | 3.8x | 16.3x | 4.6% |
PVH | $3.8B | n/m | 6.7x | 0.4x | 0.4x | 0.7x | 0.7x | 11.0x | 19.0% |
OXM | $388.8M | n/m | 14.8x | 0.3x | 0.3x | 0.4x | 0.4x | 15.8x | 13.4% |
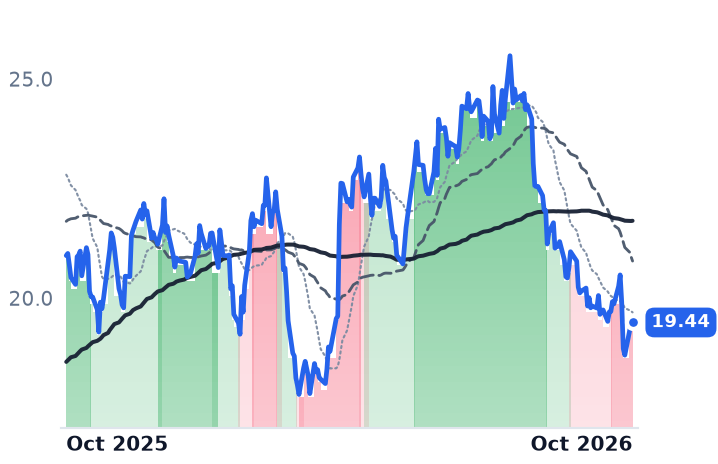
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEVI | $8.3B | 13.2x | 14.0x | 1.3x | 1.2x | 2.1x | 2.0x | 10.1x | 5.9% |
KTB | $3.4B | 12.3x | 11.5x | 1.1x | 1.2x | 2.3x | 2.5x | 10.1x | 11.7% |
GIII | $1.2B | 18.0x | 13.8x | 0.4x | 0.4x | 1.1x | 1.2x | 5.9x | 21.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TPR | $23.0B | 15.2x | 14.2x | 2.9x | 2.7x | 3.7x | 3.4x | 12.2x | 7.9% |
CPRI | $1.5B | 10.1x | 6.0x | 0.4x | 0.4x | 0.7x | 0.7x | 11.5x | 5.7% |
COLM | $3.0B | 18.0x | 15.0x | 0.9x | 0.8x | 1.7x | 1.7x | 11.9x | 5.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VFC | $5.2B | 18.8x | 12.3x | 0.5x | 0.5x | 1.0x | 1.0x | 11.7x | 11.2% |
UAA | $2.2B | n/m | 40.1x | 0.4x | 0.4x | 0.9x | 1.0x | n/m | -7.6% |
ANF | $3.2B | 6.4x | 6.6x | 0.6x | 0.6x | 1.0x | 1.0x | 4.1x | 11.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BURL | $18.4B | 30.9x | 25.6x | 1.6x | 1.5x | 3.8x | 3.5x | 18.2x | 1.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RL | Revenue | +13.6% | +8.8% | +5.3% |
| EPS | +35.1% | +15.9% | +11.0% | |
PVH | Revenue | +3.0% | +0.2% | +1.7% |
| EPS | −6.6% | +10.8% | +3.1% | |
OXM | Revenue | −2.3% | −1.3% | +2.3% |
| EPS | −66.2% | −20.9% | +33.3% | |
LEVI | Revenue | +7.5% | +4.9% | +6.0% |
| EPS | +13.0% | +12.0% | +15.6% | |
KTB | Revenue | +19.4% | −9.7% | +4.2% |
| EPS | +13.2% | −2.7% | +21.4% | |
GIII | Revenue | −5.4% | −9.0% | −2.1% |
| EPS | −30.3% | −28.0% | +9.8% | |
TPR | Revenue | +14.7% | +7.1% | +5.4% |
| EPS | +37.4% | +14.1% | +11.7% | |
CPRI | Revenue | −20.8% | −2.2% | +2.5% |
| EPS | +38.9% | +51.2% | +18.4% | |
COLM | Revenue | +3.5% | +3.2% | +2.2% |
| EPS | +21.1% | +9.8% | +3.1% | |
VFC | Revenue | −2.4% | +1.9% | +3.1% |
| EPS | +12.1% | +29.2% | +24.3% | |
UAA | Revenue | −3.7% | −0.1% | +2.8% |
| EPS | −61.8% | +9.0% | +88.5% | |
ANF | Revenue | +6.8% | +3.9% | +3.8% |
| EPS | −7.7% | +8.9% | +9.6% | |
BURL | Revenue | +8.6% | +10.6% | +8.9% |
| EPS | +23.7% | +17.3% | +17.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ralph Lauren sold its June quarter at close to full ticket, and that single disclosure separates it from the two companies sitting beside it on the premium apparel shelf. Revenue at the owner of Polo, Purple Label and RLX rose 14% to $1.96bn in the three months to 27 June, with average unit retail, the price actually collected per garment, up 15% across its own stores and sites on what the company called "continued elevation and strong full-price selling trends, with lower than planned promotions".
That line is the whole argument of a premium apparel quarter. A revenue number cannot say whether a brand got stronger: a company holding units flat while pushing price runs the opposite business from one clearing the same garments at 40% off, and both print the same sales figure. August and September were read across the shelf as the affluent apparel consumer cracking, and the group de-rated together. US consumer spending on clothing rose 3.9% year on year in August, ahead of overall spending growth of 2.6%.
What divided these three was who sets the number on the ticket.
Fewer promotions, and the margin to show for them
Ralph Lauren's gross margin reached 73.7% in the quarter, 1.4 points above a year earlier, the company crediting average unit retail growth plus channel and geographic mix for more than offsetting incremental pressure from tariffs and other product costs. Inventory finished at $1.2bn, down 5%: a higher price per unit against falling stock is the opposite of a markdown quarter being staged. Roughly 69% of last year's dollars came through retail against 31% wholesale, per the FY2026 annual report, so the company mostly rings its own prices at its own tills.
The duty bill is modelled to arrive later. On the 6 August call Ralph Lauren held an assumption of about 10% tariff rates through the first half of its year and reciprocal rates in the high teens in the second. "Brand elevation is not a destination," chief financial officer Justin Picicci told investors that day. "It's an ongoing journey, and we're still in the early innings." Guidance went up, to constant-currency revenue growth of 5% to 6%. The shares trade at 19.8x forward earnings against 23.3x trailing, and holding consensus constant that forward figure was 21.2x at the 30 June peak and 17.8x at the 2 September low: a round trip, with no net compression.
The $350m PVH collects on clothes it does not sew
PVH, which owns Calvin Klein and Tommy Hilfiger and licenses both to third parties for categories it does not manufacture, takes in more than $350m a year of licensing revenue supporting over $3bn of licensee sales. How profitable that stream is shows up when it stops: bringing previously licensed women's categories in house lifted net revenue about 1% in 2025 while cutting gross margin roughly 50 basis points, because a royalty dollar carries almost no cost of goods.
Revenue fell 3.2% to $2.097bn in the quarter to 2 August and Calvin Klein revenue dropped 7%, yet Calvin Klein denim sold direct grew double digits on double-digit gains in price per unit. Strip out $107m of tariff refunds, worth 510 basis points, and gross margin rose about 20. The constraint sits in a channel: wholesale revenue fell 6% on European weakness and the Spring 2027 order book, taken months ahead, is down mid-single digits as European wholesalers turn cautious. Inventory fell 3% to $1.738bn, so there is no glut behind it yet.
"We are really leaning into cost as a real driver of EBIT margin expansion," chief executive Stefan Larsson said on 3 September. The diluted share count has gone from 56.7m to 46.1m in two years, so per-share earnings can rise on an unchanged profit pool. At 6.7x forward earnings and 0.72x gross profit against Ralph Lauren's 3.90x, with a 19.0% trailing free-cash-flow yield, PVH is priced off that order book rather than the royalty stream; its trailing earnings multiple says nothing after a $439m goodwill write-off.
Oxford moved its price ladder and the customer stayed home
Oxford Industries has no royalty cushion and little wholesale buffer: direct-to-consumer was 82% of FY2025 sales, with Tommy Bahama 56% of the total. Comparable sales fell 1% in the August quarter, retail down 3%, and Lilly Pulitzer posted mid-single-digit negative comps after entry-level dresses under $200 fell from about half of its styles to 35%.
The cause was self-inflicted. "What we did this year is I think we just went too far too fast in shifting up the pricing tiers," chief executive Thomas Chubb said on 3 September, dating the remedy beyond this year: "Spring '27 is the first season where we were able to really incorporate what we realized was wrong about the assortment in spring '26."
Guidance followed, to sales of $1.43-1.47bn and adjusted earnings of $1.60-$2.00 from $2.30-$2.70. Oxford's forward multiple fell to 14.6x from about 20.8x on 3 September, but trailing EV/EBITDA is still 15.8x, because EBITDA fell faster than the price. Long-term debt came down $70m sequentially to $73m and capital spending is guided to $60m from $108m as the Lyons distribution center finishes, so the balance sheet is being repaired while the brands are.
What the autumn slide actually was
Over the three months to 14 October Levi Strauss fell 18.3%, G-III 20.0%, Kontoor 17.1% and Tapestry 15.4%, with Oxford down 30.8%, while Ralph Lauren (+1.2%) and PVH (+5.7%) were the group's only gainers besides Abercrombie. Over twelve months the three span 49 points, from Ralph Lauren up 17.5% to Oxford down 31.3%, which is why a category average near +6% describes none of them.
The businesses account for one of the three moves. Ralph Lauren collects its price increase at its own registers and has been allowed to keep it; Oxford owns its registers too but set the ladder wrong; PVH's largest region is governed by a department-store buyer's inventory plan agreed two seasons ahead.
The one input all three share is landed cost. The average applied US tariff on apparel reached 22.7% in August, and a garment ordered two seasons ahead carries that duty into a gross margin reported months later, which puts it in the holiday quarter now being traded, the one PwC's survey says consumers enter reporting net-negative spending intent across nearly every discretionary category. When Ralph Lauren next reports, the revenue line will again be the least informative number in it.