

Dollar Tree, Dollar General and Ollie's Spent Their Tariff Refunds on Shelf Prices
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Three discount retailers posted their widest gross margins in years this summer, and in each case most of the gain was money the federal government gave back. The margin bridges were read as a trade-down windfall finally reaching the shelf; strip the refund out and the three businesses point in different directions.
Dollar Tree booked $383m of refunded duties, 680 of its 850 basis points of expansion, and is reinvesting about $210m in prices, marketing and stores. Ollie's whole 360 basis points of expansion was refund and more, leaving underlying margin near 40.3% against its own 40.5% target on a comparable sales decline of 1.8%. Only Dollar General's core improved: comps up 3.5% on traffic up 2.0%, a fifth straight quarter of traffic growth, with 81 of 127 basis points from the refund.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
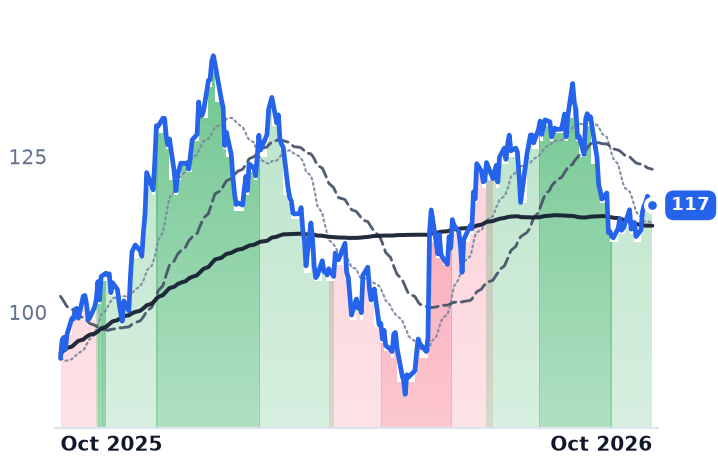
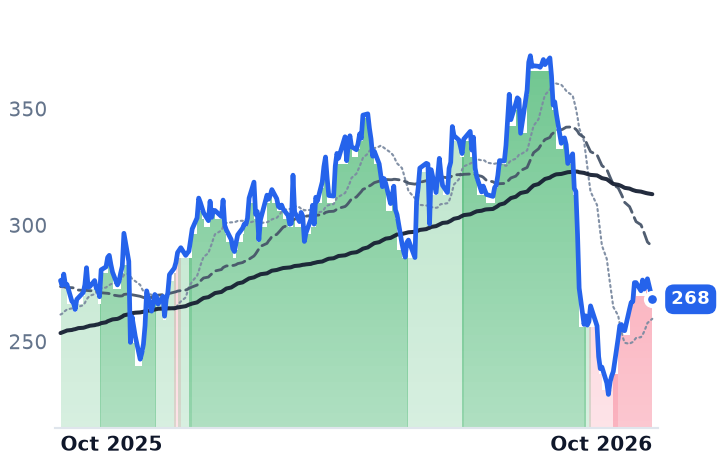
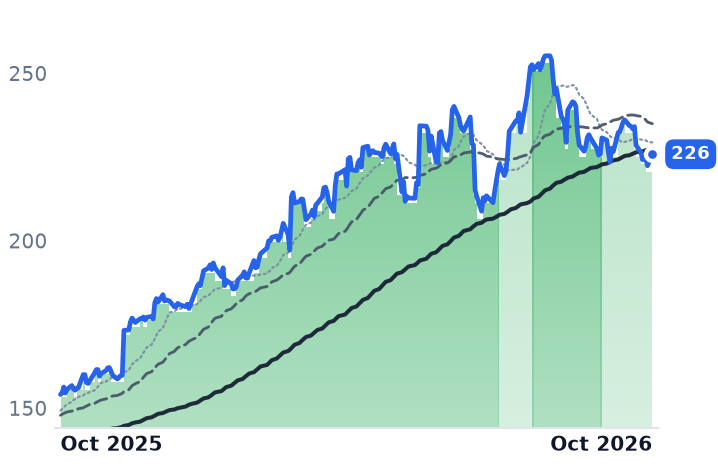
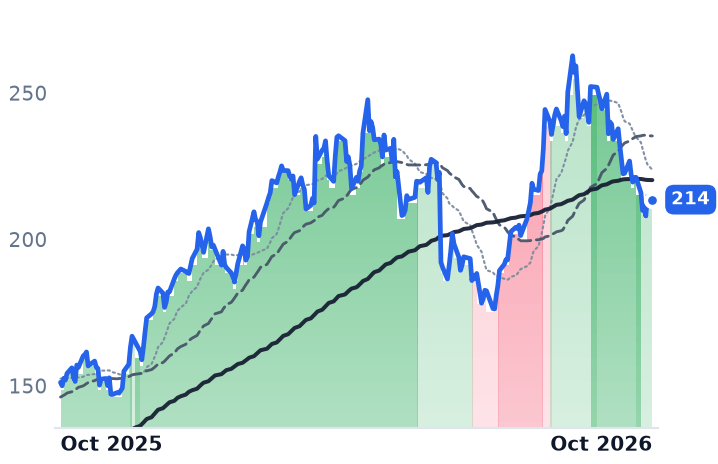
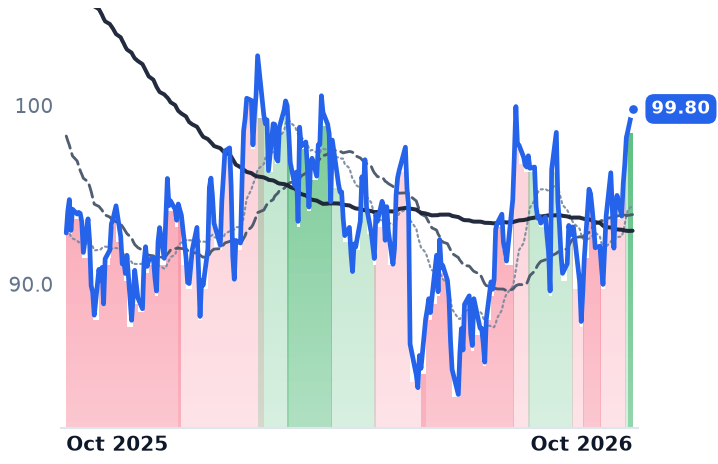
DLTR | Dollar Tree | Small-Format Value | 🟢 Cont. Bull | −1.7% | +26.6% |
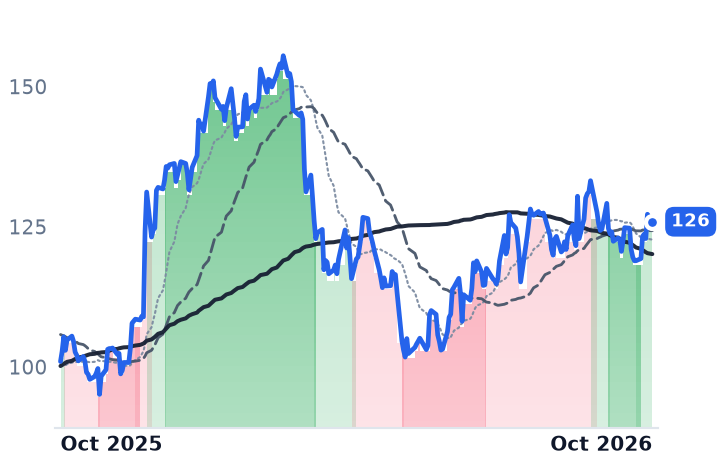
DG | Dollar General | Small-Format Value | 🌱 Emerging Bull | −2.5% | +24.7% |
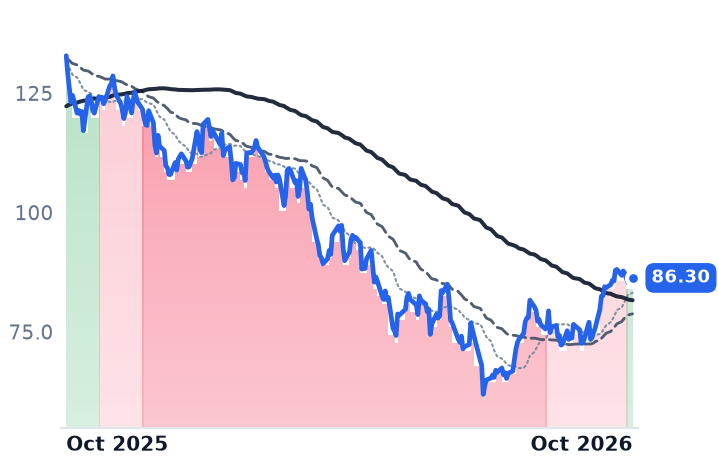
OLLI | Ollie's Bargain Outlet | Bargain Outlet | 🔴 Cont. Bear | +12.0% | −35.0% |
| Compared against · context, not the story | |||||
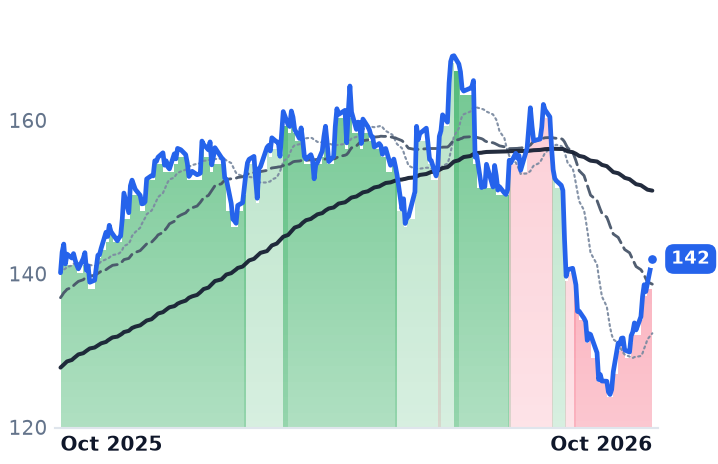
TJX | The TJX Companies | Off-Price Discounters | ⚠️ Emerging Bear | +12.6% | +1.3% |
BURL | Burlington Stores | Off-Price Discounters | ⚠️ Emerging Bear | +15.5% | −2.9% |
ROST | Ross Stores | Off-Price Discounters | 🟢 Cont. Bull | −1.8% | +46.6% |
FIVE | Five Below | Variety, Convenience & Specialty | 🟢 Cont. Bull | −14.4% | +41.3% |
BJ | BJ's Wholesale Club | Warehouse Clubs | 🌱 Emerging Bull | +4.7% | +7.5% |
TGT | Target | General Merchandise | 🟢 Cont. Bull | −3.2% | +81.6% |
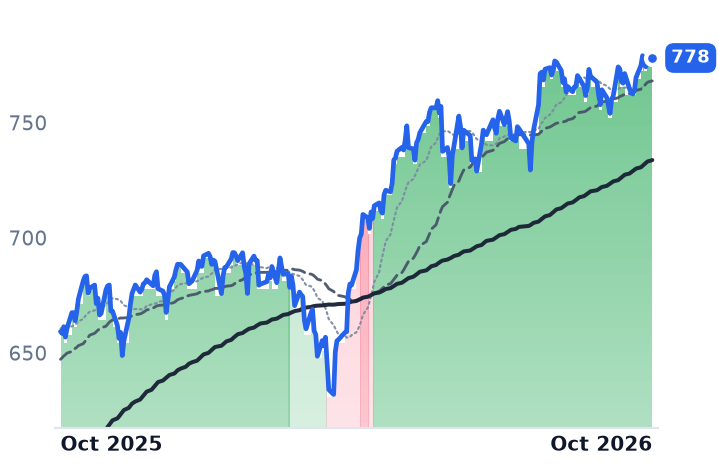
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +2.3% | +18.0% |
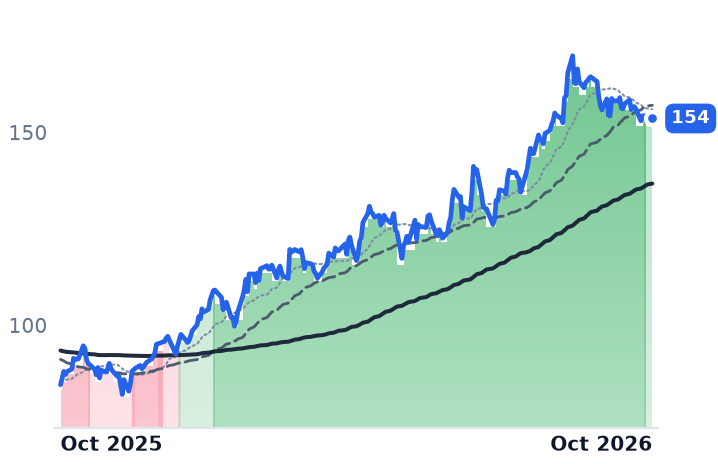
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DLTR | $22.8B | 14.5x | 15.0x | 1.1x | 1.1x | 2.9x | 2.8x | 9.7x | 8.1% |
DG | $28.1B | 16.5x | 16.1x | 0.6x | 0.6x | 2.1x | 2.0x | 12.0x | 9.6% |
OLLI | $5.2B | 19.0x | 18.5x | 1.8x | 1.8x | 4.6x | 4.4x | 13.6x | 4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TJX | $157.1B | 26.4x | 27.1x | 2.5x | 2.5x | 7.8x | 7.6x | 18.2x | 3.7% |
BURL | $16.6B | 23.6x | 22.1x | 1.4x | 1.3x | 3.0x | 2.9x | 14.9x | 6.1% |
ROST | $74.0B | 27.7x | 27.3x | 3.0x | 2.9x | 10.1x | 9.6x | 18.8x | 3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FIVE | $12.1B | 19.5x | 21.4x | 2.3x | 2.1x | 5.9x | 5.5x | 13.3x | 4.9% |
BJ | $13.1B | 22.4x | 21.9x | 0.6x | 0.5x | 3.1x | 3.0x | 13.5x | 2.8% |
TGT | $70.5B | 16.0x | 15.2x | 0.7x | 0.6x | 2.2x | 2.2x | 9.1x | 6.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DLTR | Revenue | −37.0% | +6.5% | +6.0% |
| EPS | +6.1% | +37.3% | −0.2% | |
DG | Revenue | +5.1% | +4.5% | +4.1% |
| EPS | +14.4% | +20.3% | +5.6% | |
OLLI | Revenue | +16.4% | +10.6% | +11.1% |
| EPS | +17.6% | +19.1% | +7.3% | |
TJX | Revenue | +6.7% | +6.7% | +6.3% |
| EPS | +11.7% | +12.5% | +9.5% | |
BURL | Revenue | +8.6% | +10.8% | +9.1% |
| EPS | +23.7% | +21.6% | +13.8% | |
ROST | Revenue | +6.6% | +14.0% | +6.9% |
| EPS | +5.4% | +29.7% | +6.5% | |
FIVE | Revenue | +22.9% | +20.4% | +9.2% |
| EPS | +29.1% | +60.8% | +7.9% | |
BJ | Revenue | +4.5% | +11.8% | +5.7% |
| EPS | +9.7% | +8.0% | +6.6% | |
TGT | Revenue | −1.5% | +5.1% | +3.3% |
| EPS | −16.1% | +39.6% | −5.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Dollar Tree's summer gross margin was the widest the chain has printed in years, and four-fifths of the improvement was a refund of duties the Supreme Court decided the government never had the authority to collect. After February's ruling that the International Emergency Economic Powers Act did not support the tariffs levied under it, roughly $166bn of duties began returning to importers of record, with interest, through a Customs and Border Protection refund portal. Dollar General and Ollie's Bargain Outlet booked their shares inside cost of goods sold in the same quarter.
The bridges were read as proof that the trade-down shopper is finally paying off at the margin line. All three companies are instead handing the refund to that shopper as lower shelf prices, which makes the expansion a one-year event; and underneath it, only one of the three businesses got better.
The refund, by how much of the margin it bought
At Dollar Tree, which sells a fixed-price assortment of food, household basics and seasonal general merchandise, 680 of 850 basis points of gross-margin expansion in the quarter ended 1 August was net tariff impact, taking gross margin to 42.9%. At Ollie's, the closeout chain that buys brand-name overstock and liquidation lots, the refund was worth 380 basis points of a 360 basis-point expansion: all of it, and more. At Dollar General, the rural small-box chain, 81 of 127 basis points.
None of the three banked it. "We will not hesitate to invest beyond this level to strengthen our price leadership position," Eric van der Valk, Ollie's president and chief executive, told investors on 2 September. Dollar Tree is putting about $210m of its $383m back into cost of goods, marketing and store operations.
Dollar Tree's price is printed before the cost is known
Dollar Tree publishes its price in advance, so landed cost, freight and duty land in gross margin rather than in revenue. The levers are the item behind the price and the share of the assortment lifted above the $1.25 anchor: multi-price merchandise reached 17% of total sales, up about 400 basis points year over year, across roughly 6,600 stores. "Rather than passing those costs on to the customer, we've taken advantage of the fact that we're getting that lower tariff rate in and that tariff rate is absorbing inflation," chief financial officer Stewart Glendinning said on 27 August.
That absorption has a term. Management guided third-quarter gross margin flat and fourth-quarter margin down year over year on fuel, freight and merchandise inflation, with third-quarter adjusted earnings of $0.80 to $0.95 a share including a $0.50 reinvestment headwind. Investors priced the guide: the shares fell through late September and are 16.3% below the 25 August high of $133.74. At 15.0x forward earnings against 14.5x trailing, the forward figure sits higher because consensus of $7.90 is below the $8.19 of trailing earnings that contains the refund quarter's $1.31.
Ollie's buying was never the problem
Ollie's margin is a buying outcome, and the buying was fine: TJX, Ross and Burlington all describe closeout supply as highly favorable. Demand was the problem. Comparable sales fell 1.8% on flat traffic and a smaller basket, with unseasonable weather in lawn and garden and air conditioners costing more than 100 basis points of comp; acquired Big Lots boxes are comping low-to-mid single digits negative in their second year. Full-year sales guidance was cut to $2.928–2.941bn from $2.98–3.00bn, comps to flat-to-+0.5%.
The stock then rose 17.6% in thirty days, alongside TJX at 9.9% and Burlington at 13.7%, while Five Below fell 13.9%. The likelier reading is a bid for closeout and off-price retailing generally; consensus earnings of $4.61 sit at the midpoint of the cut guide, with no upward revision behind the move. At 18.5x forward Ollie's is the dearest of the three, and 19.0x trailing against 36.7x a year ago is a de-rating interrupted.
Dollar General earns it on shrink and trucks
With consumables at 82% of net sales, Dollar General has no price point to defend and makes its money on shrink, markdowns and distribution cost. "This marks the fifth consecutive quarter of growth in customer traffic," chief executive Todd Vasos said on 27 August, on comps of 3.5% with traffic up 2.0%. Operating income rose 29.2% on sales up 5.2%, full-year earnings guidance went to $7.80–8.00 from $7.20–7.45, and up to $700m of buybacks was pulled into the second half. The shares are up 28.9% over twelve months while the trailing multiple fell to 16.5x from roughly 18.3x.
What the pump price decides
The refund accounts for four-fifths of Dollar Tree's margin gain, roughly two-thirds of Dollar General's and all of Ollie's. What it does not explain is why the traffic went one way. Gasoline at $4.359 a gallon, up 39.4% in a year, taxes a destination trip and spares a fill-in one: Ollie's blames longer drive times in Midwest, Texas and Western markets, while Dollar General's shopper is a few miles away and its remodel program adds comp mechanically. There is also a claim on the windfall itself, since retailers that passed the duties to shoppers now face consumer class actions arguing the refunds belong to those shoppers.
All three report again in December. By then the refund is spent money, and what is left on the shelf is a price each company has promised to hold without it.