

Monolithic Power Holds the Last Volt Drop in an AI Rack; Two Rivals Bought Their Way In
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Three companies have now paid for position in the final conversion stage of an AI rack — the step that delivers current straight into an accelerator — and the incumbent there is the one whose shares spent September falling. Navitas closed a $232.8m purchase of Claros on 6 October for integrated-voltage-regulator capability; Analog Devices paid $1.5bn for Empower.
Monolithic Power already supplies that socket, and its June-quarter filings show Enterprise Data revenue up 164.3% to $380.6m and 38.8% of the mix, with gross margin flat near 55.2% and inventory days down 17 to 140. None of that answers the question the market is actually asking, which is how many of the power phases on the next Nvidia platform's board are Monolithic's.
Navitas sits on the other side: revenue down 27.3% year on year, no meaningful gross profit, and 18.6% more diluted shares.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | +21.3% | +41.7% |
NVTS | Navitas Semiconductor | Other | ⚠️ Emerging Bear | −1.0% | +8.1% |
| Compared against · context, not the story | |||||
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | +12.5% | +74.2% |
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | +7.7% | +65.4% |
ON | ON Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | +8.2% | +54.7% |
VICR | Vicor | Other | ⚠️ Emerging Bear | +44.0% | +412.1% |
POWI | Power Integrations | Analog & Mixed-Signal | ⚠️ Emerging Bear | +1.3% | +15.1% |
AOSL | Alpha and Omega Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | +15.1% | −5.3% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | +5.7% | +19.1% |
NXPI | NXP Semiconductors | Analog & Mixed-Signal | ⚠️ Emerging Bear | +1.5% | +6.0% |
STM | STMicroelectronics | Analog & Mixed-Signal | ⚠️ Emerging Bear | +9.0% | +81.9% |
WOLF | Wolfspeed | Discrete & Power | ⚠️ Emerging Bear | +27.8% | −6.0% |
VSH | Vishay Intertechnology | Discrete & Power | ⚠️ Emerging Bear | +10.5% | +117.1% |
ALGM | Allegro MicroSystems | Other | ⚠️ Emerging Bear | +5.1% | +29.8% |
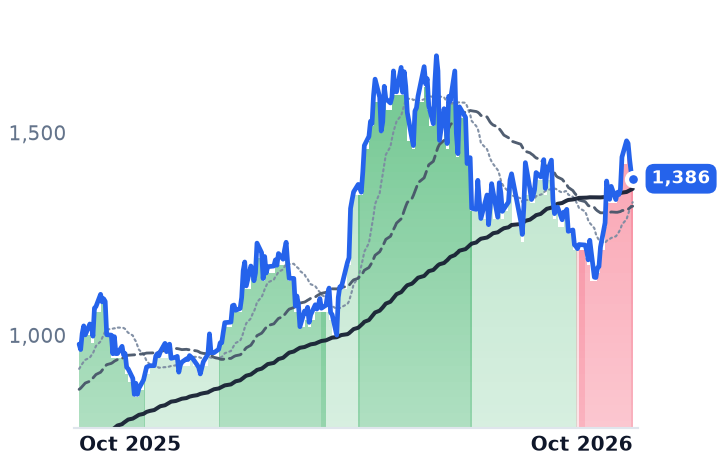
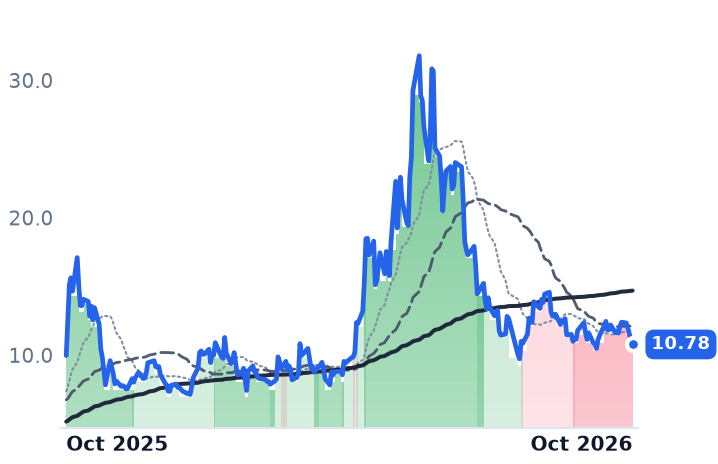
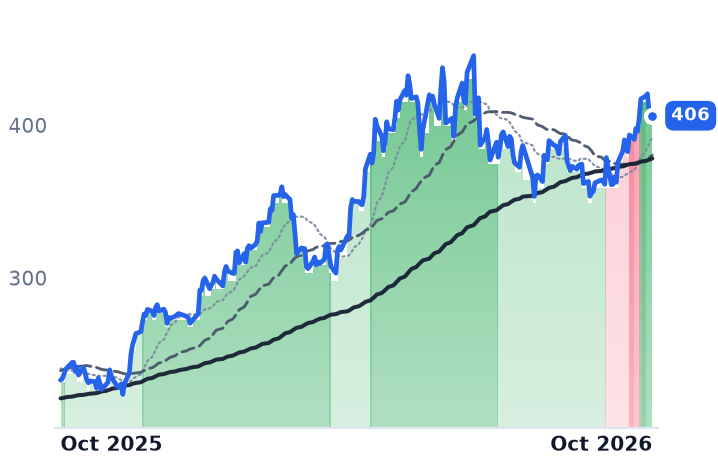
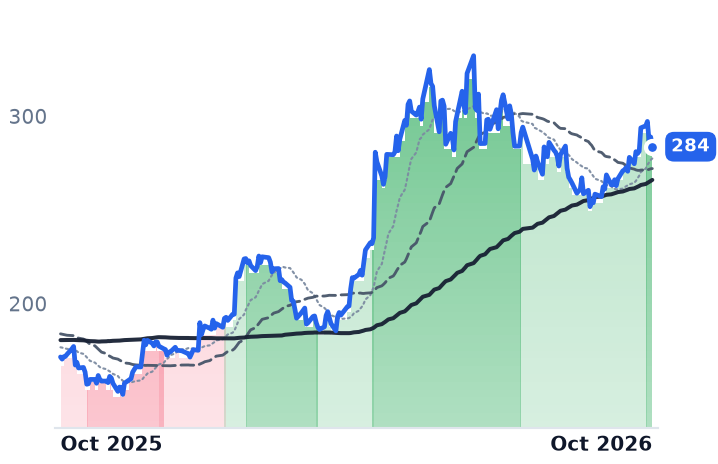
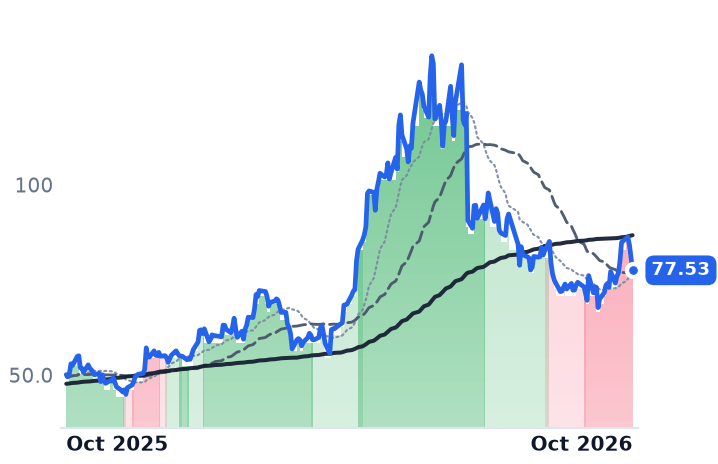
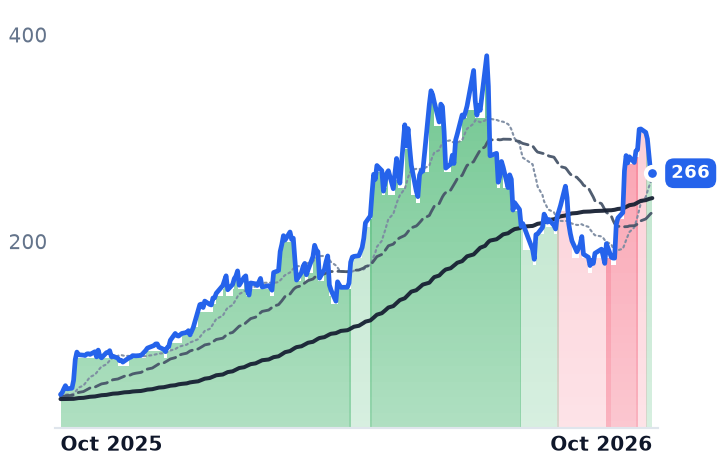
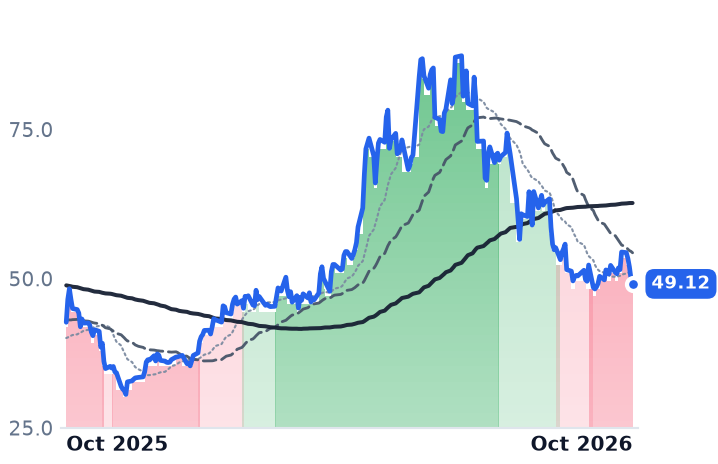
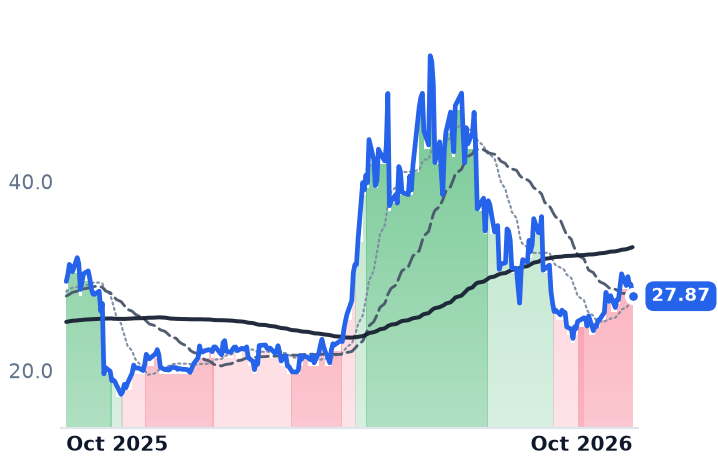
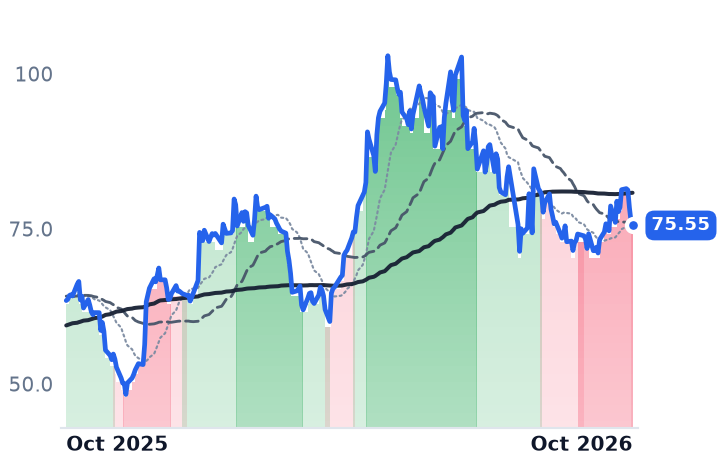
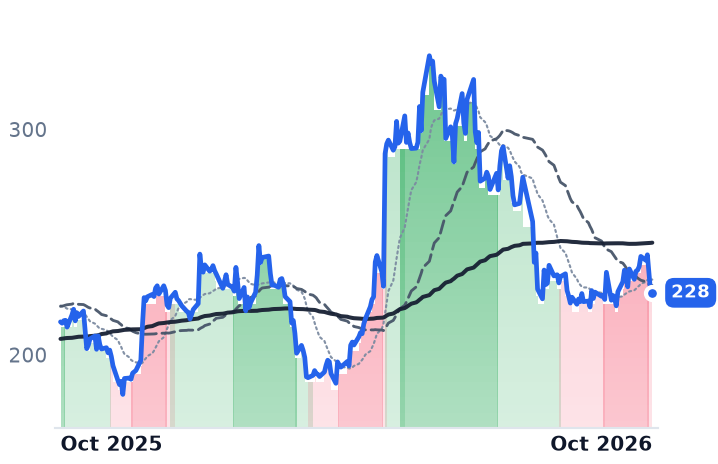
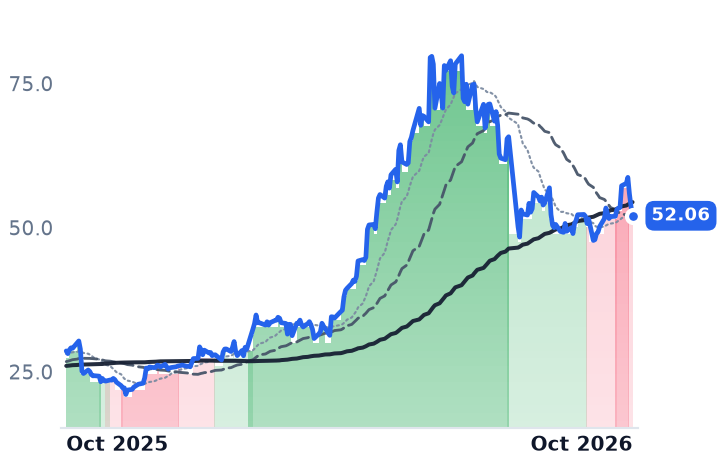
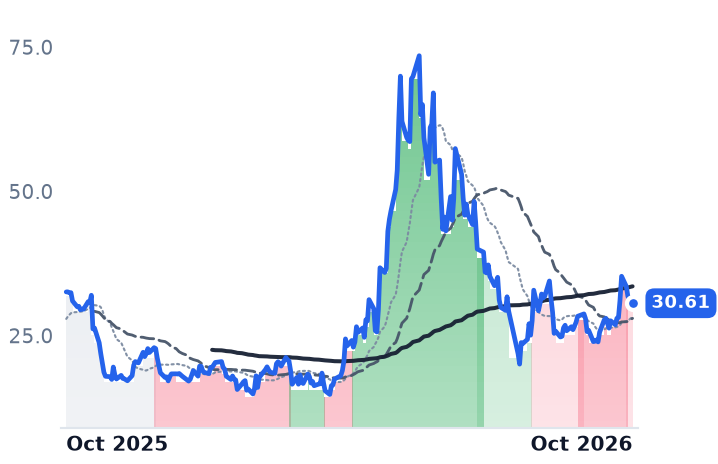
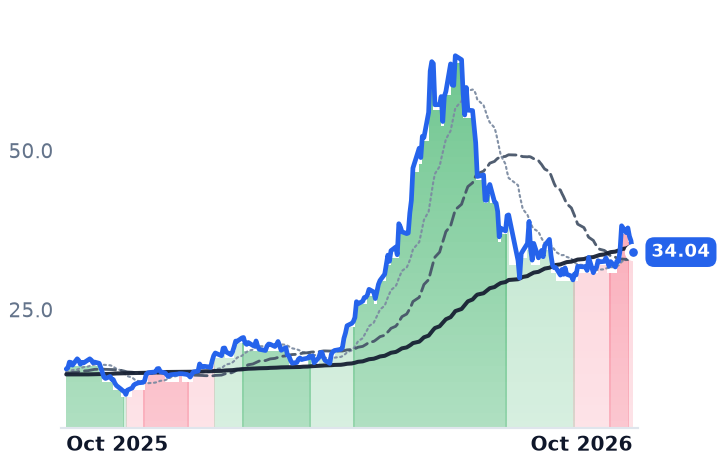
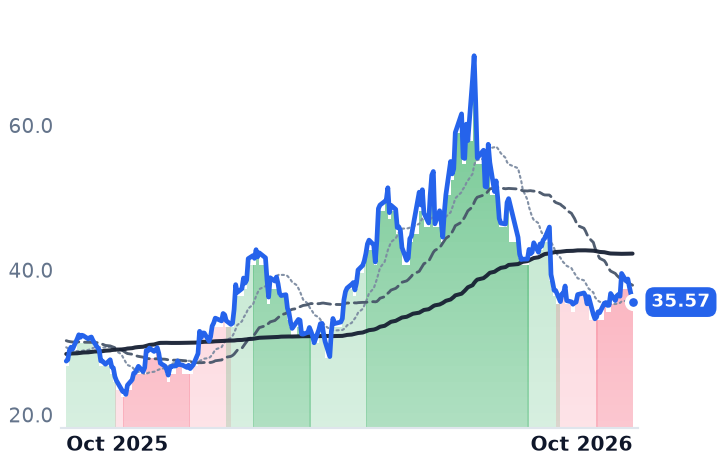
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $68.1B | 84.5x | 50.5x | 20.8x | 16.4x | 37.7x | 29.7x | 64.3x | 0.9% |
NVTS | $2.8B | n/m | — | 77.0x | 59.0x | — | — | n/m | -2.4% |
ADI | $197.8B | 48.0x | 31.6x | 14.3x | 13.1x | 21.7x | 19.9x | 29.2x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXN | $259.1B | 42.9x | 33.3x | 13.3x | 11.8x | 22.8x | 20.3x | 27.9x | 2.1% |
ON | $33.0B | 53.7x | 26.5x | 5.3x | 5.0x | 14.2x | 13.5x | 26.9x | 5.4% |
VICR | $12.1B | 83.4x | 67.6x | 25.4x | 19.0x | 44.9x | 33.6x | 87.3x | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWI | $3.5B | 136.5x | 44.7x | 7.7x | 7.2x | 14.4x | 13.5x | 84.1x | 2.3% |
AOSL | $929.9M | n/m | — | 1.4x | 1.3x | 6.1x | 5.9x | n/m | -1.8% |
MCHP | $41.0B | 104.7x | 20.8x | 8.0x | 6.4x | 13.3x | 10.7x | 27.4x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXPI | $57.5B | 19.4x | 15.1x | 4.4x | 4.0x | 7.8x | 7.2x | 13.3x | 5.1% |
STM | $49.8B | 107.2x | 41.7x | 3.7x | 3.5x | 10.9x | 10.1x | 22.5x | 0.8% |
WOLF | $1.8B | n/m | — | 2.8x | 2.9x | — | — | n/m | -19.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VSH | $5.4B | 147.2x | 45.3x | 1.3x | 1.5x | 6.2x | 6.9x | 14.3x | -0.1% |
ALGM | $6.8B | 448.3x | 35.3x | 7.2x | 6.2x | 15.2x | 13.1x | 66.3x | 1.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MPWR | Revenue | +49.3% | +28.9% | +20.5% |
| EPS | +55.0% | +31.2% | +20.6% | |
NVTS | Revenue | +4.7% | +52.5% | +59.8% |
| EPS | −21.9% | −17.9% | −44.8% | |
ADI | Revenue | +37.8% | +22.1% | +11.6% |
| EPS | +65.8% | +29.4% | +18.0% | |
TXN | Revenue | +24.0% | +13.8% | +10.6% |
| EPS | +55.6% | +20.7% | +17.1% | |
ON | Revenue | +9.2% | +13.1% | +13.9% |
| EPS | +37.1% | +40.9% | +30.2% | |
VICR | Revenue | +40.0% | +52.9% | +22.8% |
| EPS | +82.0% | +61.4% | +31.5% | |
POWI | Revenue | +7.7% | +14.2% | +20.8% |
| EPS | +14.8% | +34.8% | +43.0% | |
AOSL | Revenue | −1.9% | +4.4% | +18.5% |
| EPS | −479.7% | −9.8% | −332.6% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
NXPI | Revenue | +16.7% | +11.5% | +8.3% |
| EPS | +28.0% | +20.5% | +15.3% | |
STM | Revenue | +22.4% | +18.7% | +13.2% |
| EPS | +104.2% | +98.3% | +45.6% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
VSH | Revenue | +21.1% | +15.7% | +10.4% |
| EPS | −2763.2% | +111.4% | +48.1% | |
ALGM | Revenue | +23.0% | +24.3% | +17.3% |
| EPS | +131.1% | +93.4% | +46.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Navitas Semiconductor closed its purchase of Claros on 6 October, paying up to $232.8m — about $216.0m at closing, roughly $125m of it cash — for the ability to put a voltage regulator directly beneath a high-current processor. That capability, integrated voltage regulation and vertical power delivery, is the last stage in an AI rack's power chain, and it is the stage Monolithic Power Systems already supplies.
The market spent September deciding Monolithic was losing it. A research note questioning the company's allocation on Nvidia's next platform cost the shares 7.39% in the 14 September session, from $1,234.46 to $1,143.24 on 978,292 shares against the 68,339 traded six sessions earlier. The filings published six weeks before that say nothing of the sort about the business as it stands. The reason both can be true is structural: a power-semiconductor dollar is earned in a way the revenue line cannot read back.
The dollar arrives late, and through someone else
Monolithic, a Kirkland, Washington designer of DC-to-DC converters that step voltage down for servers, cars and industrial gear, is paid for content on a board that was designed years before it shipped. It is also paid at one remove: 88% of sales in both the three and six months to 30 June 2026 ran through distribution arrangements whose enforceable rights and obligations are with distributors and resellers, not end customers, and two of those distributors were 28% and 15% of revenue. Reported revenue is, to that extent, a distributor ordering pattern.
What it reported was acceleration. June-quarter revenue of $980.6m grew 47.6% year on year, the fourth straight quarter of faster growth, and Enterprise Data revenue rose 164.3% to $380.6m, lifting that end market to 38.8% of the company from 32.7% a quarter earlier. Operating margin went to 31.0% from 24.8%. GAAP gross margin has sat within 23 basis points of 55.2% across four quarters. Days of inventory fell 17, to 140.
On the 30 July call, management said channel inventory "remains very low" and book-to-bill was "well above 1.0x." Founder-chief executive Michael Hsing raised the year's floor for the segment: "I think right now, based on what we can see, we're willing to raise the floor for that particular end market from 85% for the year to 130% for the year," he told investors.
The number nobody discloses
The quarterly release breaks out revenue by end market against a single consolidated gross margin. There is no margin by segment, and there is no disclosure anywhere of how many of the power phases on a given accelerator board are Monolithic's rather than a second source's. That is the quantity in dispute. Rosenblatt, cutting the stock to Neutral, allowed that Monolithic is "capturing the pole position in power delivery to accelerator sockets" while arguing Nvidia's roadmap looks to have Texas Instruments and perhaps Analog Devices in the Rubin cycle. Its $880 target, set on an assumed $22 of fiscal 2026 earnings per share, now sits far below both the $1,386.29 price and the $27.45 consensus — a stale price view carrying a live competitive observation.
By the time a lost phase reaches the income statement, the platform carrying it has already shipped.
The other side of the socket
Navitas is what the same end market looks like before the revenue arrives. June-quarter revenue of $10.5m fell 27.3% year on year; GAAP gross margin was 0.4% including about $4m of intangible amortisation, 39.5% on a non-GAAP basis, and the non-GAAP operating loss was $11.4m. Diluted shares rose 18.6% in twelve months, and the company ended June with $557.4m of cash after raising roughly $373m in the quarter — the cash half of the Claros price consumes about a fifth of that. Chief executive Chris Allexandre has said AI infrastructure will exceed a third of revenue by year-end, which is a real share of a $36.5m trailing base priced at 77 times sales. The 800-volt in-rack date moved to early 2028 at Citi's conference on 8 September, from 2027 on the July call, and the joint 800-volt reference design with Microchip unveiled 5 October is a demonstration rather than a volume agreement.
Analog Devices shows the third route: buy in and carry it on a diversified book. It paid $1.5bn for Empower Semiconductor, grew August-quarter revenue 39.6% to $4.022bn at a 67.3% gross margin, and trades at 31.6 times forward earnings against Monolithic's 50.5 times.
What September was arguing about
Monolithic's shares are 18% below their 3 June peak of $1,689.89, flat over three months, and up 14.7% in thirty days inside a sector-wide advance — the iShares Semiconductor ETF gained 11% in September. The results account for essentially none of the drawdown and the valuation accounts for most of it: 84.5 times trailing earnings and 37.7 times trailing gross profit, against the roughly 39 times gross profit that already sat at the top of the range in August. The dispute is about the price, not the reported business.
What the dispute cannot be settled by is another quarter like the last one. On 29 October the company reports a period already guided to $1,140m–$1,160m of revenue, roughly a sixth above June, at a gross margin of 55.2%–55.8%. The figure that decides the next three years is not in that release, and will not be in any release until the boards it describes are already in racks.