

Software's AI Scare Reversed Without Checking Whose Subscriptions Were Growing
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Five software companies filed under the same vertical-software label bill customers on completely different meters — a bank's asset size, a contractor's construction volume, seats, cloud consumption, the monthly accounting close — and since April the market has repriced them as one thing.
Appian's cloud subscription revenue grew 23% in the June quarter, its fastest in more than two years. Freshworks' net dollar retention slipped to 104%, the only retention figure of the five going the wrong way. Both shares rose by roughly similar amounts over six months, and Appian's price against trailing gross profit went from 3.07x in May to 5.10x while gross profit grew 14.2%.
Appian and Procore, whose backlog due within a year grew 22%, have results behind them. Freshworks does not, nCino's subscription line is slowing, and BlackLine's 6% annual recurring revenue growth explains why it was left out of the rally.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
APPN | Appian | Developer Platforms & APIs | 🌱 Emerging Bull | +15.4% | +40.6% |
NCNO | nCino | Commerce & Digital Payments | 🌱 Emerging Bull | −7.2% | −20.2% |
PCOR | Procore Technologies | Industry-Specific Platforms | 🔴 Cont. Bear | +5.5% | −21.7% |
| Compared against · context, not the story | |||||
BL | BlackLine | Other | 🔴 Cont. Bear | +5.0% | −40.7% |
FRSH | Freshworks | Sales, Service & Customer Management | 🟢 Cont. Bull | +17.1% | +23.7% |
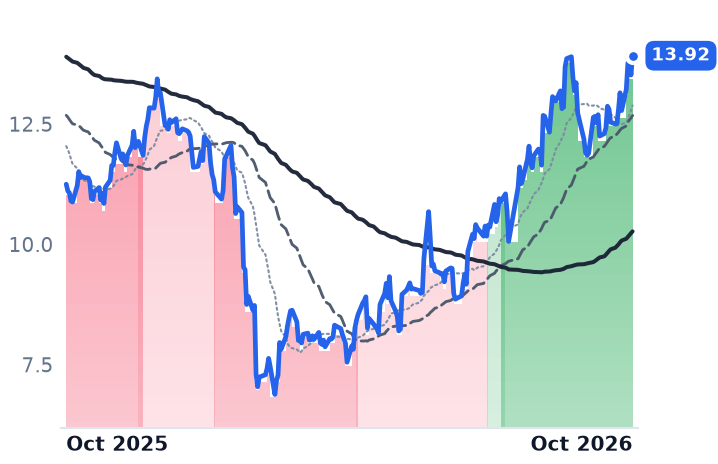
12-month price & trend
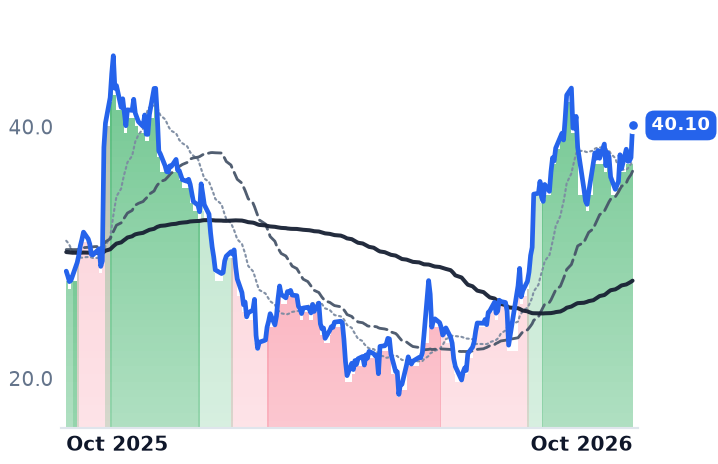
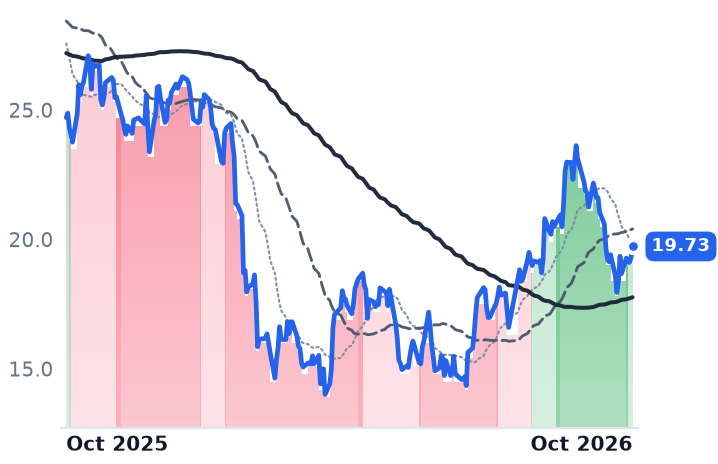
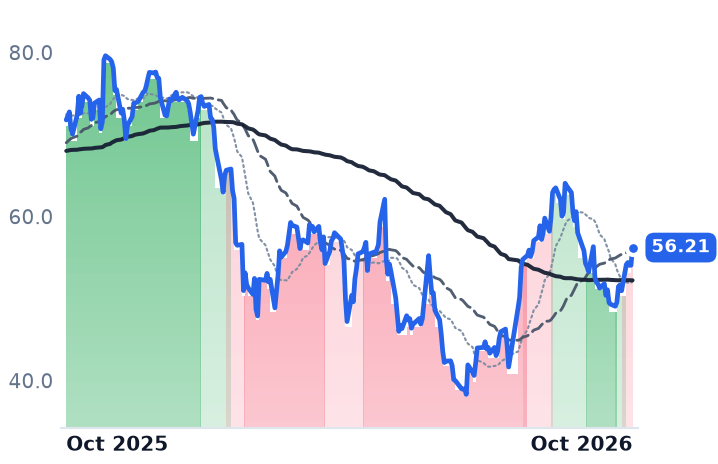
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPN | $3.0B | n/m | 37.1x | 3.7x | 3.5x | 5.1x | 4.8x | 140.7x | 2.6% |
NCNO | $2.2B | 63.6x | 15.1x | 3.5x | 3.3x | 5.6x | 5.4x | 26.1x | 6.1% |
PCOR | $9.4B | n/m | 36.6x | 6.6x | 6.2x | 8.2x | 7.7x | 147.7x | 3.1% |
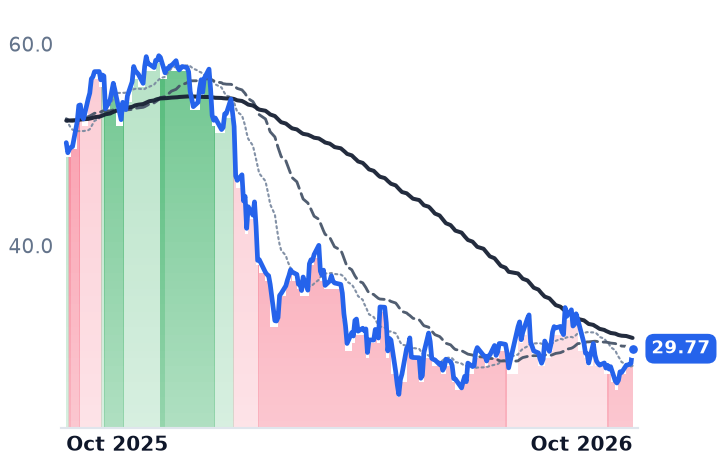
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BL | $1.7B | 49.8x | 11.8x | 2.3x | 2.2x | 3.1x | 3.0x | 21.4x | 9.9% |
FRSH | $3.8B | 21.2x | 20.8x | 4.3x | 4.0x | 5.0x | 4.7x | 47.3x | 6.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APPN | Revenue | +19.1% | +10.8% | +7.4% |
| EPS | +104.0% | +31.1% | +11.4% | |
NCNO | Revenue | +9.8% | +9.0% | +8.5% |
| EPS | +25.2% | +44.5% | +20.0% | |
PCOR | Revenue | +15.3% | +13.9% | +14.4% |
| EPS | +24.2% | +46.2% | +19.0% | |
BL | Revenue | +9.5% | +10.4% | +10.3% |
| EPS | +19.7% | +10.9% | +18.0% | |
FRSH | Revenue | +15.6% | +14.2% | +15.4% |
| EPS | +5.4% | +24.0% | +18.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Appian's cloud subscription revenue grew 23% in the June quarter, the fastest pace in more than two years, and the low-code automation company swung to positive operating cash flow. The professional-services arm that a turnaround story usually shrinks grew 20% as well, and gross margin fell.
April's selloff was read as a verdict on business models: artificial intelligence would let customers assemble their own applications, and software vendors with no infrastructure of their own would be hollowed out. The S&P 500 software and services index fell more than 26% from late January to its April low, then posted its biggest July-to-September quarterly gain since the second quarter of 2020, closing on 6 October at its highest since November 2025. If the recovery were a repricing of software paid off a customer's volumes instead of its headcount, the five names shelved together as vertical vendors would have separated by now. They have not. Their subscription meters have.
Five companies, five different bills
nCino, which sells banks and credit unions a platform for onboarding, lending and deposit accounts, left seat pricing in fiscal 2025 for tiers set by a client's asset size, saying the aim was "aligning its revenues to the usefulness the nCino Platform provides"; its contracts are non-cancellable and typically run three to five years. Procore, whose platform runs preconstruction, project and financial management for owners and contractors, invoices a year upfront against the construction volume a customer manages on it, and passed $1 trillion of annual contracted volume as of its third-quarter 2025 results, so cash and backlog move before revenue.
Appian sells a consumption-priced cloud subscription plus the services to stand up a customer's first workflows, competing with Pegasystems, Microsoft's Power Platform and the tier above it, ServiceNow. Freshworks sells seats of help-desk and information-technology service software. BlackLine sells the monthly accounting close.
Appian and Procore brought results; the multiples went further
Appian's cloud subscriptions reached $131.7m and adjusted EBITDA came in at $16.2m against guidance of $5m to $8m; operating cash flow was $12.1m against $1.9m used a year earlier, and full-year cloud guidance went to $525m–$529m. Cloud net annualized recurring revenue expansion was 115%, against 113% a year earlier and 115% the prior quarter. Services revenue of $45.6m held a flat 22.4% of the total, gross margin compressed 305 basis points to 71.2%, and group gross profit grew 14.2% — while the price against trailing gross profit went from 3.07x in May to 3.63x in late July to 5.10x now, a 66% expansion.
Morgan Stanley has not endorsed that move: Overweight with a $45 target in January, cut to Equal-Weight on 30 April with the target to $25, then lifted to $32 in August.
Procore is the one case where the forward meter outran the reported one. Current remaining performance obligation reached $1,072.5m, up 22% against 15.8% revenue growth, accelerating by 100 basis points, with 58% of the $193m increase from customers won in the prior twelve months. Operating income turned positive at $4.3m on a generally accepted accounting principles basis, from a $30.3m loss. Underneath it, US construction starts ran 15.2% higher year-to-date through August, with nonresidential starts up 23.4%. Procore trades at 7.47x trailing gross profit, below the 7.96x of early May.
A mortgage rate and a stalled base
nCino's revenue grew 8% and subscription revenue 10%, or 12% excluding US mortgage — the mortgage book is subtracting roughly two points, with rates above 7% against the Mortgage Bankers Association's 6% to 6.5% forecast for 2026. Third-quarter guidance implies 7% to 8% growth at the midpoints. "We are seeing many of our largest customers consolidating more of their most critical operations on nCino," chief executive Sean Desmond said on 25 August, alongside a $100m repurchase program. The shares are rated about where they were: 5.65x trailing gross profit against 5.52x in May.
BlackLine is the one that behaved. Annual recurring revenue of $719m grew 6%, net revenue retention was 102.4% and current remaining performance obligation grew 11% — the weakest meters of the five. "I believe the first half of 2026 will prove to be the most consequential period in BlackLine's history," chief executive Owen Ryan told investors. At 3.16x trailing gross profit and a 9.75% trailing free cash flow yield it is the cheapest here, and the cheapness is doing rational work.
The proof is Freshworks
Freshworks' net dollar retention fell to 104% from 106% on 16% revenue growth, and its price against trailing gross profit rose 55% from 3.24x in May to 5.01x — the same order of re-rating as Appian's, on the only retention number here that is deteriorating. Over the six months to 9 October the seat-priced vendor rose 84% and Appian 98%, while Procore gained 19% and nCino 13%.
So the accelerations are real at two of the five, and the repricing did not depend on them. Expected 2026 earnings growth for the software sector has climbed to 20.6% from 13.8% at the end of March, and that reset is the likelier common factor. "AI has been more of an enabler for a lot of these software companies, more than a disruptor," Adam Turnquist, chief cross-asset strategist at LPL Financial, said of the move.
The last month supports that reading. Appian and Freshworks have held their uptrends; Procore rolled over in September and nCino fell about 10% in thirty days, the opposite of what a durable re-rating of volume-indexed revenue would look like.
None of these companies has spoken since August. Appian reports again on 5 November, and the number that matters is not the revenue line it prints but whether customers kept expanding faster than they lapsed once the sector stopped doing the lifting.