

A Licence That Lets the Buyer Shop Elsewhere Raised Vicor's Quarterly Guidance Twice
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Vicor told investors on 30 September that a single non-exclusive patent licence would carry third-quarter revenue growth past 30% sequentially — the second upgrade to the same quarter in nine days, both attributed to royalties rather than shipped hardware. The audited test of that claim arrives on 20 October.
Royalties were $30.4m of the June quarter's $143.4m of revenue and carry almost no cost of sales. The hardware is not the weak part: product revenue grew 31.8% year on year and one-year backlog rose 26% to $379.7m. But the incremental dollar now comes from a legal docket, and the licensee may buy the covered modules from other suppliers.
On the same 800-volt supplier list, Navitas has produced no gross profit across four quarters; Bel Fuse, which actually ships data-center magnetics, saw that line grow 55%.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
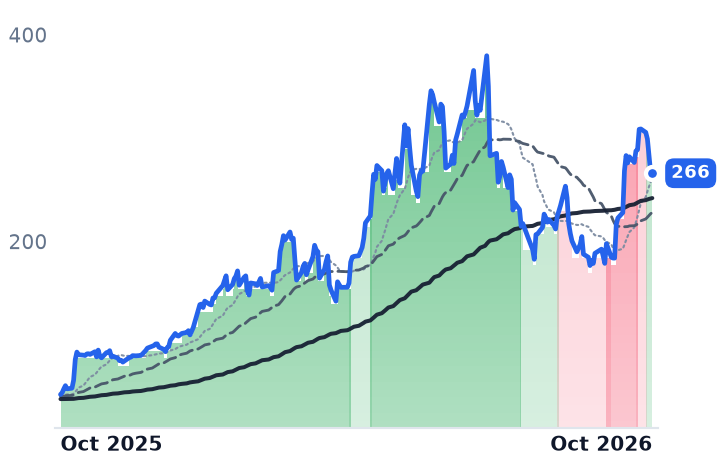
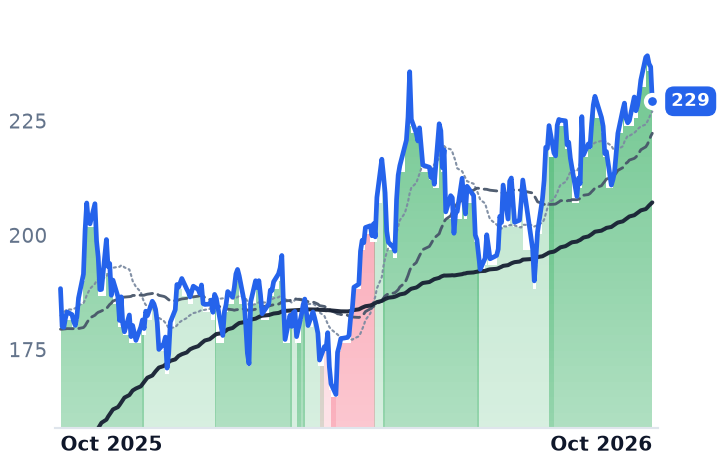
VICR | Vicor | Other | ⚠️ Emerging Bear | +34.4% | +412.1% |
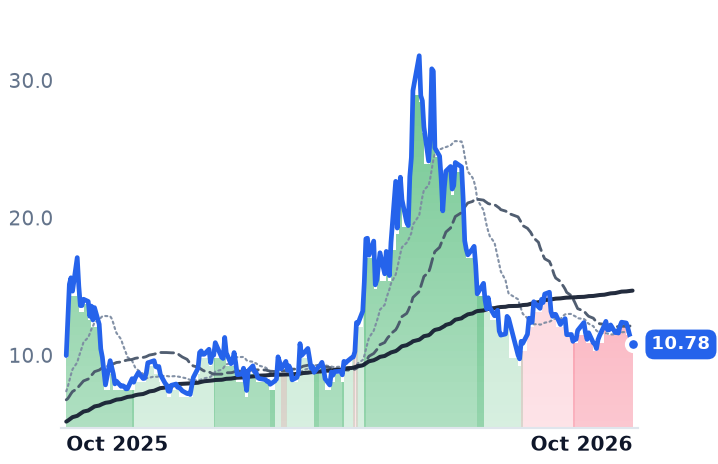
NVTS | Navitas Semiconductor | Other | ⚠️ Emerging Bear | −7.3% | +8.1% |
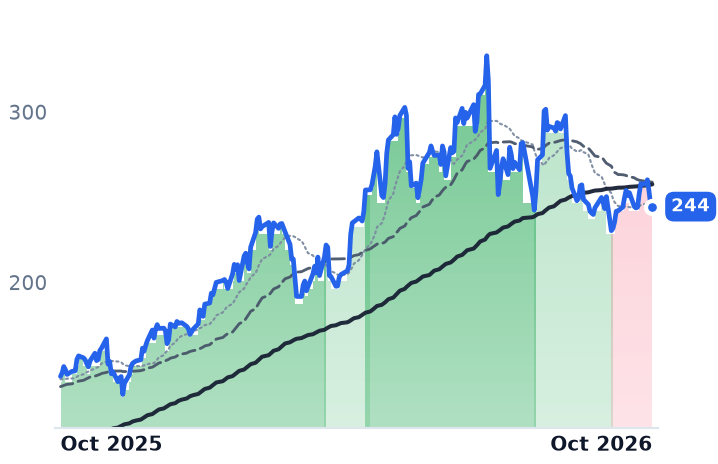
BELFB | Bel Fuse | Connectors & Interconnect Systems | 🟢 Cont. Bull | −2.3% | +68.8% |
| Compared against · context, not the story | |||||
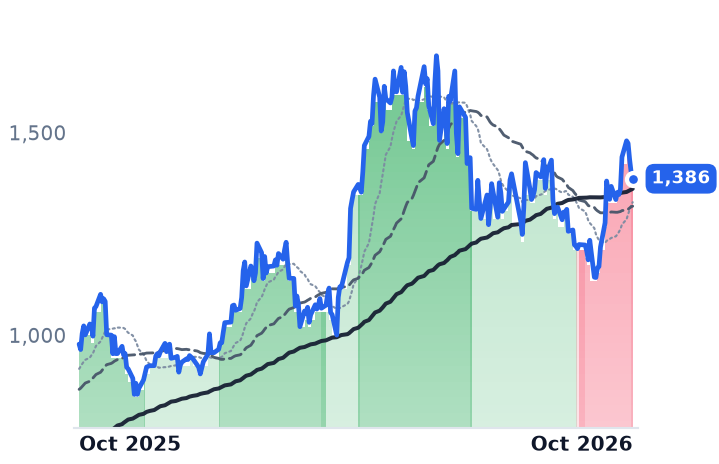
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | +12.3% | +41.7% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +5.0% | +21.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VICR | $12.1B | 83.4x | 67.6x | 25.4x | 19.0x | 44.9x | 33.6x | 87.3x | 0.4% |
NVTS | $2.8B | n/m | — | 77.0x | 59.0x | — | — | n/m | -2.4% |
BELFB | $3.0B | 61.1x | 24.8x | 4.0x | 3.7x | 10.1x | 9.2x | 20.7x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $68.1B | 84.5x | 50.5x | 20.8x | 16.4x | 37.7x | 29.7x | 64.3x | 0.9% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VICR | Revenue | +40.0% | +52.9% | +22.8% |
| EPS | +82.0% | +61.4% | +31.5% | |
NVTS | Revenue | +4.7% | +52.5% | +59.8% |
| EPS | −21.9% | −17.9% | −44.8% | |
BELFB | Revenue | +20.7% | +8.5% | +13.8% |
| EPS | +45.9% | +13.7% | +22.9% | |
MPWR | Revenue | +49.3% | +28.9% | +20.5% |
| EPS | +55.0% | +31.2% | +20.6% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vicor raised the revenue guidance for a single quarter twice inside nine days, and neither raise came from a module leaving a loading dock. The Andover, Massachusetts maker of brick-format DC-DC converters and custom power systems told investors on 30 September that third-quarter revenue would grow more than 30% sequentially, up from the "more than 20%" it had promised on 21 September, which in turn replaced nearly 10%. Both increases were attributed to higher royalties from one agreement. From the $143.4m June base, more than 30% implies a quarter above roughly $186m.
The market has treated the sequence as proof that Vicor's power-delivery hardware is winning sockets in artificial-intelligence racks. The company's own releases say something narrower: it is being paid for permission. The agreement behind both raises, signed on 16 September, licenses Vertical Power Delivery — the topology that pushes current up into the processor from below — to an unnamed artificial-intelligence equipment maker on a non-exclusive basis, and expressly permits the licensee to buy the covered modules from third-party suppliers Vicor does not supply.
The royalty is scheduled, the leverage is a docket
Royalties were $30.4m, or 21.2%, of June-quarter revenue, the company disclosed on 21 July, of which an earlier agreement contributed $15m, with $5m set for the third quarter and $10m in each of the four quarters after that. That is a payment calendar rather than an order book, and because royalties carry essentially no cost of sales they drop almost whole into operating income. Net income of $49.8m exceeded operating income of $34.9m in the June quarter, so roughly 30% of the bottom line was earned below the operating line.
What creates the calendar is enforcement. In February 2025 the U.S. International Trade Commission upheld two Vicor patents and barred importation of unlicensed computing systems containing infringing power modules, with cease-and-desist orders against Delta Electronics and Quanta Computer entities. "Since the first patent to VPD was only recently asserted, it is still possible to secure a license at an early stage of escalation with a low royalty rate," chief executive Patrizio Vinciarelli said in the 21 September release.
The docket also runs the other way. The same determination found two Foxconn affiliates licensed to one patent through boilerplate in purchase orders for Vicor components, a ruling Vicor is appealing, and a second investigation naming Luxshare, Hon Hai, Delta, Quanta, Monolithic Power, Infineon, Flex and Celestica carries a target completion date of 20 September 2027.
The hardware is not the problem; the price is the question
Product revenue of $112.9m grew 31.8% year on year, book-to-bill ran above one and one-year backlog rose 26% sequentially to $379.7m. Reported gross margin nonetheless fell from 65.3% to 58.0%, consistent with a larger royalty share a year earlier rather than with product-margin decay.
Shares rose 68.0% from $183.91 on 16 September to $308.90 on 2 October, then gave back 13.9% to $266.07 on 9 October alongside the 7 October selloff in artificial-intelligence names and 24-year-high long Treasury yields. At 83.4x trailing earnings the stock is dearer than almost anything in power components, yet cheaper on gross profit than it was in May 2026 at a similar price: 44.9x against 61.8x. Earnings grew into the multiple. A third of the forward growth consensus embeds is contracted royalty income.
The contrast on the same Nvidia 800-volt supplier list is what makes the licence remarkable. Navitas, a fabless designer of gallium-nitride and silicon-carbide power chips, reported $10.5m of revenue for the June quarter, down 27.3%, with cumulative negative gross profit across four quarters and 77.0x trailing sales to carry; its in-rack 800-volt content is dated to 2027 and later. Bel Fuse, which makes magnetics, connectors and power supplies rather than chips, grew its data solutions line 55% to about $58m and sits on 24.8x forward earnings against consensus earnings growth of 45.9%, with no long-term debt — and its shares are down 10.3% over three months.
Vicor is the only one of the three whose third-quarter number is already half-written, and it was written by lawyers. The print lands at 7:00am Eastern on 20 October, and the line investors will read first is not shipments.