

Borr Drilling Sold Rig Days Cheaper to Stay Busy While Its Chairman Bought $17.5m of Stock
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Borr Drilling's new jackup contracts are being written at roughly $123,000 a day, about 8% under the $134,000 average on the 2026 rig-days it had already sold. That is where a softening shallow-water market shows up, and it is invisible in the revenue line.
Volume says the opposite. Backlog of $1.13bn in dayrate-equivalent terms is rising, rigs worked 98.4% of scheduled time in the June quarter, and the suspended Saudi jackups that scared the market went back to work in August. Meanwhile consensus cut Borr's 2026 EBITDA to $173.6m, a 60% fall, and chairman Tor Olav Trøim bought about 4.15m shares at $4.13 to $4.38.
Noble shares the shelf label but not the market: its floaters fell to 61% contracted from 68% while its five North Sea jackups climbed to 80%.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
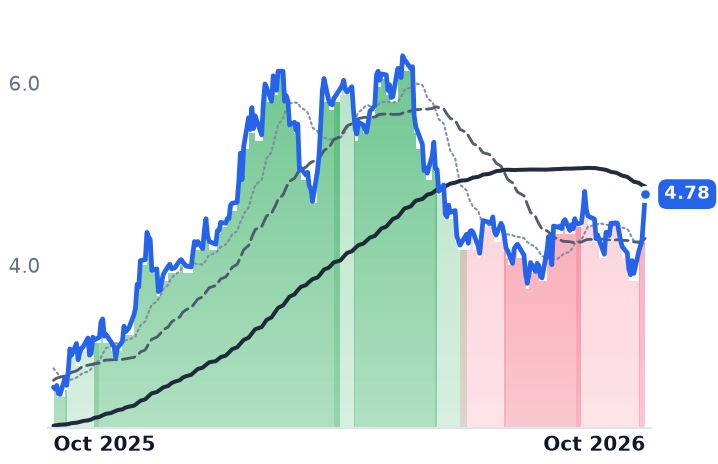
BORR | Borr Drilling | Offshore Shallow-Water Jackups | 🔴 Cont. Bear | +11.9% | +79.7% |
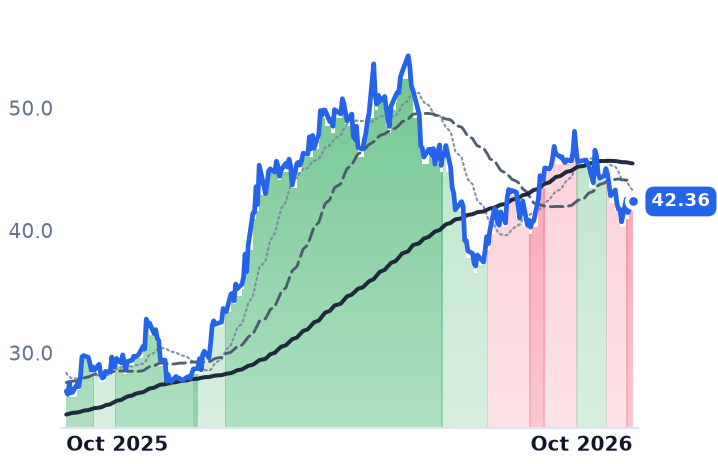
NE | Noble | Offshore Shallow-Water Jackups | ⚠️ Emerging Bear | −6.4% | +57.6% |
| Compared against · context, not the story | |||||
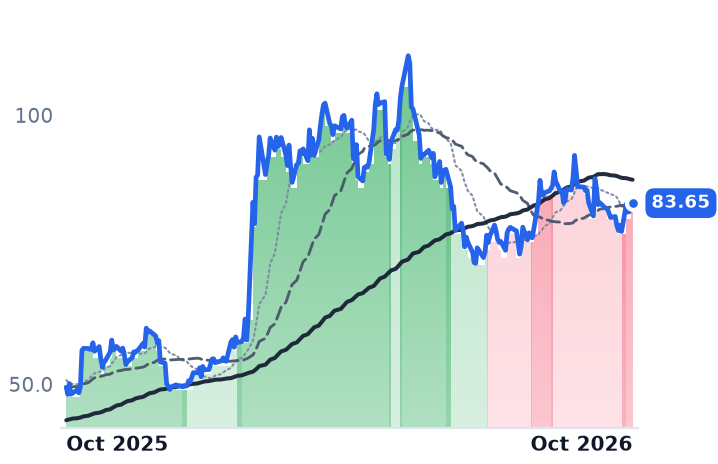
VAL | Valaris | Drilling & Rig Services | 🔴 Cont. Bear | −0.1% | +69.2% |
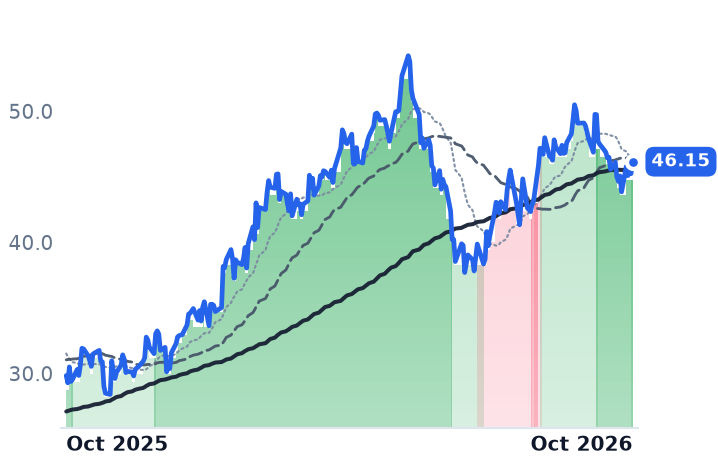
SDRL | Seadrill | Offshore Deepwater Floaters | 🟢 Cont. Bull | −3.7% | +54.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BORR | $1.5B | n/m | — | 1.4x | 1.5x | 4.8x | 4.9x | 10.2x | -10.0% |
NE | $6.8B | 44.6x | 76.9x | 2.2x | 2.3x | 8.3x | 8.8x | 9.0x | 4.2% |
VAL | $5.8B | 6.2x | 27.6x | 2.7x | 2.7x | 6.6x | 6.5x | 10.6x | -0.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SDRL | $2.9B | — | 58.5x | 1.9x | 1.8x | 7.6x | 7.4x | 9.1x | -9.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BORR | Revenue | −1.0% | +20.5% | +12.8% |
| EPS | −575.3% | −116.3% | +310.7% | |
NE | Revenue | −10.9% | +11.4% | +10.0% |
| EPS | −46.2% | +292.6% | +67.5% | |
VAL | Revenue | −6.4% | +13.6% | +2.1% |
| EPS | −37.3% | +131.8% | +14.7% | |
SDRL | Revenue | +11.0% | +10.4% | +0.8% |
| EPS | −307.8% | +347.8% | +16.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Borr Drilling, which owns a fleet of modern jack-up rigs and rents them with crew to oil companies in shallow water, added three more contract commitments on 6 October and watched its chairman spend roughly $17.5m buying its own shares through late September and early October. Both arrived while the price of new work sat below what the working fleet already earns.
That gap is the only honest read on this market, because an offshore driller is paid a dayrate multiplied by contracted operating days, recognised against contracts signed one to three years earlier. Revenue can hold long after rates break, and it can fall while the market tightens. The four weeks since Borr's shares were last at $4.12 have been read as the jackup cycle turning. What the filings show is a company deliberately buying occupancy with price.
The de-rating is in the rate, not the days
Borr's 21 contract commitments so far in 2026 — about 4,350 days and $541m of dayrate-equivalent value — were struck at an average of roughly $123,000 a day, against the $134,000 average on the 73% of 2026 rig-days already sold. New work is being signed some 8% under the rolling fleet rate.
The days themselves are piling up. Total backlog reached $1.13bn, with eight commitments and more than 2,100 firm days added since the prior report, then three more in October: a West African operator's binding letter of award for the Norve, roughly 245 days from mid-December; a one-well option exercised by Shell Nigeria on the Natt; and about 60 days of UK accommodation work for the Joro. Rigs worked 98.4% of scheduled time. Idleness is not the problem.
Price and cost are. Operating margin went from 36.0% in the June quarter of 2025 to 0.13% a year later, on revenue of $232.3m, down 13.2% and a third straight sequential decline. Adjusted EBITDA fell $44.7m sequentially to $43.8m, with $22.5m of that quarter's expense spent preparing the Odin for a US contract before it earned anything. Consensus now has 2026 EBITDA at $173.6m, a 60% fall and a further cut from the $183.4m carried a month ago, before a snap-back to $422.5m in 2027.
The company has said which of the two it is chasing: 2027 is when it plans to "turn focus again very sharply into economics and rates".
The bid came from inside
Borr rose 11.7% across the sessions of 8 and 9 October to $4.78. Noble gained 1.5% over the same two days, Valaris 1.9% and Seadrill 1.4%. Immediately before it, Drew Holdings, the vehicle of chairman Tor Olav Trøim, bought 1.5m shares on 5 October at an average $4.1314 and 1.25m more on 7 October at $4.3122, part of about 4.15m shares acquired since mid-September.
The demand case behind the buying is not imaginary. ADES Holding said on 11 August that all of its temporarily suspended Saudi offshore rigs had received resumption notices, with the suspensions event-driven rather than demand-driven; contracted jackup utilisation was holding near 90% in a market described as tight, with marketed supply roughly flat at about 405 rigs this year. Capacity came back, but earlier Aramco recalls were repriced at prevailing rates, which is consistent with Borr's $123,000.
Noble is a deepwater company on a shallow-water shelf
Noble's June-quarter revenue of $719.7m fell 15.2%, and the cause was floaters: contract drilling revenue dropped to $679m from $743m on the suspension of two rigs in Brazil, about $43m, and the end of the Globetrotter I's Black Sea work. Its 24 marketed floaters were 61% contracted, down from 68%. Its five ultra-harsh North Sea jackups went to 80% from 66%.
Its earnings sit in a $6.8bn backlog roughly equal to its $6.76bn market value, with four Guyana drillships extended to February 2029 under ExxonMobil's enabling agreement and a $0.50 quarterly dividend. Diluted shares rose from 152.9m to 161.0m since late 2024, so shrinking share count explains nothing about a stock down 7.4% in thirty days. At 9.00x trailing EV/EBITDA, Noble is the cheapest of the four offshore names on cash earnings and the only one with a positive free-cash-flow yield, at 4.2%.
What the quarter can and cannot explain
Almost none of Borr's October gain comes from reported results, which deteriorated again, or from forecasts, which were cut again. It comes from the chairman's purchases and from a Middle East market putting rigs back to work. The business evidence splits cleanly: days tightening, dollars per day loosening. Borr trades at 10.24x trailing EV/EBITDA and 1.53x book, the second-highest book multiple of the four and the only negative earnings among them; the market is paying marginally more per forward sales dollar than per trailing one, because consensus revenue falls 1%.
The clock on trading rate for utilisation is the balance sheet. "The new notes amortized at 5% per annum, equating to $101.75 million on a full year basis," chief financial officer Magnus Vaaler told investors on 12 August, with amortisation starting July 2027 on debt refinanced at 8.75% and 9.00%.
Chief executive Bruno Morand's case, made the same day, was that Middle East demand "was close to materializing prior to the onset of the conflict, and we believe this delayed activity should reenter the market once conditions stabilize." Conditions did stabilise, and the rigs came back. The question the 17 November print answers is what they came back at.