

Grand Canyon Education Traded $20m of Annual Revenue for a Fee Its University Cannot Cancel
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Education shares have been sold on the theory that the demographic cliff is arriving. The filings of the three largest listed operators describe two unrelated payers, only one of which is a student.
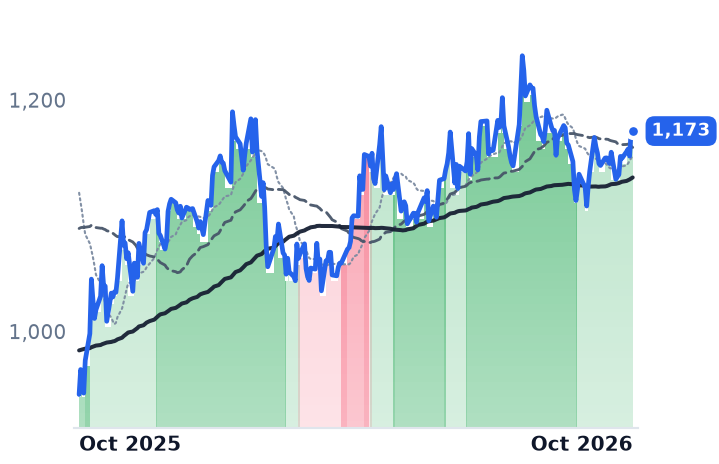
Grand Canyon Education rewrote its master services agreement with Grand Canyon University on 29 July 2026, surrendering roughly $20m of annual service revenue from housing, food and athletics fees in exchange for a term to 30 June 2041 and the removal of the university's right to walk away. The fee percentage, 60% of tuition and academic-related fees, did not move, and GCU has frozen tuition for an 18th year, so the base grows only on headcount: second-quarter revenue rose 6.7% on 7.5% more enrolled students. American Public Education owns its schools instead, drawing 41% of American Public University System's revenue from Pentagon tuition assistance with its 90/10 ratio at 89%. Only its de-rating has a business event under it, and that event is one quarter's phasing.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LOPE | Grand Canyon Education | Higher Ed Services & Operations | 🔴 Cont. Bear | +5.7% | −23.1% |
APEI | American Public Education | Higher Ed Services & Operations | ⚠️ Emerging Bear | +6.5% | +28.6% |
GHC | Graham | Higher Ed Services & Operations | 🟢 Cont. Bull | +3.0% | +24.1% |
| Compared against · context, not the story | |||||
PRDO | Perdoceo Education | Career & Technical Training | ⚠️ Emerging Bear | +2.1% | −1.3% |
STRA | Strategic Education | Higher Education Institutions | 🌱 Emerging Bull | +0.9% | +6.6% |
LINC | Lincoln Educational Services | Career & Technical Training | ⚠️ Emerging Bear | −6.1% | +11.1% |
UTI | Universal Technical Institute | Career & Technical Training | ⚠️ Emerging Bear | +1.6% | −32.0% |
COUR | Coursera | Online Learning Platforms | 🔴 Cont. Bear | −1.1% | −48.9% |
CHGG | Chegg | Education & Training Services | 🔴 Cont. Bear | +0.2% | −39.2% |
LAUR | Laureate Education | Higher Education Institutions | 🟢 Cont. Bull | +9.2% | +34.8% |
EDU | New Oriental Education & Technology | K-12 Tutoring (China) | 🟢 Cont. Bull | +5.0% | +12.6% |
TAL | TAL Education | K-12 Tutoring (China) | 🟢 Cont. Bull | +8.9% | +22.4% |
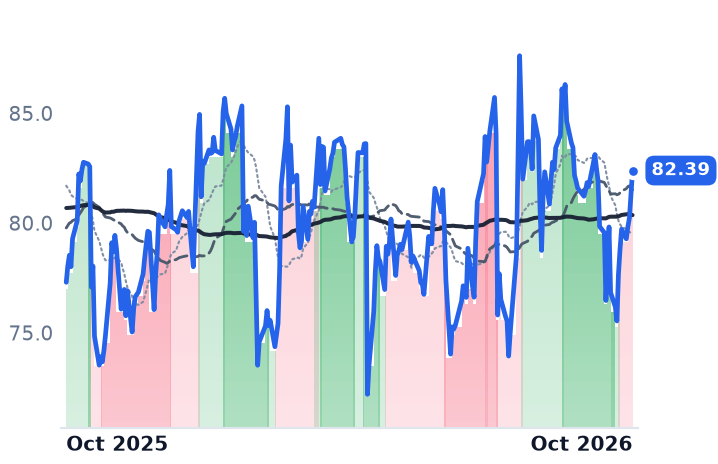
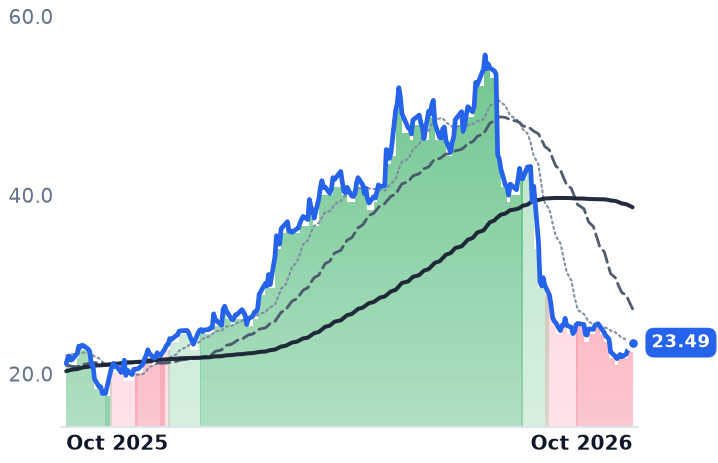
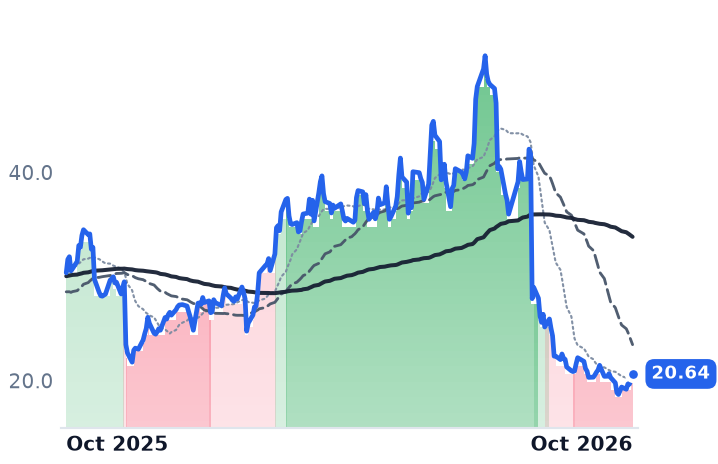
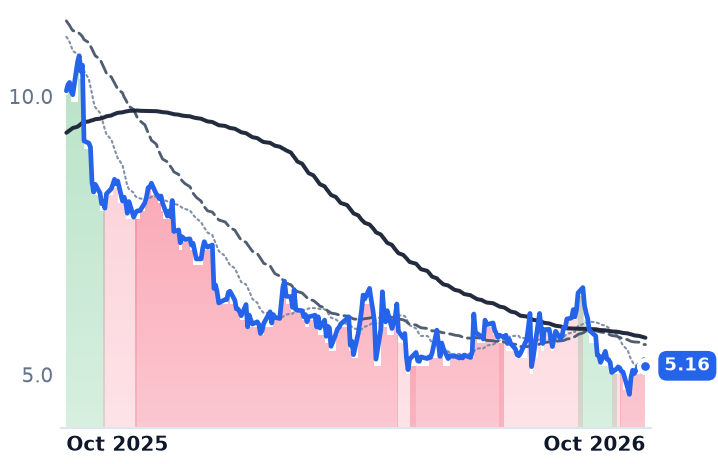
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LOPE | $4.2B | 19.2x | 15.6x | 3.6x | 3.6x | 6.8x | 6.7x | 12.5x | 5.8% |
APEI | $878.1M | 19.1x | 18.2x | 1.3x | 1.3x | 2.4x | 2.3x | 12.4x | 8.0% |
GHC | $5.1B | 9.4x | 17.0x | 1.0x | 1.0x | 3.5x | 3.4x | 6.7x | 4.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PRDO | $2.1B | 12.5x | 11.6x | 2.5x | 2.5x | 3.5x | 3.5x | 5.1x | 10.4% |
STRA | $1.8B | 13.1x | 11.0x | 1.4x | 1.4x | 2.9x | 2.8x | 7.6x | 9.7% |
LINC | $1.6B | 68.2x | 62.4x | 2.9x | 2.6x | 4.7x | 4.3x | 30.2x | -0.6% |
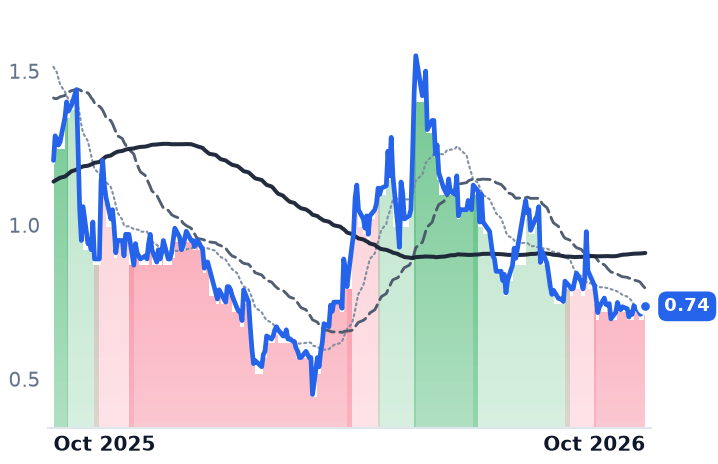
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UTI | $1.2B | 35.6x | 37.0x | 1.4x | 1.4x | 2.3x | 2.2x | 14.0x | -1.9% |
COUR | $893.9M | n/m | 12.8x | 1.2x | 1.1x | 2.1x | 2.0x | n/m | 9.4% |
CHGG | $88.2M | n/m | — | 0.3x | 0.4x | 0.6x | 0.7x | 3.0x | -0.9% |
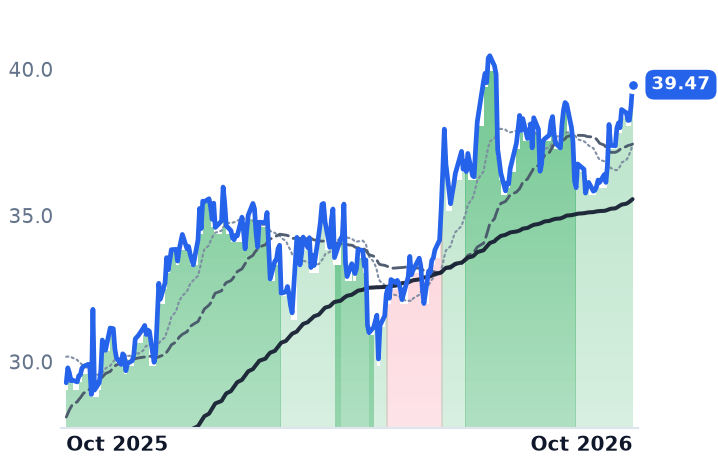
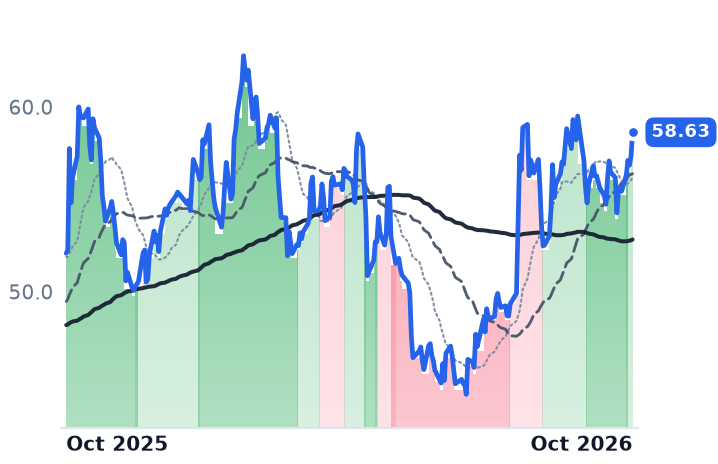
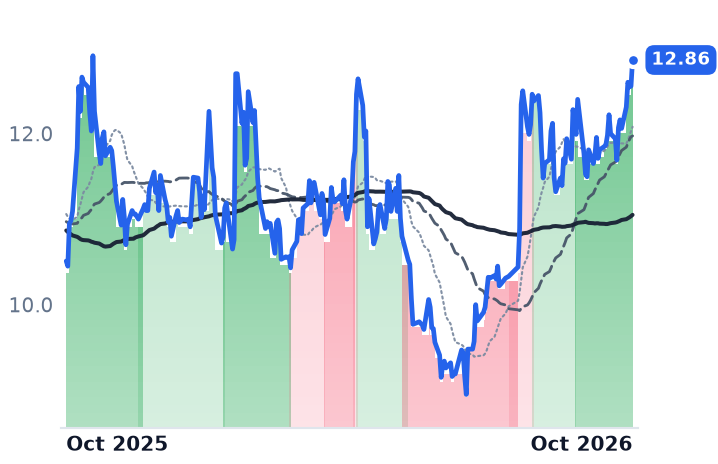
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LAUR | $4.5B | 16.3x | 15.0x | 2.6x | 2.4x | 9.6x | 8.7x | 9.8x | 5.9% |
EDU | $9.0B | 19.1x | 13.0x | 1.6x | 1.4x | 2.9x | 2.5x | 11.5x | 8.4% |
TAL | $7.8B | 2.6x | 9.0x | 2.4x | 2.1x | 4.3x | 3.7x | 8.4x | 8.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LOPE | Revenue | +5.6% | +6.1% | +5.8% |
| EPS | +12.4% | +10.8% | +9.2% | |
APEI | Revenue | +8.0% | +5.9% | +6.7% |
| EPS | +140.4% | +16.7% | +19.6% | |
GHC | Revenue | +4.9% | +4.0% | +7.4% |
| EPS | +34.5% | −2.9% | +43.3% | |
PRDO | Revenue | +2.6% | +2.8% | — |
| EPS | +23.7% | +7.9% | — | |
STRA | Revenue | +1.8% | +4.0% | +5.6% |
| EPS | +22.5% | +12.6% | +20.0% | |
LINC | Revenue | +17.1% | +9.0% | +9.4% |
| EPS | −4.1% | +50.2% | +20.2% | |
UTI | Revenue | +7.7% | +8.5% | +10.9% |
| EPS | −42.9% | +22.9% | +70.5% | |
COUR | Revenue | +7.8% | +6.2% | +1.5% |
| EPS | +5.3% | +27.8% | +37.5% | |
CHGG | Revenue | −45.2% | −21.3% | — |
| EPS | +61.4% | −50.0% | — | |
LAUR | Revenue | +13.3% | +7.2% | +7.8% |
| EPS | +28.1% | +14.5% | +16.2% | |
EDU | Revenue | +14.8% | +19.0% | +12.3% |
| EPS | +27.1% | +26.3% | +15.9% | |
TAL | Revenue | +31.9% | +25.5% | +17.6% |
| EPS | +188.3% | +125.1% | −13.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Grand Canyon Education does not own a university. It sells admissions and financial-aid counselling, marketing, learning technology and back-office finance to higher-education institutions, chiefly Grand Canyon University, the Phoenix nonprofit it sold itself out of in 2018, and it is paid a contractual percentage of what that university bills. On 29 July 2026 the two sides rewrote the contract. The amended and restated agreement re-bases the fee to 60% of GCU's tuition and academic-related fees alone, hands the revenue from student housing, food service, athletic tickets, the arena, hotel, golf course and apparel operations wholly back to the university, runs an initial fifteen-year term to 30 June 2041, and deletes GCU's right to terminate for convenience.
Management put the cost of the re-basing at about $20m of annual service revenue and less than $1m a quarter of operating income, because the ancillary revenue surrendered carried almost all of its own cost. That trade is the whole argument about this corner of the market. The weakness in education shares has been read as the demographic cliff arriving early; what the disclosures describe is a company whose revenue is one counterparty's billed tuition times a percentage it cannot reset, sitting beside a company whose largest payer is the Department of Defense.
A fee that can only grow on bodies
GCU has extended its tuition freeze for an 18th consecutive year. The counterparty that sets the base of the fee has chosen not to raise price, which leaves volume as the only lever. Second-quarter service revenue of $264.0m was up 6.7% on enrollments up 7.5%, to 121,921 students, of whom 113,011 study online. Divide the one by the other and the fee earned per enrolled student was about $2,166 against $2,182 a year earlier — a derived figure, and a falling one.
The margin came from cost discipline. Marketing and communication ran at 22.7% of revenue against 22.6%, counselling services at 33.4% against 33.5%, and operating income rose 12.3% to $58.2m, lifting the operating margin to 22.0% from 20.9%.
The smaller hybrid-campus business, which supports healthcare programmes for university partners, is capped by permits rather than appetite. Chief executive Brian Mueller's team told investors on 30 July that enrollment grew 8.5% across 47 active locations to nearly 6,000 students, that 14 locations are at or near capacity and need further state approvals to expand, and that 22 locations will show no year-on-year growth in new autumn enrollments because eight of them already started the maximum number of students their states authorised a year earlier.
Kaplan is paid the same way
Graham Holdings is filed as a conglomerate, with television stations, car dealerships, burners and lumber, and its education arm is usually treated as a sideline. It is not one: Kaplan's $50.3m of second-quarter operating income was 60% of the group's $83.6m, on education revenue that was only 32% of the top line. And Kaplan collects on the identical architecture — a 30-year support agreement under which it takes a fee of 12.5% of Purdue University Global's revenue, 13% for the years to 30 June 2027. Graham's education revenue fell 4% last quarter while its education operating income rose 9%.
American Public Education's payer is an appropriation
American Public Education owns its institutions outright and therefore keeps every obligation the fee collectors contracted away. In 2025, students using Pentagon tuition assistance as their primary payment source accounted for 41% of American Public University System's revenue, veterans' benefits 26% and Title IV federal student aid 19%. Since the American Rescue Plan Act, military and veterans' money counts on the federal side of the 90/10 rule, and APUS's ratio stood at 89% — one point from the limit, with the company stating it cannot assure future compliance.
The operating news was good. Second-quarter revenue rose 5.5% to $171.7m, gross margin widened to 55.4% from 51.8%, operating income nearly doubled to $13.5m, and full-year guidance was raised to revenue of $690m–$698m and diluted earnings of $2.48–$2.79. On 4 August the company folded Rasmussen University and Hondros College of Nursing into APUS, lifting the last regulatory restriction on Rasmussen's total enrollment. "The foundation is built, the business is simplified, the balance sheet is strong, and now the institutional combination is complete," chief executive Angela Selden told investors on 10 August.
The quarter after it was the problem. Third-quarter revenue was guided to $164.5m–$167.0m against consensus of $169.9m, and earnings to $0.18–$0.29 against $0.56, implying military course registrations up 1.0%–3.0% and nursing enrollment up 2.5%.
What the de-rating got right
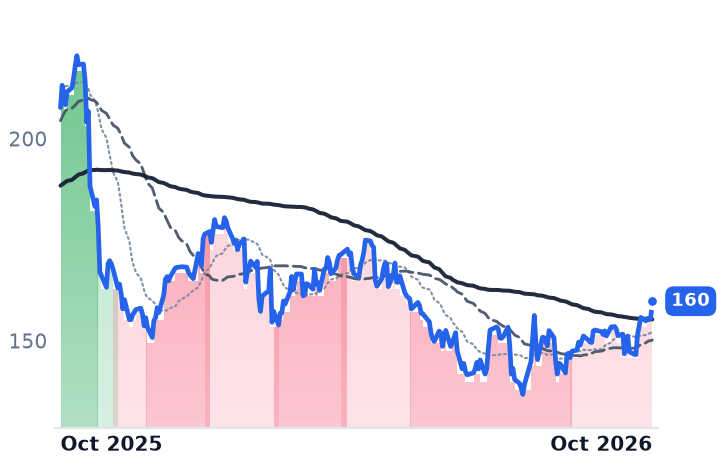
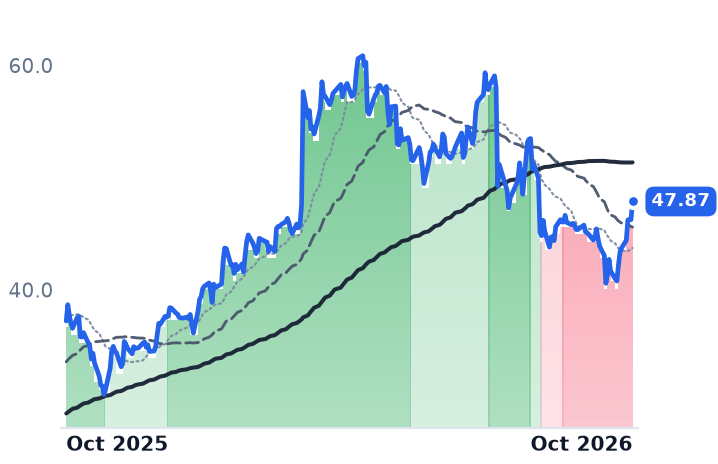
Shares of Grand Canyon Education fell 7.0% over the two sessions after the amendment and raised guidance were published, and at $159.80 remain 22.8% below the $207.00 of a year ago. Price against trailing gross profit has compressed from roughly 10.3x then to 6.85x while that gross profit grew 7.6%; the forward multiple of 15.6x earnings sits below the trailing 19.2x. American Public Education is down 17.2% over three months and trades at 2.41x trailing gross profit, back from 3.07x in July, having given back most of a year's re-rating.
Only one of those two moves has a business event under it, and it is the smaller one: a phasing problem inside a year the company raised. The larger move has no deterioration behind it at all. The genuine damage in this industry landed on the owners of Title IV-funded campuses — Lincoln Educational Services fell from $43.20 in early August to $23.49, after reporting that enrollment grew about 9% while student starts rose about 1% "as fewer enrolled students than expected attended the first day of class", with management pointing at the restart of federal loan repayments in May 2026. A fee computed on a tuition invoice does not feel a student-credit shock the way a school that must collect from the student does.
What it feels instead is policy. The Education Department's 2011 bundled-services exception is what permits an online program manager to be paid a share of tuition at all, and the department has been soliciting comment on that exception and on the incentive-compensation prohibition it carves out of. Projections of US high-school graduates have the count peaking in 2025 and falling about 13% through 2041, even as total fall 2025 enrollment came in roughly 1% above the year before. The pipeline is a slope, not a cliff edge, and it runs the length of the new agreement.
So Grand Canyon Education has fixed its share of one university's frozen tuition until 2041, and fixed it over exactly the span in which the supply of eighteen-year-olds is expected to thin. The contract settles who gets paid and for how long. It cannot settle how many people walk through the door.