

Record Data-Center Cooling Orders at Modine, AAON and Trane Cost All Three Gross Margin
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The market treated data-center cooling as a demand story and sold it after one late-July report. Demand was not what cracked; the profit on converting orders was.
Modine's Data Centers segment nearly doubled sales to $348.6m on a third consecutive quarter of record orders, AAON's backlog rose 98% to $2.0bn, and Trane booked a record $12.1bn backlog. Every one of them lost gross margin, and AAON cut its full-year gross-margin guidance by two percentage points while raising sales-growth guidance.
The division among them is financial leverage to a single end market. Modine and AAON, both building plant and shipping units priced at award date, now trade at 12.9x and 14.3x gross profit against roughly 18x in May; Trane's multiple is where it was.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
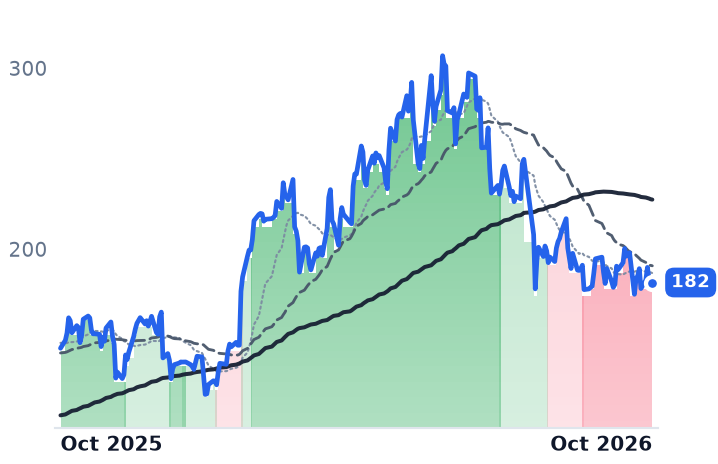
MOD | Modine Manufacturing | Thermal & Powertrain Components | ⚠️ Emerging Bear | +0.3% | +25.0% |
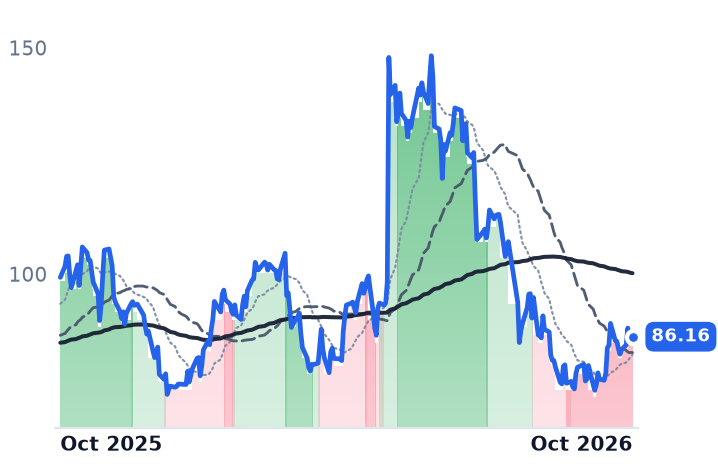
AAON | AAON | HVAC Systems | ⚠️ Emerging Bear | +12.2% | −13.2% |
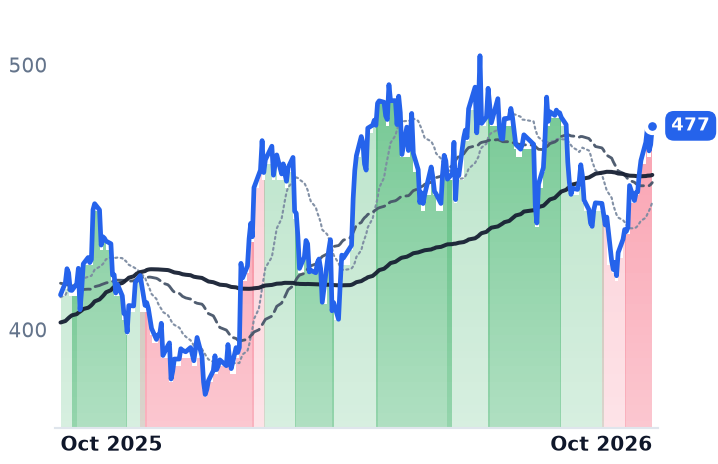
TT | Trane Technologies | HVAC Systems | ⚠️ Emerging Bear | +8.5% | +15.5% |
| Compared against · context, not the story | |||||
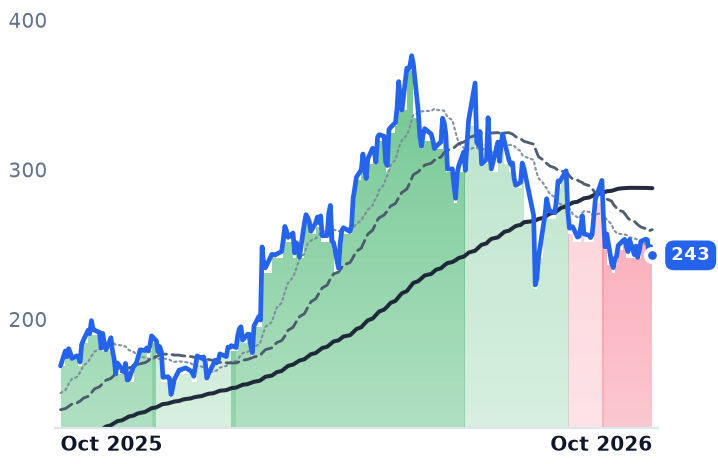
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −2.2% | +43.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MOD | $9.6B | 68.0x | 24.1x | 2.9x | 2.4x | 12.9x | 10.7x | 33.7x | 1.0% |
AAON | $7.1B | 44.4x | 36.2x | 3.7x | 3.1x | 14.3x | 12.0x | 25.2x | -1.7% |
TT | $104.9B | 35.9x | 31.2x | 4.7x | 4.4x | 13.4x | 12.5x | 24.9x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MOD | Revenue | +22.6% | +29.0% | +14.9% |
| EPS | +33.4% | +50.1% | +38.0% | |
AAON | Revenue | +65.6% | +17.6% | +16.3% |
| EPS | +68.8% | +51.4% | +26.3% | |
TT | Revenue | +11.7% | +9.7% | +8.8% |
| EPS | +17.4% | +15.5% | +15.4% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Modine Manufacturing, which builds coils, chillers and air handlers to order for hyperscale data centers and for vehicle makers, nearly doubled sales in its data-center business in the June quarter and lost more than nine percentage points of gross margin doing it. The segment reported $348.6m against $183.7m a year earlier, and its gross margin came in at 20.2%, 960 basis points below the prior year, because shortages of certain key components limited what the plants could produce.
The complex was sold in late July on the premise that hyperscalers were about to stop ordering heat-rejection gear. On the evidence the three largest listed sellers of that gear have published, the ordering never slowed. What slipped is the money earned turning an order into a shipped unit, and that distinction is the whole argument now sitting in front of three reports due in the next month.
The order book is the part that is working
Neil D. Brinker, Modine's president and chief executive, said demand remains robust "as evidenced by three consecutive quarters of record order intake leading to the company's backlog nearly doubling over the past year." Part of the franchise is pre-sold rather than bid project by project: an agreement guarantees Modine's ability to supply more than $4bn of Airedale cooling products between 2027 and 2029, against a $165m upfront payment earmarked for expanding production capacity. Its anchor data-center customers have been reported as Google and Amazon; order visibility and customer concentration are the same disclosure read twice.
Group revenue rose 28.0% to $874.1m, yet gross profit rose 10.0% and operating income fell 1.2%. On the 30 July call management quantified the drag: component shortages cost 450 to 550 basis points of Data Centers margin through unfavorable overhead absorption, labor deliberately carried through supply-chain downtime. Guidance was left at 20-35% revenue growth with Data Centers sales up 60-80% and segment margins above 20% in the second half. Modine is also spinning Performance Technologies, its vehicular business, into a merger with Gentherm through a Reverse Morris Trust, leaving shareholders roughly 40% of the combined company and expected to close by the end of calendar 2026.
AAON's constraint is floor space, and it costs margin
AAON, which sells rooftop units through independent sales representatives and custom data-center cooling through its BasX division, doubled sales to $627.0m in the June quarter, with BASX-branded sales up 216% to $345m and total backlog up 98% to $2.0bn. The legacy book grew too: AAON-branded sales rose 39.3% and that backlog 9.4%.
Gross margin fell 2.2 points, and the company cut its full-year gross-margin range to 25-26% from 27-28% while raising sales growth to 55-60%. Chief executive Matt Tobolski attributed the squeeze to "the mix impact of exceptionally strong growth, ramp-up activity associated with new capacity and price/cost timing dynamics" — a unit quoted months ago, built from metal that has since repriced. Three-month copper on the London Metal Exchange touched a record $13,387.50 a tonne on 8 September and has traded above $14,300 since; JPMorgan forecasts aluminium near $3,800 a tonne this quarter. AAON has added roughly a million square feet at Longview, Texas and Memphis, Tennessee, and its trailing free-cash-flow yield is minus 1.68%: the plant is being funded out of current cash flow. Its shares now trade at 14.3x gross profit against 18.4x in early May, though at 36.2x forward earnings it remains the dearest of the three.
The one that didn't have to de-rate
Trane Technologies, the applied-systems vendor whose chiller bookings are the cleanest published read on hyperscaler capex converting into construction, booked a record $7.8bn of orders, a 123% book-to-bill with every segment above 100%, record backlog of $12.1bn and applied-equipment bookings up 130%, a fourth straight quarter above 100% growth. Trane lost 2.0 points of gross margin as well, from a 35.6% base that absorbs it. Its price-to-gross-profit is 13.4x against 13.8x in May, and 31.2x forward earnings against consensus revenue growth of 11.7% this year.
What the shares did
The repricing was one session. On 29 July, after Vertiv reported 24% revenue growth and fell 17% on the day, Modine closed down 14.4%, AAON 9.5% and Trane 4.9%. Over three months to 9 October Modine is down 22.9% and AAON 20.2% while Trane rose 1.0%; measured from their highs since September 2025, Modine sits 40.8% below and AAON 41.9%, Trane 5.3%. The underlying bear case predates July: at CES on 6 January, Nvidia's Jensen Huang said next-generation Vera Rubin racks run coolant at 45C inlet "with no chillers necessary," and cooling shares fell hard that day. Vertiv's published answer was that "using higher-temperature water does not eliminate the need for heat rejection".
The margin cuts justify some of the de-rating; the order books justify none of it. Modine's 12.9x gross profit against 17.96x on 3 May, and a 24.1x forward multiple against consensus revenue of $4.06bn next fiscal year, up 29%, is a business whose estimates have not followed its price. The reason Trane sat out the fall is structural: diversified revenue, a gross margin nearly two-thirds higher than Modine's, and no plant ramp to fund. Modine and AAON are the levered expressions of one end market, converting award-priced backlog while building the capacity to convert it, and that is where a two-point margin miss turns into a 40% drawdown.
Modine reports on 27 October, Trane on 29 October and AAON about 5 November. The question those three prints settle is narrow and answerable: whether the margin on a shipped chiller recovers once the components arrive, or whether building to a price agreed last year is simply what this business now earns.