

Announced Transformer Plants Add a Third More Output by 2028, Short of Demand Up by Half
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A shortage is supposed to be killed by new factories, and the factories have been announced. The arithmetic says they do not finish the job: announced plants lift global large-power-transformer nameplate output by roughly 35% by 2028 against 2023, while demand scenarios run to 50% or more, and the gap closes only after 2028.
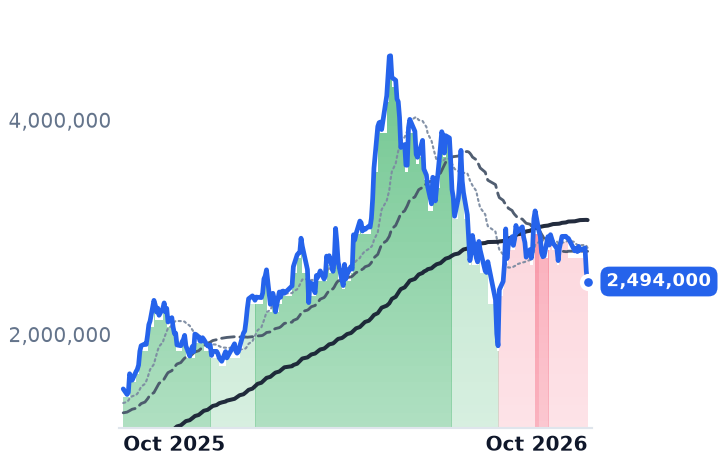
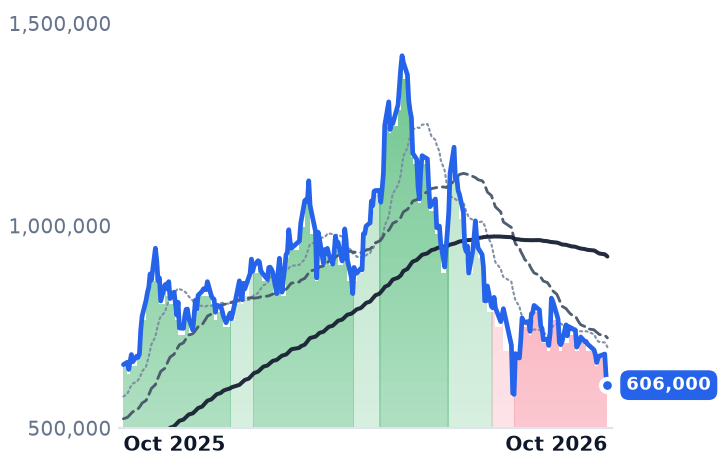
The two Korean makers building into that gap were marked down hard anyway. Hyosung Heavy and HD Hyundai Electric each broke about 11% in the two sessions to 8 October, while Hyosung's backlog sat at KRW17.5tn, up 63% year over year, and HD Hyundai raised its 2026 order target by 22.8%. Quoted lead times on large power transformers still run near 128 weeks.
Nothing in the reported numbers or the order books explains the fall, and consensus earnings for both are still rising. The likelier reading is a reset in what a 2028 delivery slot is worth after a bond selloff rather than supply catching up.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
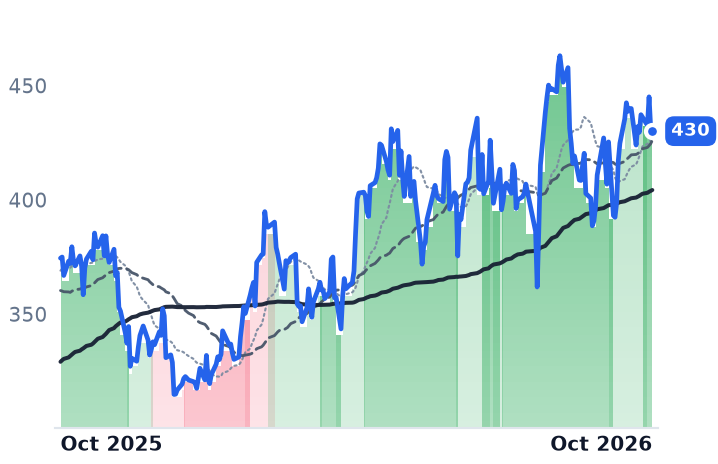
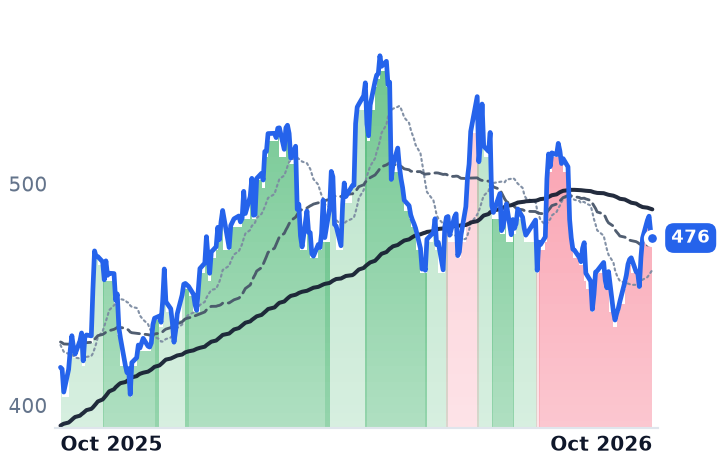
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +0.7% | +14.8% |
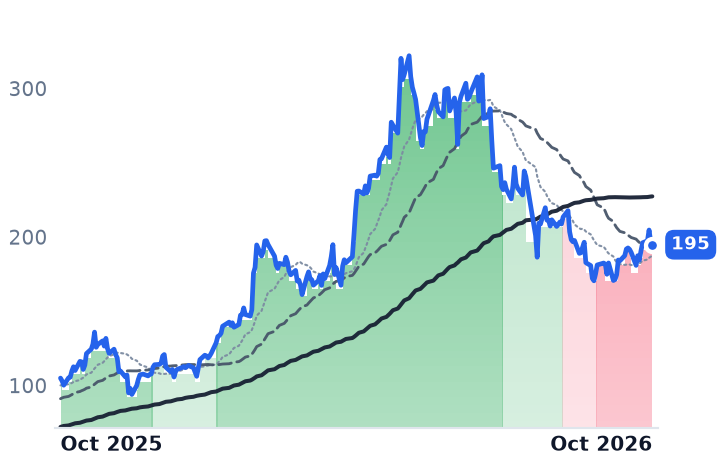
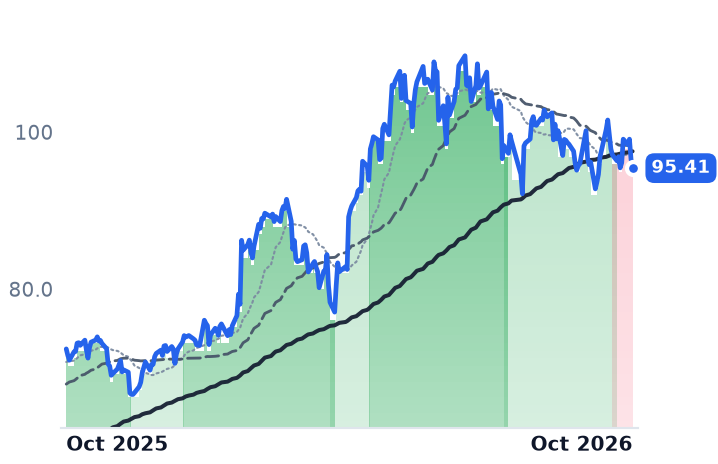
POWL | Powell Industries | Electrical Distribution & Switchgear | ⚠️ Emerging Bear | +6.8% | +85.5% |
HUBB | Hubbell Incorporated | Electrical Distribution & Switchgear | ⚠️ Emerging Bear | +2.4% | +14.0% |
| Compared against · context, not the story | |||||
298040.KS | Hyosung Heavy Industries | Electrical Equipment & Parts | ⚠️ Emerging Bear | −12.0% | +67.2% |
267260.KS | HD Hyundai Electric | Electrical Equipment & Parts | ⚠️ Emerging Bear | −16.8% | −7.7% |
ABBNY | ABB | Electrical Equipment & Parts | 🟢 Cont. Bull | −4.8% | +31.8% |
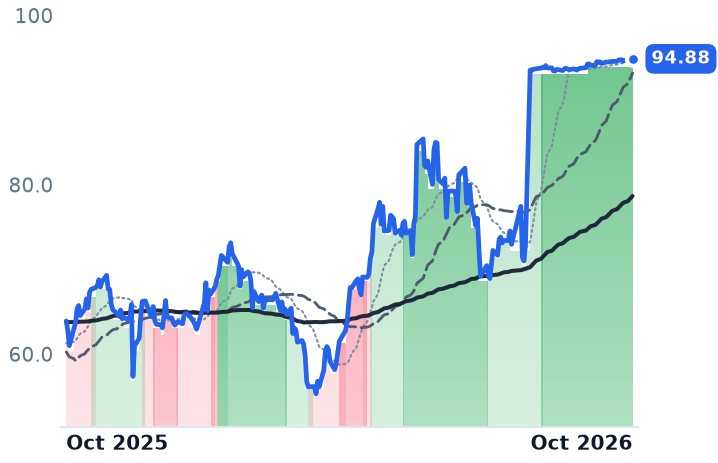
ATKR | Atkore | Electrical Infrastructure Products | 🟢 Cont. Bull | +1.1% | +48.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
298040.KS | $25.9T | 44.4x | 33.0x | 4.0x | 3.6x | 18.6x | 16.6x | 28.9x | 2.0% |
267260.KS | $24.4T | 28.7x | 25.5x | 5.6x | 5.2x | 16.2x | 15.0x | 19.7x | 2.7% |
ETN | $168.6B | 44.0x | 32.0x | 5.6x | 5.1x | 15.6x | 14.2x | 29.3x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWL | $7.1B | 37.2x | 28.4x | 6.1x | 4.7x | 20.4x | 15.7x | 26.0x | 3.4% |
HUBB | $25.3B | 28.3x | 23.4x | 4.1x | 3.7x | 11.6x | 10.5x | 20.6x | 3.6% |
ABBNY | $179.9B | 35.7x | 29.6x | 4.9x | 4.7x | 12.3x | 11.7x | 23.9x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ATKR | $3.2B | n/m | 14.9x | 1.1x | 1.0x | 5.6x | 5.2x | n/m | 1.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
298040.KS | Revenue | +22.2% | +19.4% | +16.7% |
| EPS | +62.4% | +43.5% | +32.6% | |
267260.KS | Revenue | +16.1% | +19.2% | +14.9% |
| EPS | +36.7% | +27.7% | +21.8% | |
ETN | Revenue | +20.0% | +11.2% | +9.7% |
| EPS | +12.6% | +19.3% | +17.2% | |
POWL | Revenue | +8.8% | +25.8% | +14.4% |
| EPS | +12.1% | +27.8% | +19.8% | |
HUBB | Revenue | +17.6% | +10.2% | +6.2% |
| EPS | +12.7% | +12.0% | +10.9% | |
ABBNY | Revenue | +13.7% | +12.5% | +10.4% |
| EPS | +31.2% | +10.8% | +14.7% | |
ATKR | Revenue | +5.0% | +4.7% | +6.6% |
| EPS | −13.4% | +11.5% | +13.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The cure for a transformer shortage is more transformer factories, and the industry has committed to a wave of them. Eaton, the power-management group that builds switchgear and utility distribution gear, is putting up a $340m transformer plant in South Carolina targeting 2027 production; Siemens Energy has a $150m plant in North Carolina. Add the announced nameplate together and global large-power-transformer output rises by roughly 35% by 2028 against 2023, against demand that several scenarios put at 50% or more, with the supply gap closing only after 2028 in the base case.
That matters because the shares of the companies building the capacity have lately been priced as though the cure had already landed. The de-rating across power equipment since the summer reads naturally as the shortage premium deflating as supply arrives. The order books and the quoted lead times tell a different story, and the two makers that fell hardest in October are the ones whose backlogs lengthened most.
Hyosung Heavy Industries and HD Hyundai Electric each broke about 11% in the two sessions to 8 October. Neither disclosed anything.
A 128-week quote is still a 128-week quote
Large power transformers that took two years or less before 2020 now average around 128 weeks, with power and substation units quoted at 160-plus weeks as of August 2026 and high-capacity hyperscaler units at four to five years. Medium-voltage switchgear runs roughly 52 to 80 weeks at the 15kV class and 78 to 104 weeks at 38kV on June 2026 procurement data, sold out through 2028 in many channels. The constraint still lands on the buyer: Bloomberg, citing Sightline Climate, estimates 30% to 50% of planned 2026 US data-center capacity could slip or be cancelled because the gear cannot be delivered on time.
Five years of work on the book, and a plant still to come
Hyosung Heavy, which builds power and cast-resin transformers, high-voltage switchgear and high-voltage direct-current transmission systems alongside a separate construction division, ended June with a KRW17.5tn backlog, up 63% year over year, which analysts put at roughly five years of work. It has signed KRW386.5bn, about $277m to $287m, of ultra-high-voltage transformer contracts with two unnamed US technology companies for AI data centers. The June quarter carried a 14.96% operating margin against 10.77% a year earlier, and group operating margin has gone from 4.08% in 2022 to 11.16% in fiscal 2025: the thinnest margin among these makers, and so the most geared to the premium.
HD Hyundai Electric, which makes power and distribution transformers, gas-insulated switchgear, motors and generators, held a backlog of $8.5bn at end-June, up 23% in six months, and raised its 2026 order target by 22.8% to $5.185bn. A second plant aimed particularly at North America is due for completion in April 2027, with main Korean facilities already running near 95% utilization. June-quarter revenue rose 26% to KRW1,141.8bn at a 25.14% operating margin.
The US-listed read agrees. Eaton's Electrical Americas backlog reached $15.2bn, up 33% year over year, on a rolling-twelve-month book-to-bill of 1.3x, and "accelerating orders and growing backlogs are clear proof points that our customer-focused end-to-end solutions are winning in the market," chief executive Paulo Ruiz said in the 31 July second-quarter release.
What fell, and what did not change
Hyosung Heavy dropped 11.2% and HD Hyundai Electric 11.3% in those two sessions, extending ninety-day falls of 14.7% and 28.8%; across twelve months Hyosung is still up 75.9% and HD Hyundai up 2.6%. No company announcement is discoverable behind the break, and earlier falls in the Korean power complex were attributed to profit-taking, weakening AI sentiment and rotation into large-cap semiconductors rather than impairment. Meanwhile the 30-year Treasury yield reached 5.69% on 8 October, its highest since 2002.
So the results account for none of the decline.
Consensus still has Hyosung revenue up 22.2% and earnings up 62.4% this year, and HD Hyundai earnings up 36.7%. At the 8 October closes that leaves Hyosung near 29.6x forward earnings, derived from a stale 33.0x snapshot, and HD Hyundai near 22.8x. Estimates rose while the shares fell, which is the signature of a reset in what a delivery slot years out is worth once the discount rate moves, not of a bookings turn in the shortage.
The plants being built now are the test of the whole premium, and they report late: a Korean second line in April 2027, Eaton's South Carolina output in 2027, Siemens Energy's North Carolina capacity behind that. Until one of them shortens a quote, the shortage belongs to the seller.