

US Containerboard Mills All Took October Downtime, and Waste Paper Prices Fell by Half
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Cheaper recovered fiber was supposed to be the gift that widened containerboard margins into the fourth quarter. The October data says it arrived for the wrong reason: Fastmarkets put US old corrugated container pricing at a $38-a-ton average, down $39 month on month, and attributed it to weak demand, full mill inventories and market-related downtime at every major US containerboard mill.
That matters because September's published index only recognized $70 a ton of linerboard increase against Packaging Corp's announced $140. Mills idling machines are not mills collecting that price. Meanwhile the fast cost moved the other way: diesel set a record $6.53 a gallon on 22 September.
Packaging Corp is the exposed name here, up 7.7% over twelve months at 29.7x trailing earnings after four quarters of falling operating income. International Paper and Graphic Packaging have already been marked down to their collapsing estimates.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
IP | International Paper | Corrugated & Containerboard | 🌱 Emerging Bull | −12.8% | −28.4% |
PKG | Packaging Corporation of America | Corrugated & Containerboard | 🟢 Cont. Bull | −2.0% | +9.2% |
GPK | Graphic Packaging | Corrugated & Containerboard | 🔴 Cont. Bear | −13.9% | −54.0% |
| Compared against · context, not the story | |||||
SW | Smurfit Westrock | Corrugated & Containerboard | 🟢 Cont. Bull | −5.7% | +6.1% |
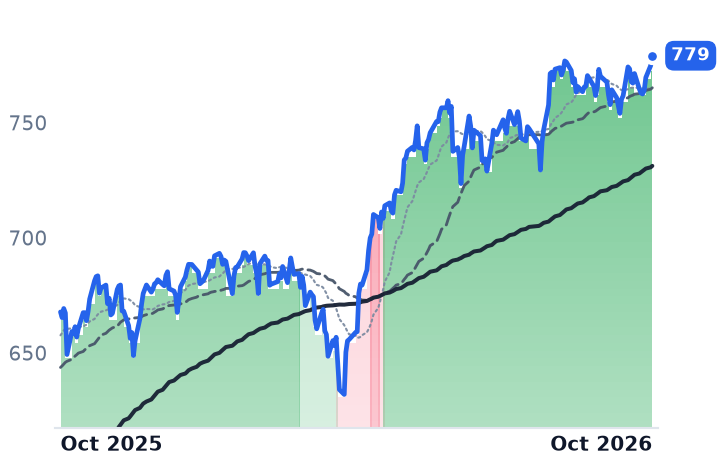
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.5% | +16.7% |
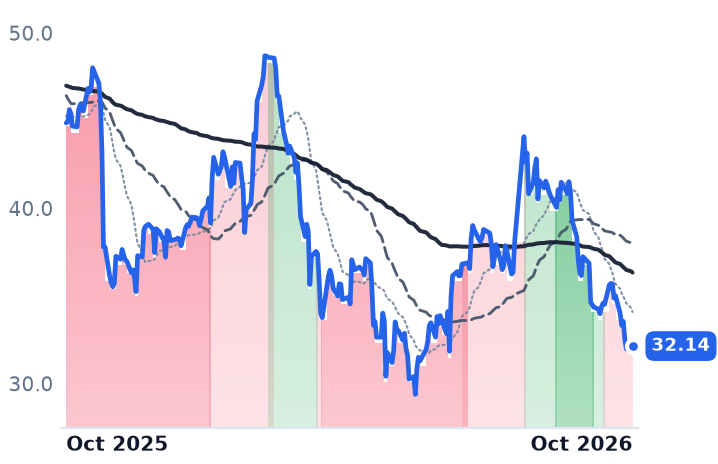
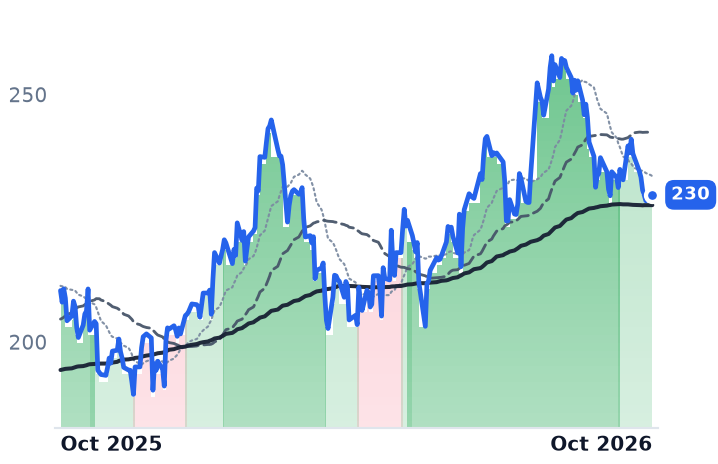
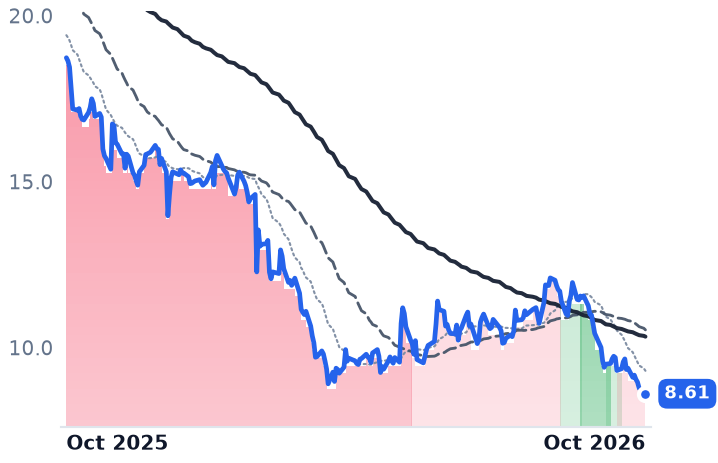
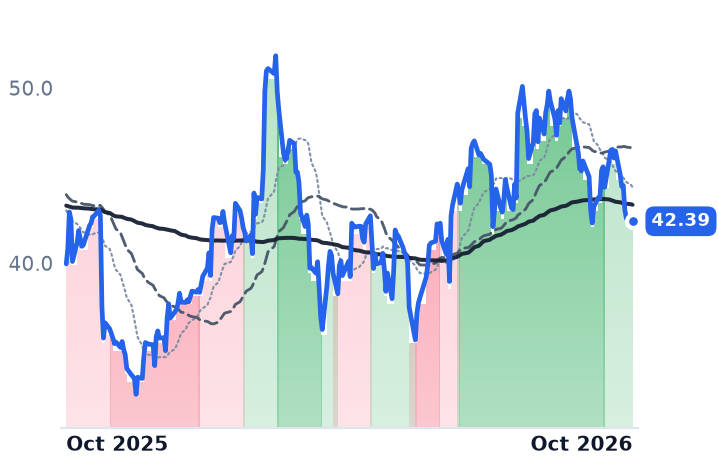
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IP | $17.0B | n/m | 24.6x | 0.7x | 0.7x | 2.5x | 2.5x | n/m | 2.9% |
PKG | $20.5B | 29.7x | 22.0x | 2.1x | 2.0x | 10.7x | 10.1x | 13.2x | 3.6% |
GPK | $2.5B | 13.0x | 12.3x | 0.3x | 0.3x | 1.9x | 1.9x | 8.9x | 7.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SW | $22.3B | 47.3x | 19.2x | 0.7x | 0.7x | 4.2x | 3.9x | 8.6x | 4.4% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IP | Revenue | +0.2% | +6.1% | +1.5% |
| EPS | +443.6% | +131.9% | +13.1% | |
PKG | Revenue | +10.9% | +7.8% | +2.8% |
| EPS | +5.4% | +30.4% | +5.2% | |
GPK | Revenue | +0.9% | +1.8% | +1.8% |
| EPS | −62.5% | +50.1% | +14.5% | |
SW | Revenue | +3.1% | +5.8% | +2.2% |
| EPS | −7.5% | +57.4% | +13.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Every major containerboard mill in the United States took market-related downtime in October, and the price of the waste paper they buy as raw material collapsed with them. Fastmarkets put US old corrugated container pricing at a $38-a-ton average for the month, down $39 from September's $77 and $88 over three months, blaming "weak bulk grade demand, high mill inventories, and market-related downtime at major paper and board mills in the USA." Mixed paper reached a high side of zero. Recovered paper is being landfilled in Florida.
Falling fiber has been read all autumn as the input relief that would finally let a round of announced price increases reach the operating line. The October print inverts that reading. Cheap fiber of this kind is the fingerprint of mills that cannot sell board at September's price, not of supply discipline tightening a market.
The index only ever confirmed half the increase
The revenue side of a corrugated dollar resets off a published third-party benchmark, with weeks to months of lag before an announced increase reaches an invoice, and only if the publisher validates it. September's Fastmarkets RISI settlement recognized linerboard up $70 a ton and medium up $100 against announced increases of $140 from Packaging Corporation of America, $100 from Smurfit Westrock and $80 from International Paper, all effective 1 September. No October settlement existed as of 6 October, so the only dated index evidence is September's.
Mark Kowlzan, Packaging Corp's chief executive, described the mechanics on the company's second-quarter call: "We are seeing the majority of the first increase rolling in during July and we'll see the beginning of the second increase in August with realizations split between Q3 and Q4."
The costs that are not indexed do not wait. US average diesel hit a record $6.53 a gallon on 22 September, roughly 77% above a year earlier. Andy Silvernail, International Paper's chief executive, sized a $2-a-gallon move at $150m to $200m for his company at a Jefferies conference on 10 September, and had already told investors on 30 July: "The pricing up to now has really been eaten by inflation... If you look at what's happened with OCC, energy, diesel, freight, you name it... it's unfortunately really eaten every bit of that pricing up until today."
What Packaging Corp has to prove on 21 October
Packaging Corp, which makes containerboard and converts nearly all of it into shipping boxes and retail displays, is the group's best operator and its most exposed valuation. Its revenue growth accelerated for four consecutive quarters, from 6.0% to 14.7% year on year, and operating income fell year on year in all four. June-quarter operating margin was 13.38% against 15.37%. Total corrugated shipments per day rose 24.3% on the Greif containerboard assets bought for $1.8bn, and legacy shipments still set a quarterly record, none of which reached the operating line.
The shares are up 7.7% over twelve months at 29.7x trailing and 22.0x forward earnings, which is 26.8x the $8.58 the company actually reported for 2025 and 20.8x peak-cycle 2022 earnings of $11.02. Third-quarter results come after the close on 21 October, guided to $2.91 a share excluding special items, against $2.51 reported a year earlier.
International Paper has already been marked to its arithmetic. June-quarter revenue fell 11.3% to $6.004bn and operating income was $45m, a margin of 0.75%. Its 2025 net loss of $3.52bn makes trailing earnings multiples meaningless; at $32.14 it is on 24.6x the 2026 consensus of $1.31 and 10.6x the 2027 consensus of $3.03, a 132% one-year jump that consensus builds out of margin rather than volume, on revenue up 6.1%. The company is closing five sites for an expected $230m earnings improvement, and its North American box volumes rose 1.7% a day while industry shipments fell 1.9%.
Graphic Packaging has the cost leg and none of the index
Graphic Packaging sells folding cartons, cups and food containers to consumer-goods and restaurant buyers and makes no containerboard at all. Management told investors it is "taking pricing actions on the approximately $1 billion of revenue where pricing is not determined by a contract" — roughly 12% of about $8.6bn of sales. It re-guided 2026 inflation to at least $150m from $60m-65m. June-quarter gross margin was 13.35% against 19.19%, operating income fell 56%, and 2026 consensus earnings of $0.70 a share sit 53% below the $1.48 delivered in 2025. The shares trade at 0.79x book and 12.3x forward earnings because the estimate underneath them fell further than the price. The boxboard operating rate it runs against was 88.8% in the second quarter, while containerboard ran near 95%.
So the twelve-month tape splits along earnings lines, and only one name is unexplained. International Paper down 31.1% and Graphic Packaging down 54.9% match businesses whose margins and estimates have gone backwards. Packaging Corp's gain does not: it is priced for 2027 earnings of $13.63 a share, a 30% step-up, by a company that has not grown operating income in a year. Since 4 September, shares of the two corrugated names fell 13.7% and 3.2% while the broad market rose, which is the market beginning to ask the same question.
The box buyers are asking it out loud. The Association of Independent Corrugated Converters publicly opposed the third increase of the year on 10 August, arguing raw-material costs did not justify it and noting that producers announce large numbers and secure smaller ones. October's fiber price, set by machines that stopped running, is the strongest argument they have been handed yet.