

Leverage, Not Pallets, Split Cold-Storage Landlords Americold and Lineage in September
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Two landlords rent the identical thing — pallet positions in refrigerated rooms — and their shares parted company last month for a reason that has nothing to do with food. Both are filling more space while moving fewer pallets: Americold's physical occupancy reached 67.4% against economic occupancy of 76.0%, and Lineage's same-store throughput fell 1.8% while its price per pallet handled rose 2.1%.
The gains are rate and cost removal, not volume. What differs is the liability side. Americold put roughly $1.1bn of joint-venture proceeds against debt and raised guidance; Lineage carries $7.8bn of net debt, leverage near 6.0x against its own 5.0-5.5x target, and a dividend absorbing 73% of guided cash flow that is itself falling. When the ten-year Treasury yield passed 5%, Americold was the only industrial landlord in its set still trending up, and Lineage took three target cuts in a week.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
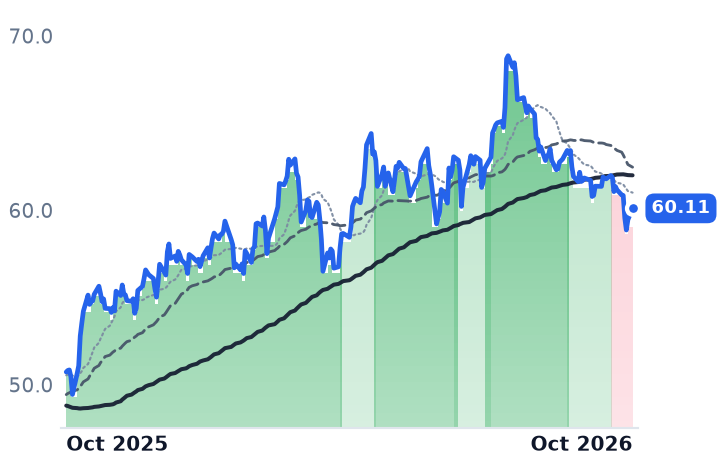
COLD | Americold Realty Trust | Temperature-Controlled Warehousing | 🟢 Cont. Bull | +2.0% | +10.2% |
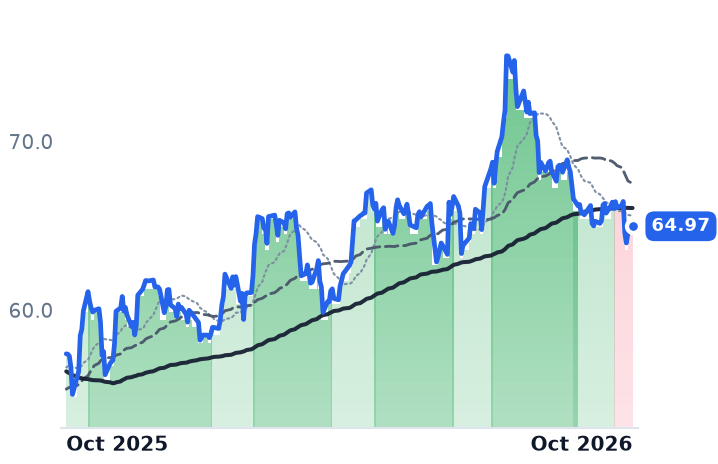
LINE | Lineage | Temperature-Controlled Warehousing | 🌱 Emerging Bull | −7.5% | −12.6% |
| Compared against · context, not the story | |||||
PLD | Prologis | Logistics & Distribution | 🟢 Cont. Bull | −7.0% | +11.7% |
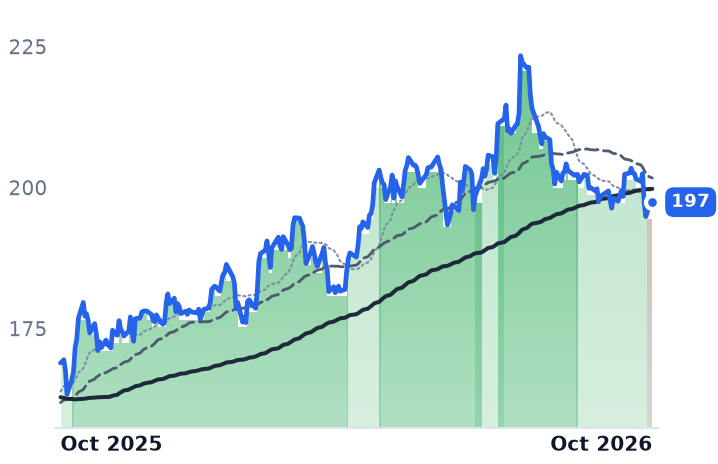
CAG | Conagra Brands | Frozen & Prepared Foods | 🔴 Cont. Bear | −12.6% | −24.2% |
FR | First Industrial Realty Trust | Logistics & Distribution | 🟢 Cont. Bull | −2.6% | +18.5% |
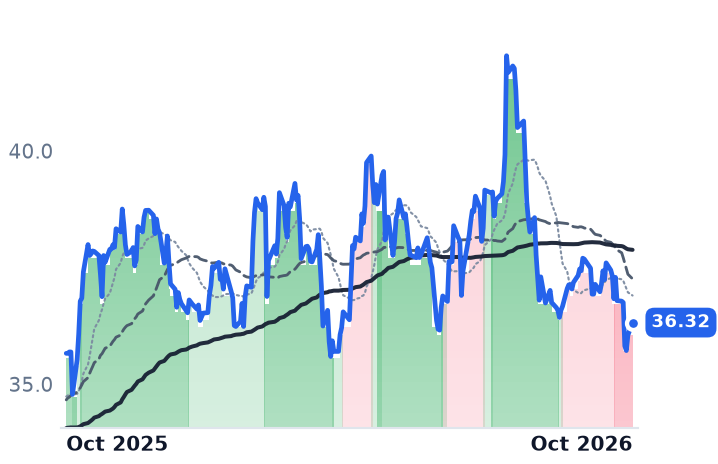
TRNO | Terreno Realty | Logistics & Distribution | 🟢 Cont. Bull | −1.9% | +13.2% |
EGP | EastGroup Properties | Logistics & Distribution | 🟢 Cont. Bull | −1.0% | +16.9% |
STAG | STAG Industrial | Logistics & Distribution | ⚠️ Emerging Bear | −3.1% | +1.8% |
TSN | Tyson Foods | Meat Processing | 🔴 Cont. Bear | −0.1% | −2.3% |
12-month price & trend
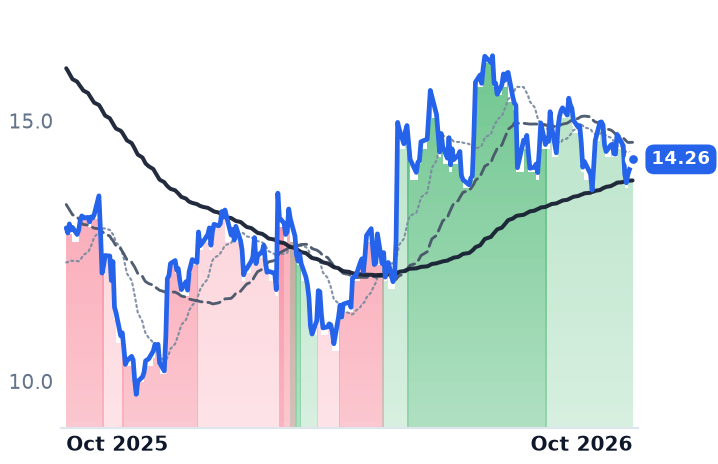
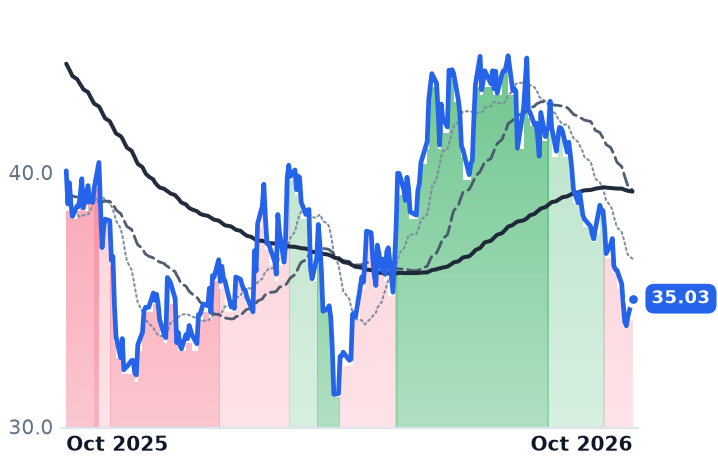
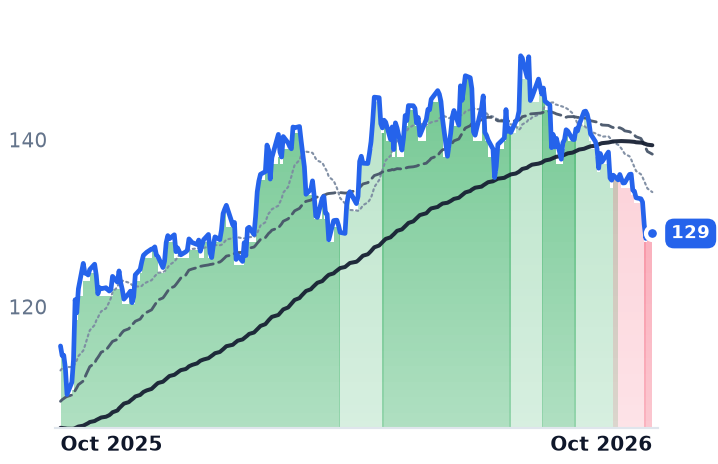
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
COLD | $4.1B | n/m | — | 1.6x | 1.6x | — | — | 125.3x | -2.9% |
LINE | $8.0B | n/m | — | 1.5x | 1.5x | 13.6x | 13.5x | 11.7x | 3.0% |
PLD | $120.4B | 28.7x | 35.1x | 13.1x | 14.0x | 45.1x | 48.1x | 18.6x | 4.4% |
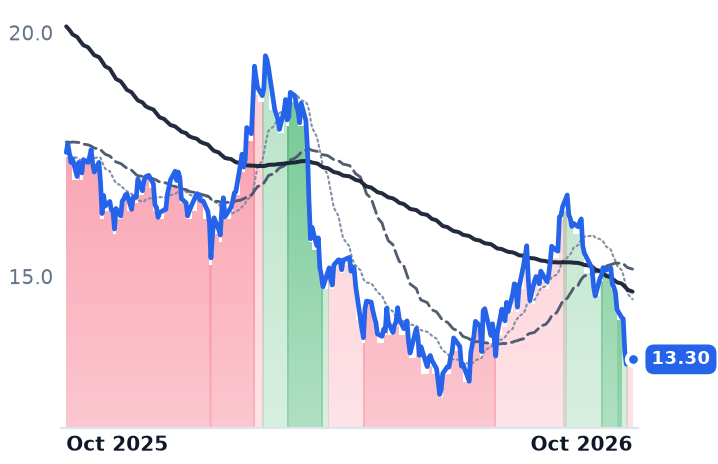
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CAG | $6.4B | n/m | 9.1x | 0.6x | 0.6x | 2.4x | 2.5x | n/m | 13.8% |
FR | $8.1B | 23.5x | 29.1x | 10.8x | 10.7x | 23.0x | 22.7x | 12.2x | 6.0% |
TRNO | $6.9B | 16.1x | 43.0x | 14.1x | 13.5x | 22.1x | 21.1x | 13.5x | 2.9% |
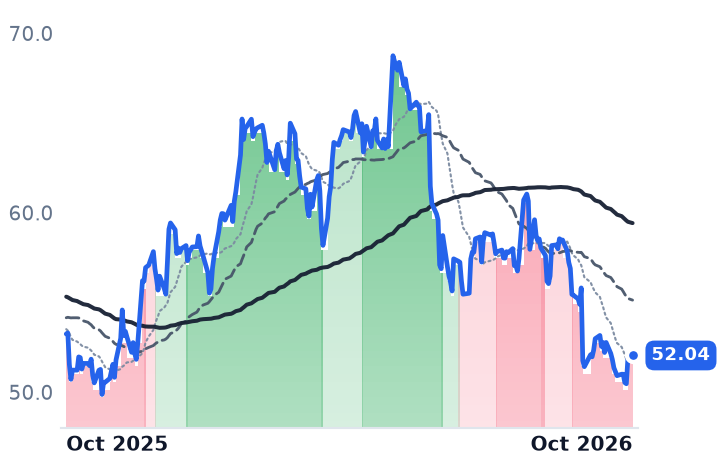
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EGP | $10.8B | 36.7x | 34.9x | 14.6x | 13.8x | 40.6x | 38.2x | 23.0x | 3.9% |
STAG | $7.2B | 29.6x | 34.8x | 8.4x | 8.0x | 13.5x | 12.9x | 15.3x | 5.6% |
TSN | $18.5B | 31.3x | 12.5x | 0.3x | 0.3x | 5.4x | 5.4x | 9.9x | 6.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
COLD | Revenue | −2.6% | +0.4% | +6.4% |
| EPS | +8674.3% | −107.8% | +114.5% | |
LINE | Revenue | −0.3% | +2.3% | +4.6% |
| EPS | +100.3% | −19.1% | −23.1% | |
PLD | Revenue | +5.6% | +9.4% | +7.5% |
| EPS | +33.6% | −5.2% | +13.2% | |
CAG | Revenue | −3.2% | −4.1% | −0.4% |
| EPS | −26.7% | −13.9% | +2.5% | |
FR | Revenue | +4.4% | +7.3% | +7.4% |
| EPS | +24.9% | −9.8% | +4.4% | |
TRNO | Revenue | +8.4% | +11.1% | +15.8% |
| EPS | −57.8% | +2.2% | +22.8% | |
EGP | Revenue | +9.1% | +8.9% | +10.7% |
| EPS | +17.3% | +0.3% | +3.6% | |
STAG | Revenue | +8.4% | +6.4% | −2.3% |
| EPS | −12.2% | +4.1% | +14.1% | |
TSN | Revenue | +2.6% | −1.2% | +1.3% |
| EPS | −5.6% | +16.5% | +22.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two companies rent the same thing, pallet positions in refrigerated rooms, and last month the market stopped treating them alike. Both are filling more space while handling fewer pallets: Americold's physical occupancy reached 67.4% against economic occupancy of 76.0%, and Lineage's same-store throughput fell 1.8% while the price per pallet handled rose. The improvement is coming from rate and cost removal, with physical volume still shrinking at both.
What separated the shares was the balance sheet. Americold closed a joint venture with EQT, put the proceeds against maturities and raised cash-flow guidance; Lineage carries $7.8bn of net debt, leverage near 6.0x against its own 5.0-5.5x target, and a dividend taking 73% of guided cash flow that is itself declining. When the ten-year Treasury yield passed 5%, Americold was the only industrial landlord in its set still trending up, and Lineage absorbed three analyst target cuts inside a week.
Americold spent the summer selling buildings to pay down debt. Twelve of its refrigerated facilities went into a joint venture with EQT's Active Core Infrastructure fund that closed on 31 August, freeing roughly $1.1bn of net proceeds, with about $895m of maturities through 2028 earmarked for repayment against total net debt of some $4bn. Lineage, the larger of the two operators with 498 facilities against Americold's 185, spent the same months committing capital to warehouse automation on top of $7.8bn of net debt.
Then the discount rate moved. The Federal Reserve raised rates on 16 September for the first time in three years and the ten-year Treasury yield touched 5.041%, and the sector's working assumption, that cold storage's problem is food destocking and the cure is customers restocking, turned out to be the wrong meter to watch. Neither landlord is handling more pallets. Both are earning more per pallet position. The difference in what their shares did is sitting on the liability side.
Rooms filling up, volumes still falling
Americold, which rents pallet positions and sells pallet-handling labour to food producers and distributors, reported second-quarter physical occupancy of 67.4%, up 300 basis points year on year, against economic occupancy of 76.0%. The gap is positions paid for under fixed commitments whether or not pallets are in them, and it runs to nearly nine points. Fixed commitments were 58% of storage revenue, with the top 25 customers on committed structures carrying an eight-year weighted-average stated term. Meanwhile the company handled 8.9 million throughput pallets, down 1.0%.
The two dollars inside one building behave nothing alike. Rent-and-storage margin was 61.2%, down 90 basis points; warehouse-services margin was 13.3%, up 70. That second line is a spread between the price per pallet handled and hourly wages plus the power to hold a room cold, and power is going the wrong way: US average commercial electricity prices rose 6.1% to 13.86 cents per kilowatt-hour in the first half of 2026.
"We are not relying on a recovery in demand to create value," chief financial officer Christopher Papa told investors on 6 August. "Instead, we are laser focused on executing against the priorities that are within our control."
Lineage shows the same shape with a narrower wedge: same-warehouse physical occupancy of 75.8% against 81.5% economic, same-store throughput down 1.8%, services revenue per throughput pallet up 2.1% to $32.18, and same-store net operating income down 2.9%. Its contract conversion is running backwards: the share of rent-and-storage revenue carrying minimum guarantees slipped to 44.5% from a 46.7% peak.
The glut is in old buildings, and the restocking check splits
The market absorbed negative 56 million cubic feet in the first half against 41 million of deliveries, the first negative first-half absorption since 2007, taking vacancy to a record 7.7%; pre-2006 buildings hold 68% of all vacant cube while 2006-2019 vintage runs 3.4% vacant. Replacement cost of $130-$350 a square foot, against $85-$150 for dry storage, is why nobody prices new space down to clear the old. Lineage's own estimate is that the market is about 10% overbuilt.
The independent read on inventories is mixed. USDA's September report put end-August red meat holdings up 8% year on year, pork up 12%, with poultry down 4%. On the customer side, Conagra reported Frozen & Refrigerated volumes down about 10% on its first-quarter call of 30 September, the result of its own pricing actions.
What the two balance sheets bought
Americold raised full-year cash-flow guidance to $1.26-$1.32 a share, up four cents at the midpoint after absorbing roughly five cents of dilution from the EQT venture; at $14.26 that is about 11.1x the midpoint, against an average close of $25.72 in 2024. JPMorgan upgraded the shares to Neutral on 24 September with a $16 target, citing a stabilised operating environment.
Lineage's cash flow is going the other way: adjusted funds from operations of $0.76 a share in the June quarter, down 6.2%, after $0.78 and down 8.2% in March, with leverage near 6.0x against a stated 5.0-5.5x target. The quarterly dividend declared on 15 September, $0.5325, annualises to $2.13, about 73% of the $2.925 midpoint of guidance. Competing for the same cash is the automation programme, which targets $110m of additional EBITDA from a 10% cut to roughly $1bn of annual labour spend, with $250m invested and $200m more committed through 2030. The company has idled 15 facilities, about 1% of its US portfolio, while carrying 20 under construction that it says add $134m of net operating income. Goldman Sachs cut its target to $48 from $53 on 28 September, Scotiabank to $39 from $44 on 2 October, Evercore ISI to $43 from $45 the same day.
How much the numbers explain
For Lineage, almost all of it. A 19.4% fall over three months sits against declining cash flow per share, negative same-store income, a dividend covered by a shrinking number and the heaviest debt load in the sub-sector when long yields hit their highest level since 2007. For Americold the accounting is incomplete. Revenue growth inflected from -1.6% a year ago to +1.9% in the June quarter and operating income grew 23.8%, mostly from cost removal; over 30 days the shares added 0.3% while every industrial landlord around them fell, Prologis by 6.2%. Over three months they still fell 11.5%. What looks like recovery at 11.1x guided cash flow is a de-rated price meeting a slightly better business, and consensus still models revenue down 2.6% this year.
Neither company reports again until November, so every pallet count above predates the rate move that split them. The thing worth watching is who stops competing. "We wouldn't be surprised at all, and we're certainly hearing on the street, that there'll be a couple of competitor exits in the coming quarters," Lineage chief executive Greg Lehmkuhl said on 5 August. Two-thirds of the empty cubic feet in America sit in buildings put up before 2006, owned by someone. Whether those owners leave before customers refill their rooms is the question the occupancy line cannot answer.