

onsemi Says It Can Fill Its Fabs to 93% Without New Capital Spending
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Power-semiconductor shares were sold this summer as if their factories had emptied out. At onsemi they filled up: June-quarter utilization reached 83% from 77%, the fourth straight quarter of gross-margin expansion lifted the non-GAAP figure to 39.3%, and capital spending fell to $34m, or 2.1% of revenue.
The mechanism matters because a power-chip gross margin is made by absorbing fabs and substrate plants committed years ago, not by booking revenue growth. Vishay, the broad-line discrete and passive maker, reported a 1.32 book-to-bill and a backlog up 18% to $1.9bn. Only Wolfspeed fits the idle-capacity story, with gross margin at -25% on revenue down 24%.
So the de-rating onsemi and Vishay absorbed from the July peak is not an order-book event; Wolfspeed's is. The next test is onsemi's third-quarter report, expected around November 2.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
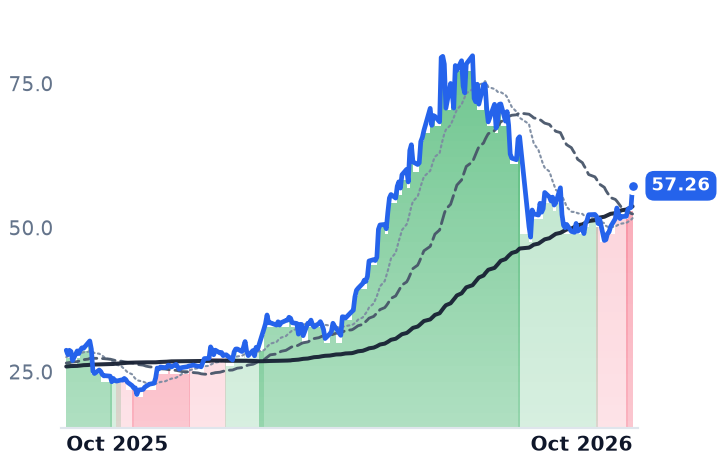
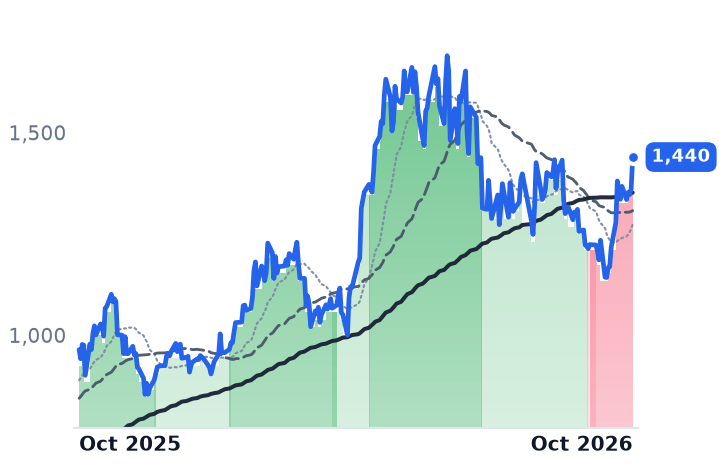
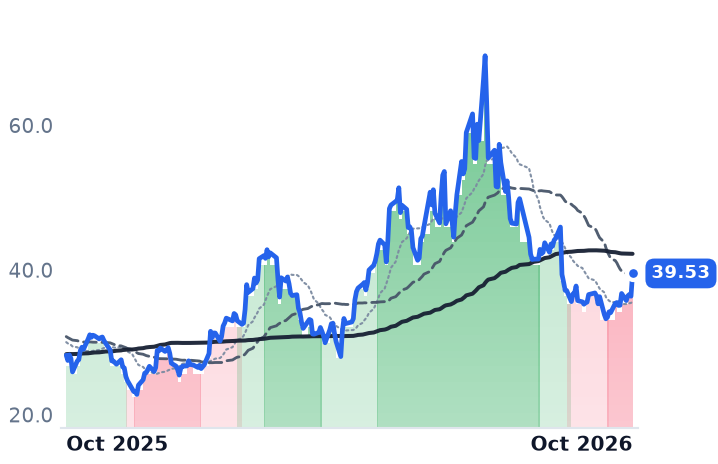
ON | ON Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | +14.1% | +68.6% |
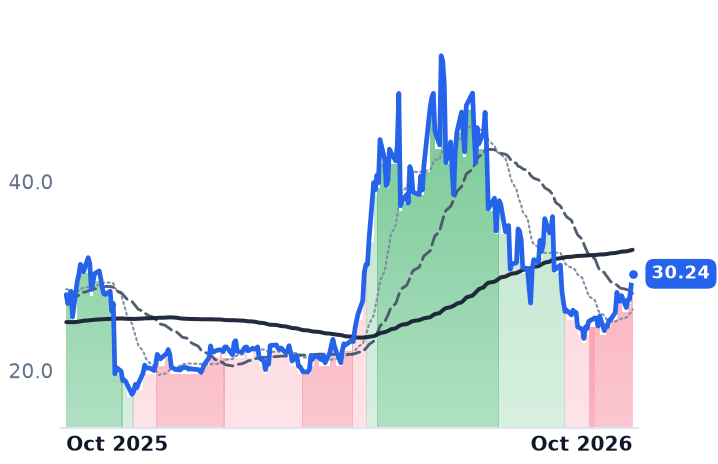
VSH | Vishay Intertechnology | Discrete & Power | ⚠️ Emerging Bear | +20.1% | +140.5% |
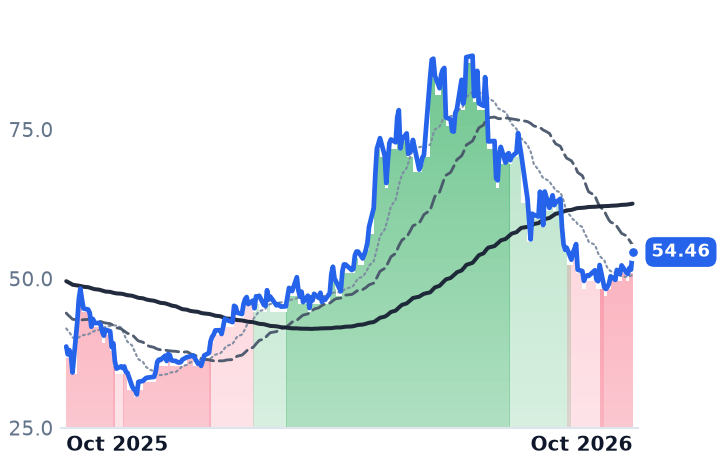
WOLF | Wolfspeed | Discrete & Power | 🔴 Cont. Bear | +24.4% | +34.8% |
| Compared against · context, not the story | |||||
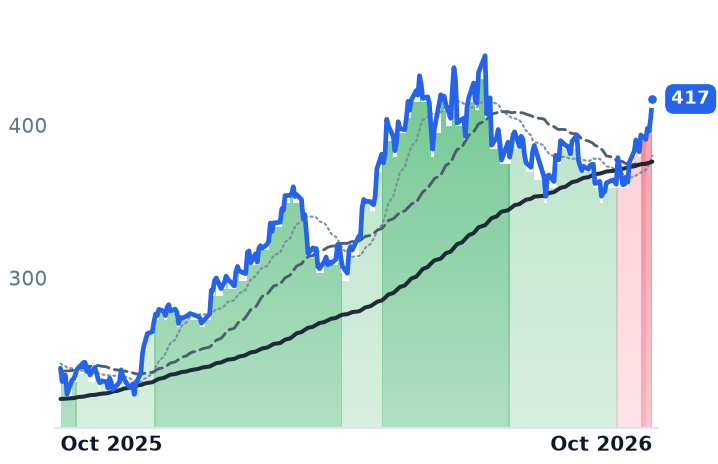
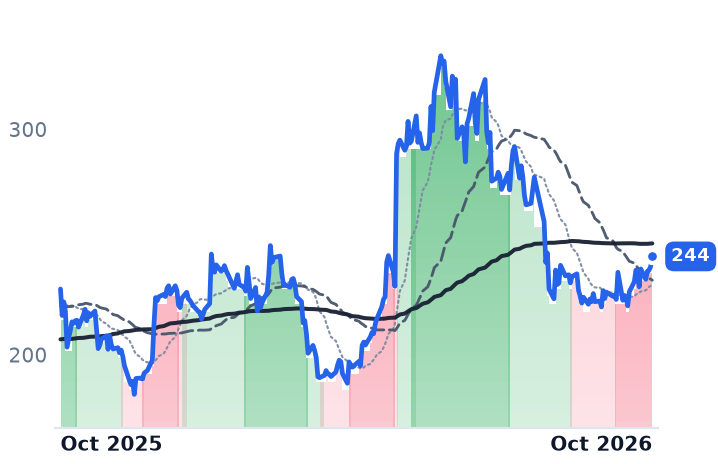
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | +13.7% | +64.9% |
STM | STMicroelectronics | Analog & Mixed-Signal | ⚠️ Emerging Bear | +9.6% | +99.2% |
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | +17.6% | +49.3% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | +15.2% | +73.2% |
NXPI | NXP Semiconductors | Analog & Mixed-Signal | ⚠️ Emerging Bear | +6.9% | +6.3% |
ALGM | Allegro MicroSystems | Other | ⚠️ Emerging Bear | +8.0% | +40.1% |
AOSL | Alpha and Omega Semiconductor | Analog & Mixed-Signal | 🔴 Cont. Bear | +20.0% | +7.8% |
POWI | Power Integrations | Analog & Mixed-Signal | ⚠️ Emerging Bear | +7.9% | +41.0% |
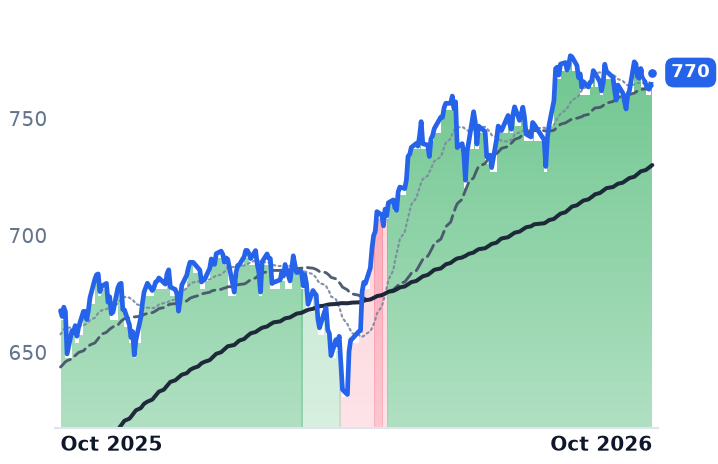
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.1% | +15.2% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +1.6% | +26.1% |
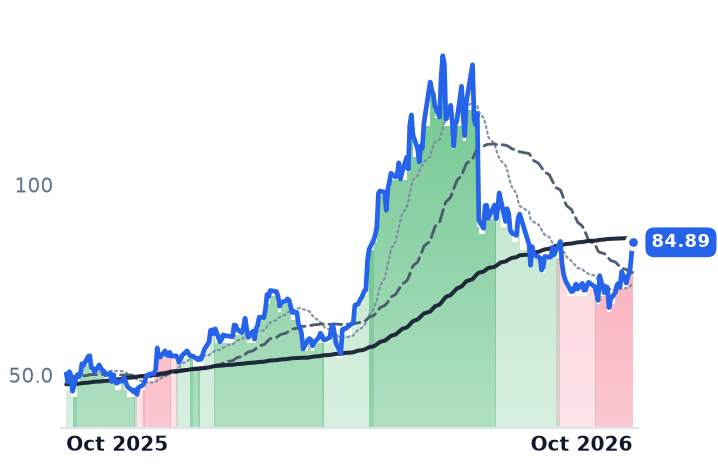
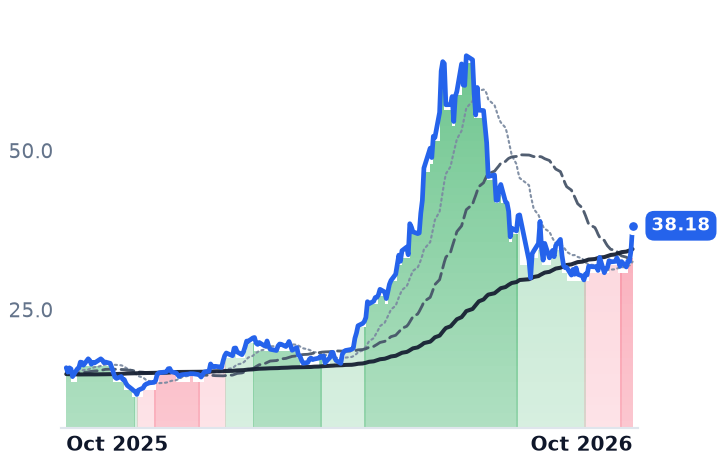
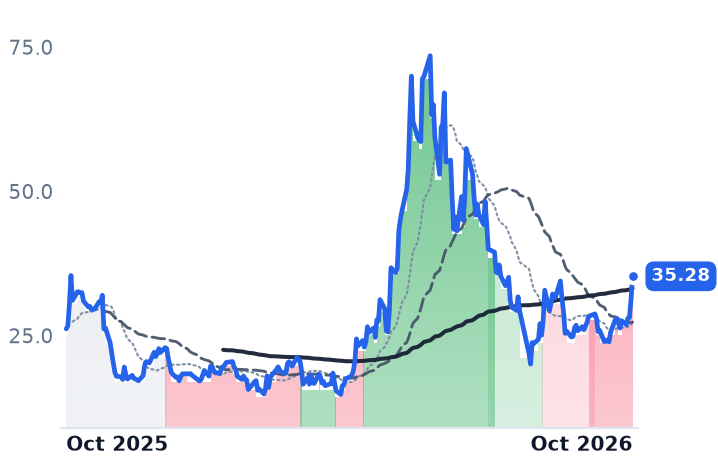
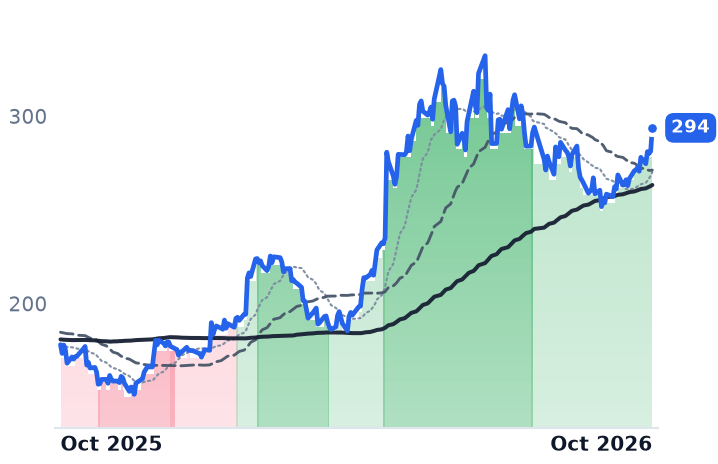
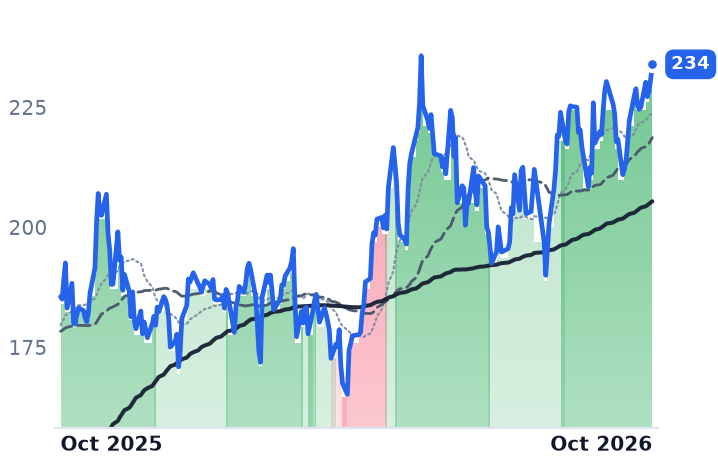
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $33.0B | 53.7x | 26.5x | 5.3x | 5.0x | 14.2x | 13.5x | 26.9x | 5.4% |
VSH | $5.4B | 147.2x | 45.3x | 1.3x | 1.5x | 6.2x | 6.9x | 14.3x | -0.1% |
WOLF | $1.8B | n/m | — | 2.8x | 2.9x | — | — | n/m | -19.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXN | $243.5B | 40.3x | 31.3x | 12.5x | 11.1x | 21.5x | 19.0x | 27.9x | 2.2% |
STM | $49.8B | 107.2x | 41.7x | 3.7x | 3.5x | 10.9x | 10.1x | 22.5x | 0.8% |
MPWR | $65.5B | 81.5x | 48.6x | 20.1x | 15.8x | 36.3x | 28.6x | 63.9x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADI | $191.7B | 46.5x | 30.6x | 13.8x | 12.7x | 21.0x | 19.3x | 30.4x | 2.6% |
NXPI | $57.5B | 19.4x | 15.1x | 4.4x | 4.0x | 7.8x | 7.2x | 13.3x | 5.1% |
ALGM | $6.8B | 448.3x | 35.3x | 7.2x | 6.2x | 15.2x | 13.1x | 66.3x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AOSL | $929.9M | n/m | — | 1.4x | 1.3x | 6.1x | 5.9x | n/m | -1.8% |
POWI | $3.5B | 136.5x | 44.7x | 7.7x | 7.2x | 14.4x | 13.5x | 84.1x | 2.3% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ON | Revenue | +9.2% | +13.1% | +13.9% |
| EPS | +37.1% | +40.9% | +30.2% | |
VSH | Revenue | +21.1% | +15.7% | +10.4% |
| EPS | −2763.2% | +111.4% | +48.1% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
TXN | Revenue | +24.0% | +13.8% | +10.6% |
| EPS | +55.6% | +20.7% | +17.1% | |
STM | Revenue | +22.4% | +18.7% | +13.2% |
| EPS | +104.2% | +98.3% | +45.6% | |
MPWR | Revenue | +49.2% | +28.7% | +20.2% |
| EPS | +54.8% | +31.0% | +20.2% | |
ADI | Revenue | +37.8% | +22.1% | +11.6% |
| EPS | +65.8% | +29.4% | +18.0% | |
NXPI | Revenue | +16.7% | +11.5% | +8.3% |
| EPS | +28.0% | +20.5% | +15.3% | |
ALGM | Revenue | +23.0% | +24.3% | +17.3% |
| EPS | +131.1% | +93.4% | +46.0% | |
AOSL | Revenue | −1.9% | +4.4% | +18.5% |
| EPS | −479.7% | −9.8% | −332.6% | |
POWI | Revenue | +7.7% | +14.2% | +20.8% |
| EPS | +14.8% | +34.8% | +43.0% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
onsemi's factories ran fuller in the June quarter than in March, and the company told investors there is room to run them fuller still without buying another tool. Utilization rose to 83% from 77% as the company ramped against a rising backlog, and management put the ceiling at 92% to 93% on equipment already installed.
That is the whole argument in power semiconductors. onsemi — a maker of power switches, energy-conversion parts, sensors and analog chips sold into cars, factories, solar and, increasingly, AI data centers — does not get paid for electrification in any way its revenue line makes legible. It earns the spread between a fixed base of fabs and silicon-carbide substrate operations committed years ago and the volumes customers actually pull today. Utilization, capital intensity and channel inventory decide whether a falling share price means lost demand or unabsorbed capacity. From its July 2 high of $91.22 the stock lost about 26% into a September 17 low; every one of those three operating measures moved the other way.
The absorption math
June-quarter revenue was $1,604m, up 9%, with GAAP gross margin of 38.4% and a non-GAAP figure of 39.3% — up eight-tenths of a point and a fourth consecutive quarter of expansion. Operating margin reached 16.1% and diluted earnings were $0.56 a share. Operating income grew 33.7%, more than three times the rate of sales. Capital spending was $34m, or 2.1% of revenue, with full-year intensity now guided below 5%. Distributor inventory drained to 10.1 weeks from 10.8 as sell-through outran sell-in, and company inventory fell nine days to 192.
"We delivered revenue, gross margin and earnings per share above the midpoint of guidance, reflecting strengthening demand, particularly across AI-driven applications," chief executive Hassane El-Khoury said in the August 3 results release. Silicon-carbide power-device revenue rose 12.5% sequentially to $215.7m, with China automotive silicon carbide guided up 60% to 70% this year. The base all of this is measured from was grim: 2025 revenue fell 15.3% to $5.995bn and gross margin collapsed to 33.1%. onsemi is the number-two merchant supplier of power silicon carbide, roughly 20% to 25% of the market behind STMicroelectronics, and vertically integrated into substrates since its 2021 purchase of GT Advanced Technologies.
The broad-line maker says the channel is empty too
Vishay Intertechnology, which sells MOSFETs, diodes, resistors, inductors and capacitors mostly through distributors, is the natural check: capacity expansion, no silicon-carbide story. Its June quarter produced a book-to-bill of 1.32 — 1.23 in semiconductors, 1.40 in passives — and backlog up 18% to $1.9bn, equal to 6.1 months of shipments, on revenue of $888.6m at a 23.3% gross margin. Distributor inventory fell to 18 weeks from 20 while point-of-sale rose 20.5% year on year. "The weeks of inventory has gone down each of the quarters," chief executive Joel Smejkal told investors on the August 5 call. "So the distributors, even though they speak about the need to replenish, they haven't been able to do it." Vishay's shares still fell about 17% over three months, and its 2026 capital budget of $400-440m — half of it a 12-inch German fab now in installation — is near 11% of consensus revenue.
Where the empty fab actually is
Wolfspeed, the pure-play wide-bandgap maker with 2,371 employees, is the genuine case. Fiscal fourth-quarter revenue was $149.6m, down 24.1%, with GAAP gross margin at -25% attributed explicitly to underutilization. It needs roughly $800m of annual revenue to break even and is running about $200m short; the materials business meant to be the moat shrank 45% to $43.3m. It emerged from a prepackaged Chapter 11 on September 29, 2025, cutting debt from about $6.7bn to roughly $2bn on a share count near 48m that could dilute past 90m. Its shares trade at 2.76x trailing sales and 2.85x forward — the forward figure is higher because the sell side models fiscal 2027 revenue falling to $643m. Industry-wide, front-end silicon-carbide utilization fell to roughly 50% in the 2024 correction while Chinese 6-inch substrate prices dropped from about $1,500 a wafer to about $500.
The verdict
All three peaked within a day of each other on July 2 and troughed in mid-September; the October 2 rebound was complex-wide, with Texas Instruments up 4.4% and STMicroelectronics 7.0% on a Mizuho note arguing Nvidia's Vera Rubin ramp arrives sooner and lifts power content per rack from about $15,000 to about $115,000 under 800-volt distribution. onsemi's analyst day, where it set 2030 targets of about $11bn revenue and 53% gross margin, landed hours before the Federal Reserve's first rate increase since 2023, to 3.75%-4.00%, and investors marked the targets down.
Wolfspeed's de-rating is earned by its own income statement. onsemi's and Vishay's are not explained by anything in their order books, and the likelier reading is rotation out of long-dated automotive and industrial earnings at a higher discount rate. But the cheapness at both is forward-dated and conditional: onsemi's 53.7x trailing earnings, down from 340.9x in May as trough quarters roll off, becomes 26.5x forward and about 18.9x on 2027 consensus of $4.50 a share only if earnings roughly double, and Vishay's 21.4x on 2027 estimates requires the German fab to convert on schedule.
The idle-fab story in power semiconductors is real; it is just that the idle fabs belong to Wolfspeed. onsemi's third-quarter report, expected around November 2, is where the rest of the premise gets a number attached to it.