

Aaron Ravenscroft Grew Manitowoc's Parts Business to $700m at 35% Margins
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
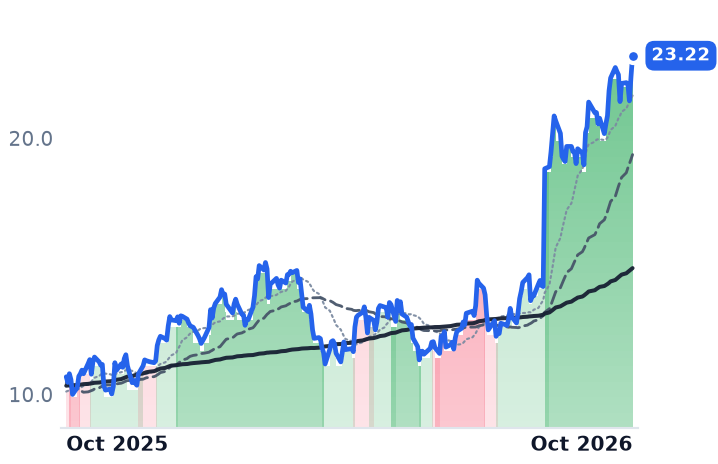
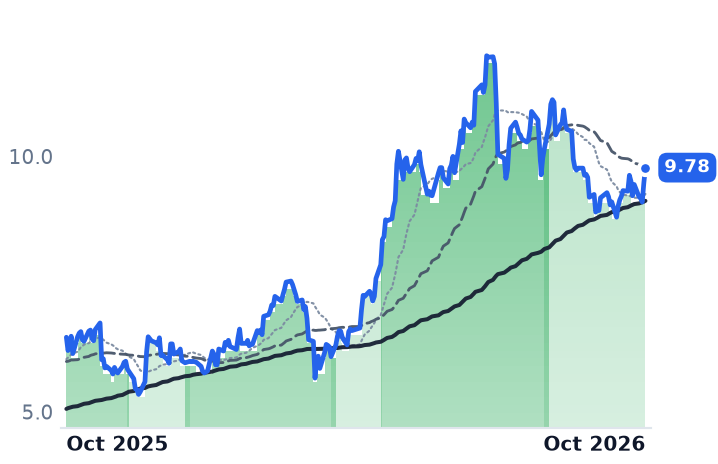
The smallest company among the listed crane makers and equipment renters has more than doubled in twelve months while the renters that buy its machines went nowhere, and the reason is a change in what it sells. Manitowoc's parts, service and remanufacturing revenue now exceeds $700m a year at gross margins near 35%, against roughly $375m six years ago, and large crawler cranes are sold out for 2027.
Second-quarter orders rose 56% year over year and backlog passed $1bn for the first time. The order book is earned; what it is earned on is narrow. United Rentals raised 2026 gross fleet spending twice, to $4.85–5.25bn, and realized a 52.9% recovery rate on used iron sold — the renters are funding the order book, not undercutting it. Terex's fall is tariffs and a mid-merger reorganization rather than lost demand.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
MTW | The Manitowoc | Industrial - Machinery | 🟢 Cont. Bull | +8.5% | +117.2% |
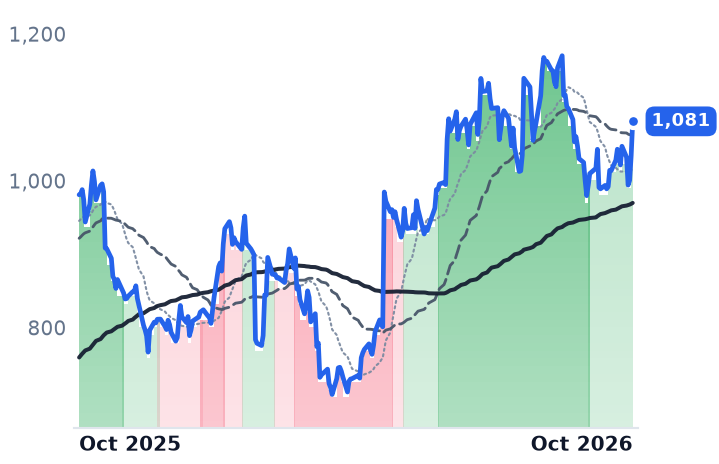
URI | United Rentals | Construction & Industrial Equipment | 🟢 Cont. Bull | +7.0% | +10.2% |
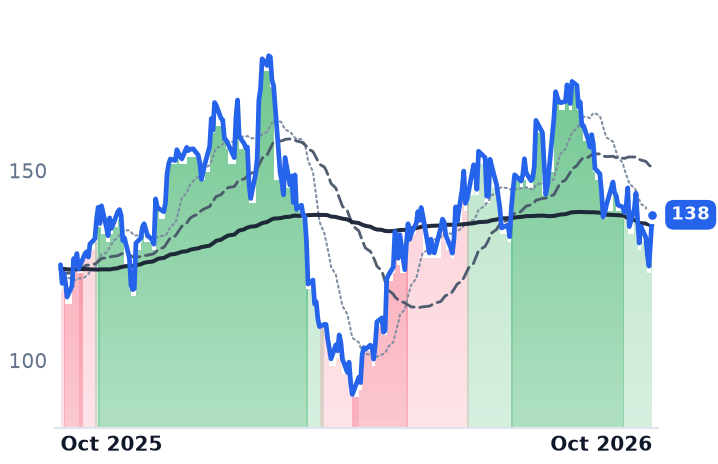
HRI | Herc | Construction & Industrial Equipment | 🟢 Cont. Bull | −1.8% | +10.5% |
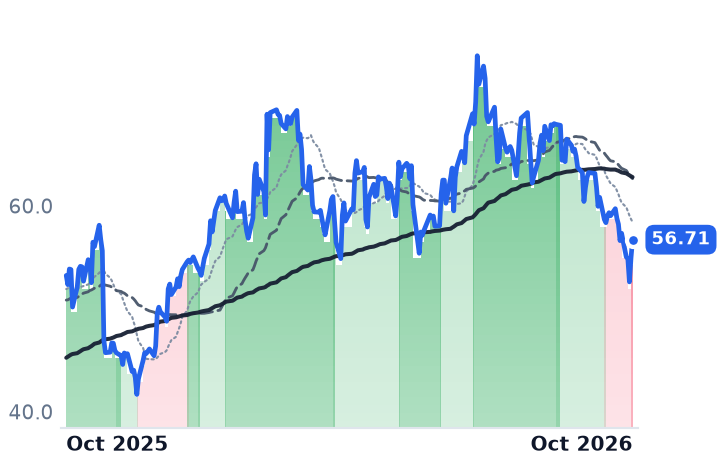
TEX | Terex | Aerial Work Platforms | 🟢 Cont. Bull | −10.3% | +6.5% |
CTOS | Custom Truck One Source | Construction & Industrial Equipment | 🟢 Cont. Bull | +6.4% | +51.4% |
TXT | Textron | Aircraft & Rotorcraft Manufacturers | ⚠️ Emerging Bear | −2.3% | −11.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MTW | $833.8M | 41.5x | 25.3x | 0.4x | 0.4x | 1.9x | 1.9x | 9.5x | 8.3% |
URI | $67.3B | 26.1x | 21.8x | 4.0x | 3.8x | 10.8x | 10.2x | 12.2x | 0.9% |
HRI | $4.6B | 94.1x | 19.4x | 1.0x | 0.9x | 3.3x | 3.2x | 12.6x | 2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TEX | $6.5B | 28.5x | 11.2x | 1.0x | 0.8x | 5.5x | 4.5x | 19.8x | 5.2% |
CTOS | $2.2B | 103.7x | 72.4x | 1.1x | 1.0x | 5.4x | 5.2x | 10.1x | -4.9% |
TXT | $13.3B | 14.6x | 11.9x | 0.9x | 0.9x | 5.3x | 5.2x | 9.2x | 5.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MTW | Revenue | +5.3% | +1.5% | +2.0% |
| EPS | +179.6% | −0.1% | −21.4% | |
URI | Revenue | +10.0% | +8.7% | +8.8% |
| EPS | +15.9% | +15.8% | +13.3% | |
HRI | Revenue | +12.0% | +8.2% | +7.6% |
| EPS | −1.8% | +53.8% | +40.5% | |
TEX | Revenue | +50.5% | +8.0% | +5.3% |
| EPS | +2.2% | +18.6% | +14.4% | |
CTOS | Revenue | +6.2% | +5.4% | +3.3% |
| EPS | −184.5% | +119.8% | +61.8% | |
TXT | Revenue | +6.7% | +5.6% | +3.7% |
| EPS | +13.1% | +5.6% | +12.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Manitowoc booked $709m of crane orders in the second quarter and ended it with a backlog above $1bn for the first time in its history. The maker of Grove mobile cranes, Potain tower cranes and lattice-boom crawlers is the smallest company on this shelf, worth $834m of equity, and its shares have more than doubled over the past twelve months while the equipment renters that are its largest customers barely moved.
What changed is the mix. Parts, field service, remanufacturing, training and telematics — everything that is not a new machine — now bring in more than $700m a year, up from roughly $375m six years ago, at gross margins of about 35%. Non-new-machine sales have risen 84% since 2020, and the company's stated target is $1bn, or half of total revenue. That is a deliberate retreat from the part of the business that breaks in every downturn.
"We spent 100 years focused on the most volatile, cyclical, lowest-margin portion of the crane industry," chief executive Aaron Ravenscroft said in August 2026.
The second quarter showed what the mix does to profit. Revenue rose 10.3% to $594.9m while gross profit rose 24.3% and operating income nearly tripled to $31.1m. Adjusted earnings of $0.46 a share beat a consensus of $0.11, and the shares rose 32% on August 7. About $750m of the $1.05bn backlog ships this year; large crawler cranes are sold out for 2027 on data-center work. At 9.5 times trailing earnings before interest, taxes, depreciation and amortization and 1.19 times book value, with a trailing free cash flow yield of 8.3%, the shares are not expensive against the assets. Earnings multiples are less useful here: a 2.4% net margin makes the 41.5x trailing figure hostage to small swings, and the published forward estimate rests on a single analyst.
The renters are buying, not liquidating
The original worry about this group was that rental fleets sell three-to-seven-year-old machines into the same market the manufacturers must price against, so softening residual values would squeeze returns and cut orders. The numbers say the opposite. United Rentals, which rents construction and industrial equipment from roughly 1,360 locations, recovered 52.9% of original equipment cost on fleet sold in the second quarter — up from 50.0% two quarters earlier — generating $330m of proceeds. "We sold $624 million of OEC at a 53 percent recovery rate," chief executive Matthew Flannery said after the July 23 results, adding the company was on track to sell about $2.8bn of fleet this year "supported by strong demand for used equipment." It then raised 2026 gross fleet capital spending to $4.85–5.25bn, the second increase of the year.
Its own results accelerated — revenue up 11.8% to $4.41bn, gross margin 39.3%, up from 36.1% — and the shares still fell slightly over three months. At 26.1 times trailing earnings against about 21.9x on the same basis in early January, the de-rating in trend terms is the multiple, not the operations. Herc Holdings, which outbid United Rentals for H&E, is the leveraged version: rental revenue up 2% on roughly 3% less average fleet, net leverage of 3.95x and quarterly interest of $126m against $86m a year earlier. Custom Truck One Source, which builds and rents utility and telecom trucks, averaged 81.6% rental utilization, up four percentage points, raised guidance, and rebuilt backlog above $340m after record deliveries.
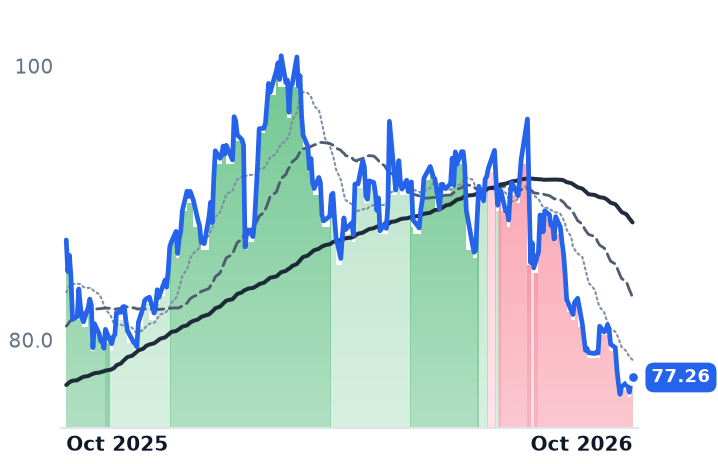
Terex is the one name down hard, 16.8% over three months, and its problem is not demand. Aerials bookings rose 71% year over year and segment sales rose 10.9% to $673m, but segment margin fell 3.4 percentage points to 5.7% on tariff costs. Meanwhile it is mid-merger with REV Group and has put the Genie aerials business up for sale to reduce cyclical exposure, with no buyer announced. At 11.3 times 2026 consensus earnings and 1.31 times book it is the cheapest of the group, and it is also the one whose shape next year is unknown.
What the split actually means
The line does not run between companies that own iron and companies that build it. Manitowoc's gain is earned at the order book and the margin line, and the aftermarket shift means a slower 2028 crane cycle no longer takes the whole income statement with it. United Rentals' flat shares sit against record results, which leaves interest rates and the multiple as the likelier explanation — the group rose together on October 2 after payrolls came in at 29,000, cooling rate expectations. Terex's loss is input cost and corporate reorganization, and a Genie sale would settle it one way or the other.
The shared exposure is the buyer. Data centers account for nearly all of the $78bn increase in US commercial construction forecast for 2026; strip them out and nonresidential building contracts. Manitowoc's crawler lines are full through 2027. The orders that fill 2028 have to come from the same handful of balance sheets J.P. Morgan expects to spend $697bn on data centers next year, and from nothing else that has yet appeared in anyone's backlog.