

A $562m Goodwill Charge Turned Trimble's 11% Growth Quarter Into a $471.7m Loss
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Trimble's reported bottom line says the business broke; the operating numbers say it accelerated. The same quarter produced record recurring revenue of $2.51bn, up 14%, a raised full-year revenue forecast of $3.90–3.95bn and a new $1.00bn repurchase authorization.
The write-down is non-cash. It marks down goodwill created largely by the roughly $2.1bn Transporeon acquisition, and the transportation unit that produced it is now under strategic review after inbound interest.
The judgment: a category repricing, not a demand break. Autodesk, Bentley and Procore each grew low-to-mid teens last quarter and each raised guidance or reported record profitability, and all four trade well below spring levels. On forward earnings Trimble, at 15.7x, is cheaper than the other three; Procore, at 30.3x, is the most expensive.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
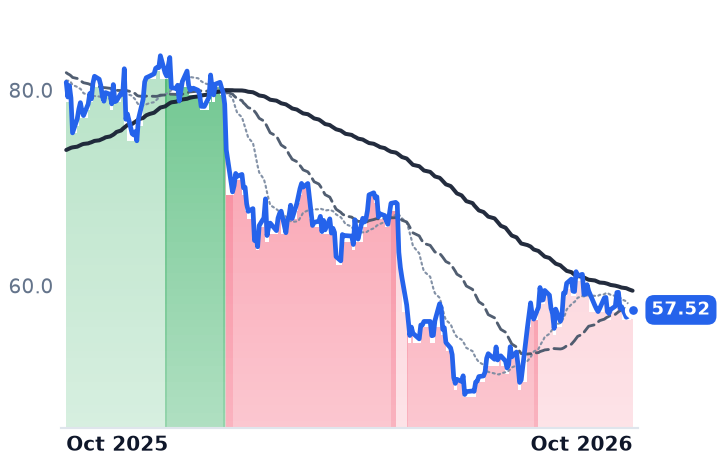
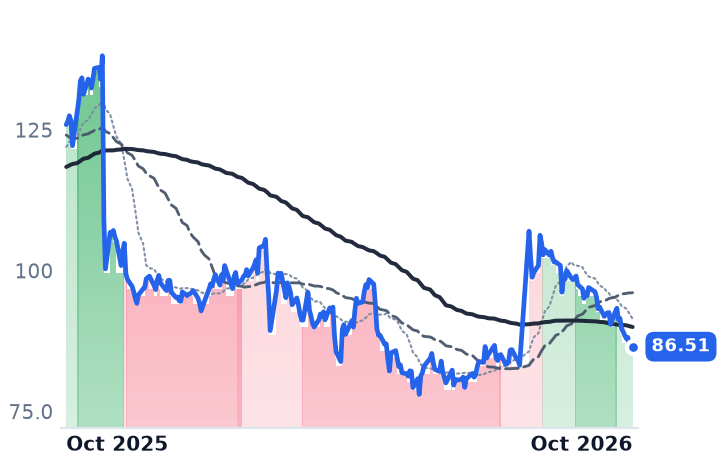
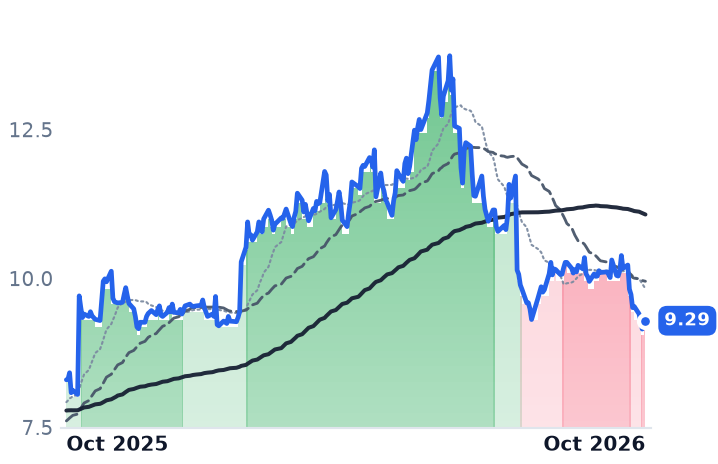
TRMB | Trimble | Data Infrastructure & Software Solutions | 🔴 Cont. Bear | −3.3% | −28.8% |
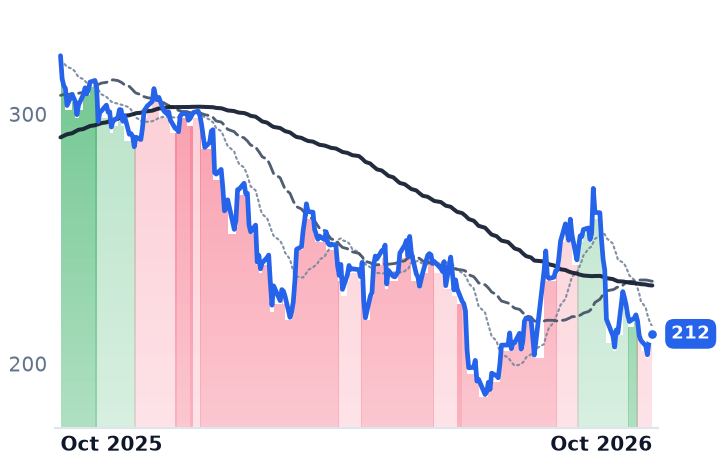
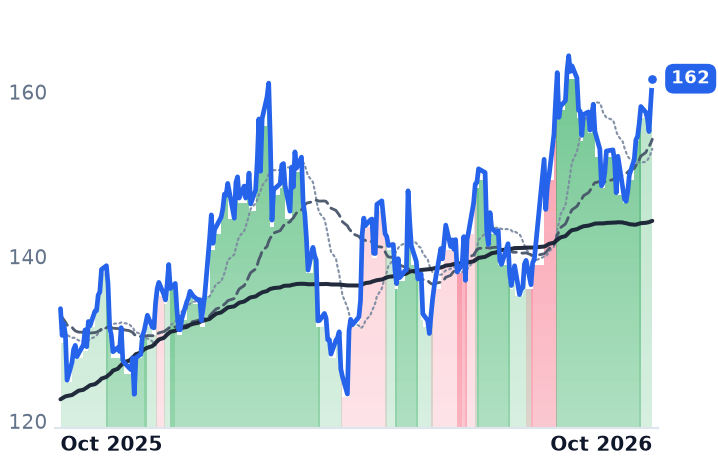
ADSK | Autodesk | Design & Content Creation | 🔴 Cont. Bear | −2.7% | −34.5% |
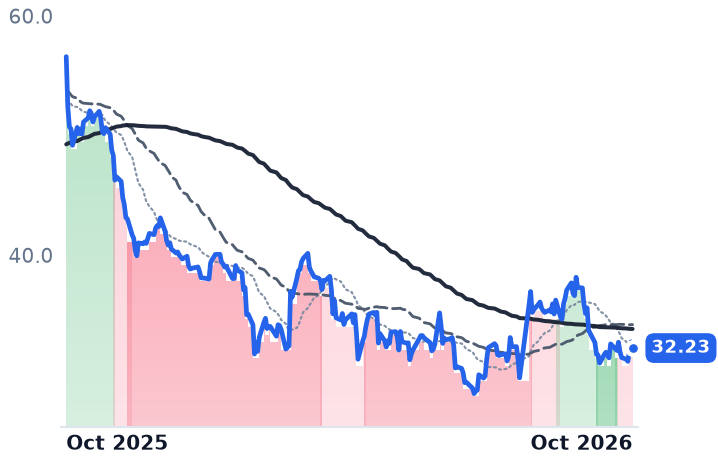
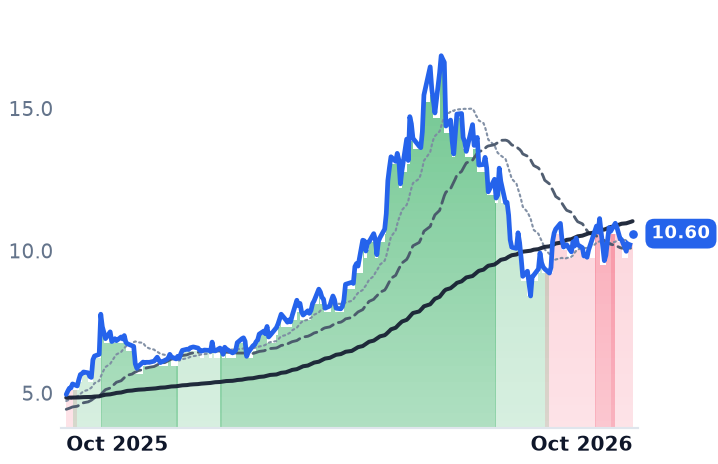
BSY | Bentley Systems, Incorporated | Specialized Enterprise Solutions | 🔴 Cont. Bear | −4.4% | −43.1% |
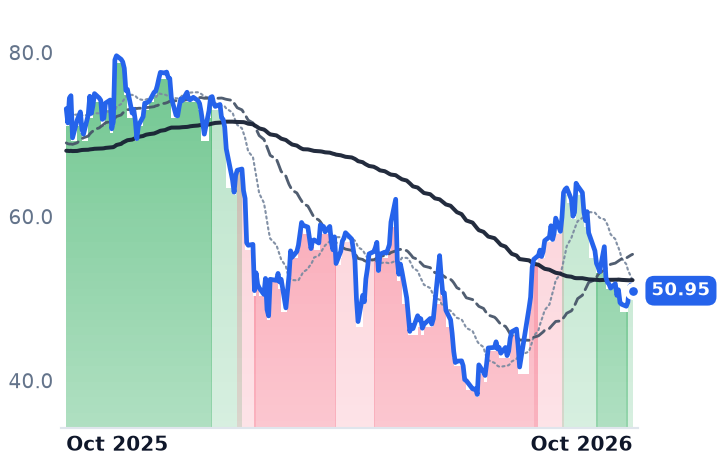
PCOR | Procore Technologies | Specialized Enterprise Solutions | 🔴 Cont. Bear | −12.2% | −30.3% |
ITRI | Itron | Data Infrastructure & Software Solutions | 🌱 Emerging Bull | −10.8% | −31.3% |
EMR | Emerson Electric | Industrial Automation & Controls | 🟢 Cont. Bull | +5.8% | +20.9% |
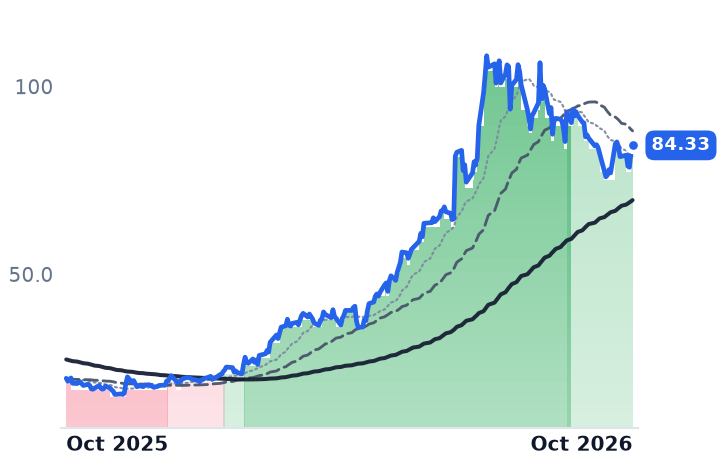
ATEX | Anterix | Technology & Services | 🟢 Cont. Bull | −2.2% | +278.3% |
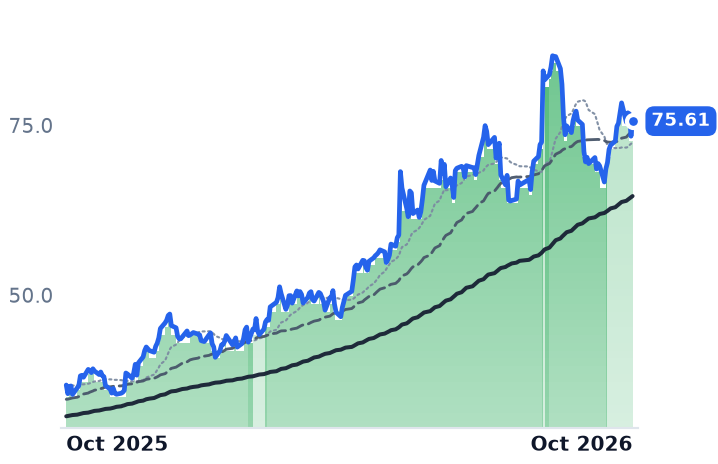
DGII | Digi International | IoT & Edge Connectivity | 🟢 Cont. Bull | +9.0% | +105.7% |
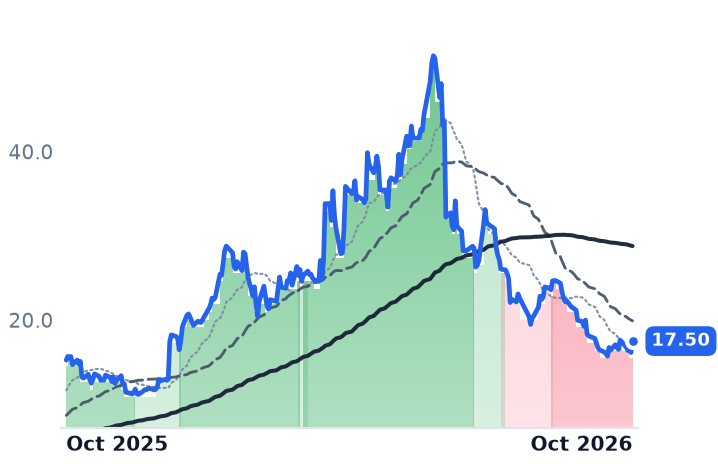
ORCL | Oracle | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | −10.4% | −50.8% |
MSI | Motorola Solutions | Wireless & Mobile Networks | 🌱 Emerging Bull | −4.4% | −1.5% |
FTNT | Fortinet | Network Security Appliances | 🟢 Cont. Bull | +15.8% | +109.5% |
CSCO | Cisco Systems | Enterprise Networking Infrastructure | 🟢 Cont. Bull | +2.7% | +65.2% |
ERIC | Telefonaktiebolaget LM Ericsson (publ) | Wireless & Mobile Networks | ⚠️ Emerging Bear | −8.0% | +12.0% |
NOK | Nokia Oyj | Optical Transport & Switching | ⚠️ Emerging Bear | +5.7% | +114.1% |
PL | Planet Labs PBC | Unmanned Systems & ISR | ⚠️ Emerging Bear | −3.4% | +14.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TRMB | $13.4B | n/m | 15.7x | 3.5x | 3.4x | 5.2x | 5.0x | 55.7x | 4.1% |
ADSK | $44.8B | 27.3x | 16.8x | 5.7x | 5.4x | 6.3x | 5.9x | 19.2x | 6.3% |
BSY | $9.4B | 35.0x | 23.0x | 5.9x | 5.6x | 7.2x | 6.8x | 21.0x | 5.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCOR | $7.7B | n/m | 30.3x | 5.4x | 5.1x | 6.8x | 6.4x | 120.0x | 3.8% |
ITRI | $3.8B | 14.2x | 13.5x | 1.6x | 1.6x | 4.1x | 4.0x | 8.0x | 10.1% |
EMR | $90.5B | 35.2x | 22.1x | 4.9x | 4.5x | 9.1x | 8.5x | 19.9x | 3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ATEX | $1.6B | 24.0x | — | 233.5x | 76.0x | 233.5x | 76.0x | 780.2x | 0.9% |
DGII | $2.9B | 58.2x | 24.1x | 5.6x | 4.9x | 8.8x | 7.7x | 29.6x | 4.7% |
ORCL | $409.9B | 22.0x | 17.5x | 5.7x | 4.5x | 8.9x | 7.1x | 14.0x | -7.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MSI | $74.3B | 34.8x | 25.3x | 6.1x | 5.7x | 12.1x | 11.5x | 21.9x | 3.6% |
FTNT | $132.8B | 63.3x | 52.5x | 17.6x | 16.4x | 21.9x | 20.3x | 45.0x | 2.3% |
CSCO | $442.2B | 33.4x | 22.0x | 7.0x | 6.1x | 10.8x | 9.4x | 23.2x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ERIC | $30.5B | 12.6x | — | 1.3x | — | 2.8x | — | 6.6x | 10.1% |
NOK | $57.2B | 74.2x | 30.6x | 2.6x | 2.7x | 5.8x | 6.1x | 19.4x | 1.0% |
PL | $5.8B | n/m | — | 15.4x | 13.3x | 27.8x | 24.0x | n/m | 0.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TRMB | Revenue | −2.1% | +10.2% | +7.9% |
| EPS | +8.8% | +18.8% | +12.7% | |
ADSK | Revenue | +17.0% | +16.1% | +11.0% |
| EPS | +23.0% | +23.0% | +12.5% | |
BSY | Revenue | +13.6% | +10.5% | +10.2% |
| EPS | +18.5% | +12.4% | +16.2% | |
PCOR | Revenue | +15.3% | +13.9% | +14.4% |
| EPS | +24.1% | +46.2% | +20.2% | |
ITRI | Revenue | +1.3% | +6.5% | +6.0% |
| EPS | −6.4% | +8.0% | +15.8% | |
EMR | Revenue | +4.5% | +5.6% | +5.4% |
| EPS | +9.4% | +11.2% | +10.8% | |
ATEX | Revenue | −2.2% | +256.4% | −9.5% |
| EPS | −316.3% | −126.0% | +75.2% | |
DGII | Revenue | +24.8% | +8.7% | +4.5% |
| EPS | +31.4% | +16.3% | +8.4% | |
ORCL | Revenue | +17.8% | +34.4% | +45.3% |
| EPS | +25.3% | +8.7% | +35.4% | |
MSI | Revenue | +11.4% | +6.5% | +6.8% |
| EPS | +16.8% | +8.3% | +10.7% | |
FTNT | Revenue | +20.2% | +11.3% | +11.1% |
| EPS | +28.0% | +9.4% | +13.1% | |
CSCO | Revenue | +11.1% | +15.9% | +6.9% |
| EPS | +12.9% | +19.2% | +8.7% | |
ERIC | Revenue | +0.2% | +1.9% | +2.5% |
| EPS | −28.0% | +15.6% | +10.1% | |
NOK | Revenue | +6.1% | +7.1% | +6.8% |
| EPS | +34.8% | +19.3% | +17.8% | |
PL | Revenue | +21.9% | +46.7% | +30.2% |
| EPS | −55.9% | −40.8% | −129.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Trimble, which sells survey and machine-guidance hardware alongside the design, project and freight software that consumes the data those machines capture, wrote $562m off the value of its transportation business last quarter. In the same August 12 release it raised its revenue forecast for the year and authorized a new $1.00bn share repurchase.
The charge is non-cash and backward-looking. It marks down goodwill created largely by the roughly $2.1bn Transporeon purchase, and it converts Trimble's reported result into a $471.7m net loss, or $2.02 a diluted share, in a quarter when the operating business grew faster than it has since 2024. That is the stake: the engineering-software companies Trimble trades alongside have lost between a quarter and two-fifths of their value over twelve months on the argument that artificial intelligence will erode software revenue, and Trimble is now the one where a screen on trailing earnings returns a negative number.
The quarter underneath the charge
Second-quarter revenue was $972.0m, up 11% reported and 10% organic. The sequence matters more than the level: revenue fell 1.4% year on year in the fourth quarter of 2025, then grew 11.8% in the first quarter of 2026 and 11.0% in the second. Gross margin reached 69.4% against 68.3% a year earlier, and non-GAAP operating income of $260.6m was 26.8% of revenue. Annualized recurring revenue hit a record $2.51bn, up 14% as reported and 12% organic, and full-year revenue guidance went to $3.90–3.95bn, roughly 9% growth. The architecture, engineering and construction software unit carried it, with recurring revenue of $1.577bn, up 14%, and Field Systems at $399m, up 12%.
Chief executive Rob Painter told investors on the second-quarter call that Trimble is "already monetizing AI today through stand-alone offerings and hybrid license and consumption models", citing estimating tools that automate the measuring of blueprints, with early customers reporting time savings of up to 60%.
The impaired unit is now in play
Having written down transportation and logistics, Trimble opened a strategic review of the transport business after inbound interest. The accounting consequence is that trailing multiples are unusable — a reported price/earnings of -122x, an EV/EBITDA of 55.7x — leaving forward earnings as the only workable anchor at 15.7x against 2027 consensus of $3.67 a share. Those same estimates embed 10% revenue growth in 2027 to $3.93bn at a 30% operating margin.
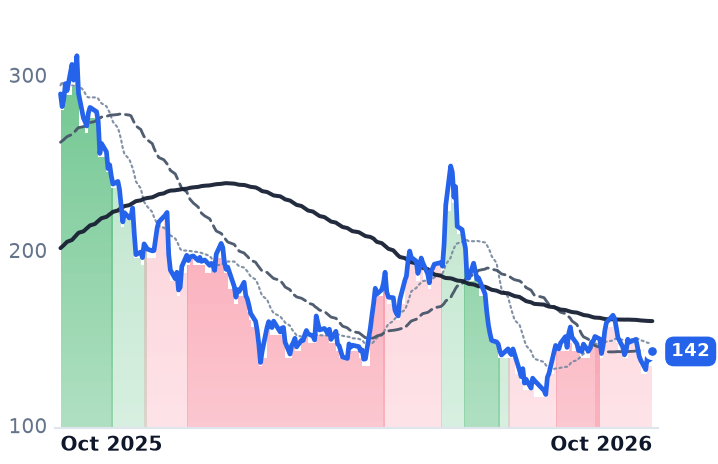
The shares reflect none of it. At $57.52 Trimble is down 28% over twelve months and 12% over six, and its 50-day average has sat below its 200-day without interruption since the start of April — alone among these four in never climbing out of a downtrend, including during the mid-September rally the others caught. Analysts moved from bearish to neutral, citing limited near-term catalysts despite the improved earnings power.
The group was marked down together
The comparison set did not deteriorate either. Autodesk, which sells design and engineering software including AutoCAD and Revit, grew revenue 16.1% to $2.046bn at a 91% gross margin and raised fiscal 2027 billings guidance to $8.575–8.65bn, with construction growing north of 20%; it trades at 16.8x forward earnings against 27.3x trailing, and is down 34% over twelve months. Bentley Systems, which sells infrastructure-engineering software to civil, structural and utility engineers, reported recurring revenue of $1,536m, up 12% in constant currency on revenue up 12.8%; at 23.0x forward it has lost 42% in a year. Procore, a cloud construction-management platform, grew revenue 15.8% to $375.2m and posted its first-ever quarter of GAAP operating profitability while raising guidance to $1.510–1.514bn; at 30.3x forward it is the most expensive of the four, and it does not sell seats at all — it prices on annual construction volume with unlimited users.
Autodesk's Andrew Anagnost put the rebuttal plainly on the company's August 27 call: "The future of AI won't belong to the company with the best single model. It will belong to the platform that combines the richest context with the right models to deliver the best outcomes for customers."
What the discount is actually pricing
Trimble earns part of its de-rating. A company reporting a half-billion-dollar loss disappears from earnings screens, and a strategic review means the shape of the remaining company — its revenue base, its growth rate, its recurring mix — stays genuinely unsettled until the review concludes.
The rest is unexplained by the business. Accelerating organic growth, a record recurring base, a raised forecast and a fresh buyback authorization are not the inputs to a 28% annual decline. And the four did not split by growth rate or by pricing model: they were compressed as one category, their relative ordering intact, Procore still the dearest and Trimble still the cheapest on forward earnings. That is a verdict on what investors will pay for engineering software, not on how much of it gets sold.
Which leaves Trimble's next move partly out of its own hands. The figure that decides the company's shape will not appear in a guidance range — it is whatever someone offers for the transport unit Trimble has already told the market is worth $562m less.