

AEP's Transmission Rates Reset to $1.44bn for 2026 Without a Rate Case
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two big regulated utilities are building into the same data-center load and fell about the same amount this quarter, but only one of them is already being paid for what it spends. American Electric Power's East transmission companies had their rates reset on 1 January by a formula filed at the Federal Energy Regulatory Commission, lifting the annual revenue requirement to $1.44bn from $1.257bn, with the prior year trued up and billed with interest at an allowed 9.85% return plus a half-point regional adder.
Entergy's Louisiana rates for 2026 were instead set off a 2025 test year, and its June quarter showed the cost of waiting: revenue up 5.9% but diluted earnings of $1.03 a share against $1.05, on a share count up 4.6%. A sector-wide discount-rate shock explains most of both declines. Only one of the two multiples looks like it is paying for a lag.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
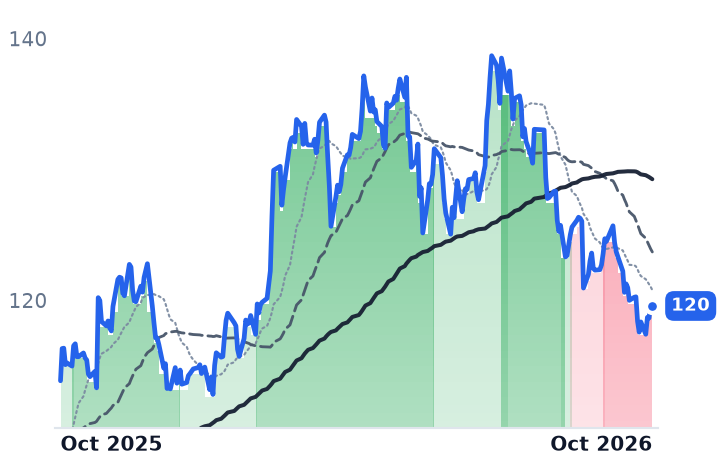
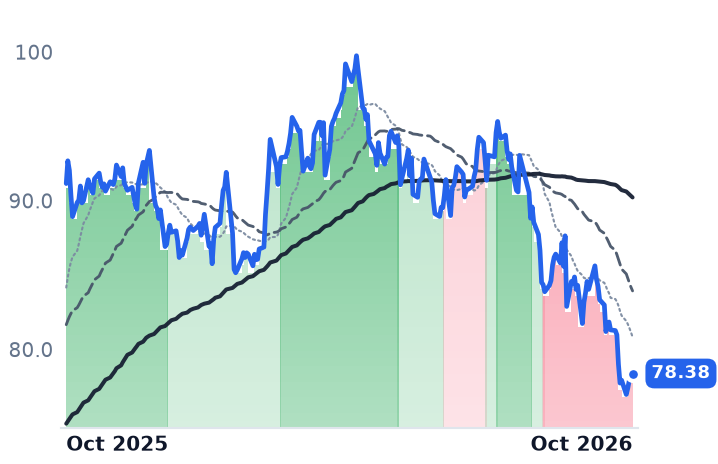
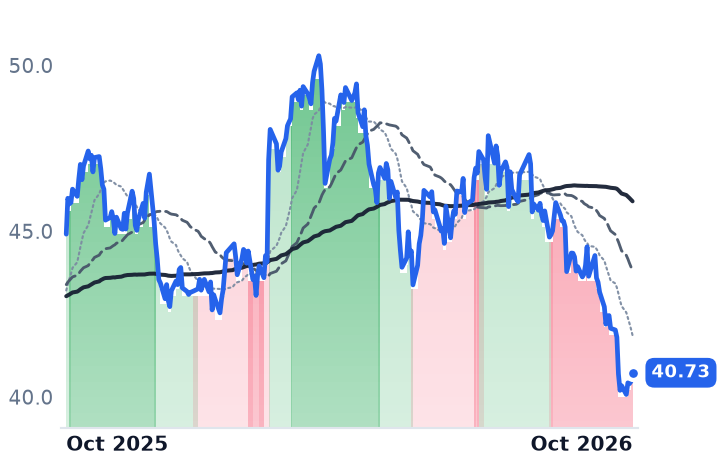
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | −4.0% | +5.0% |
ETR | Entergy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.9% | +4.9% |
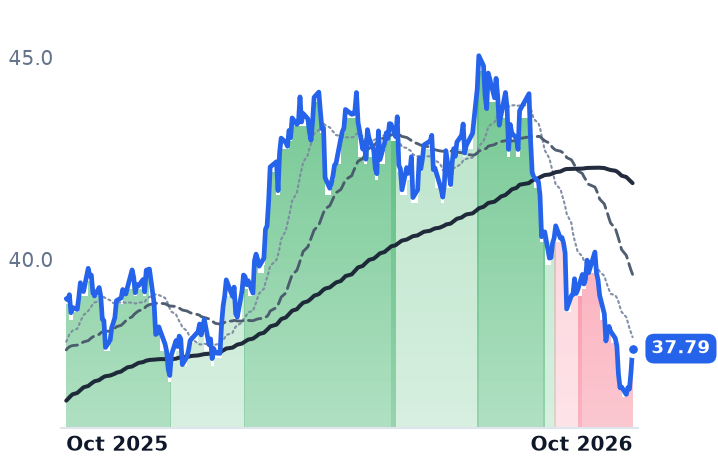
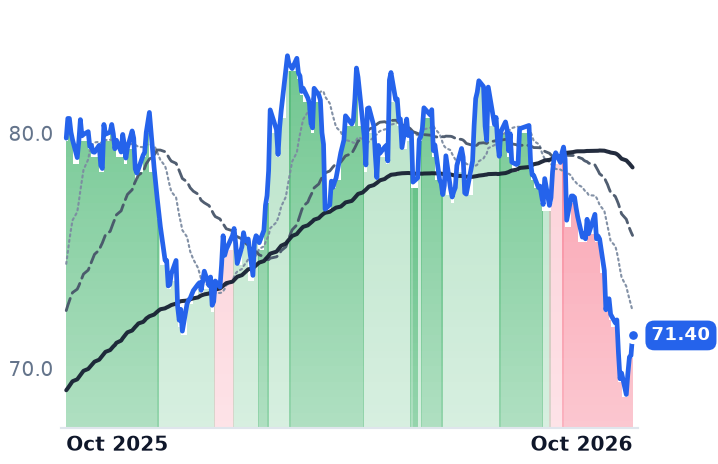
NEE | NextEra Energy | Vertically Integrated Utilities | 🔴 Cont. Bear | −7.9% | −5.2% |
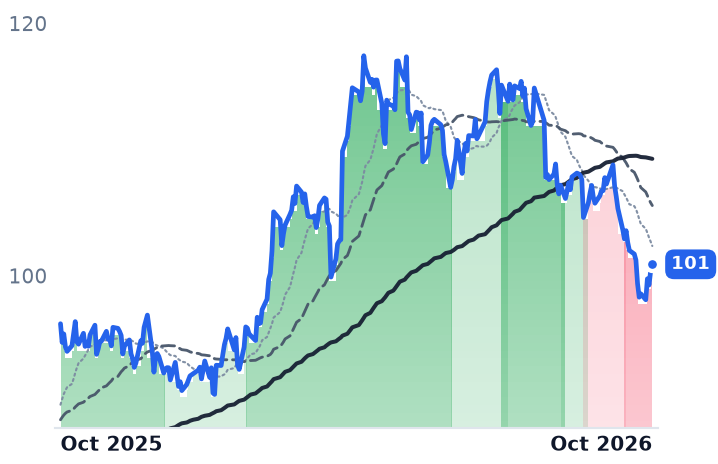
FTS | Fortis | Regional/International Utilities | ⚠️ Emerging Bear | −4.3% | +5.6% |
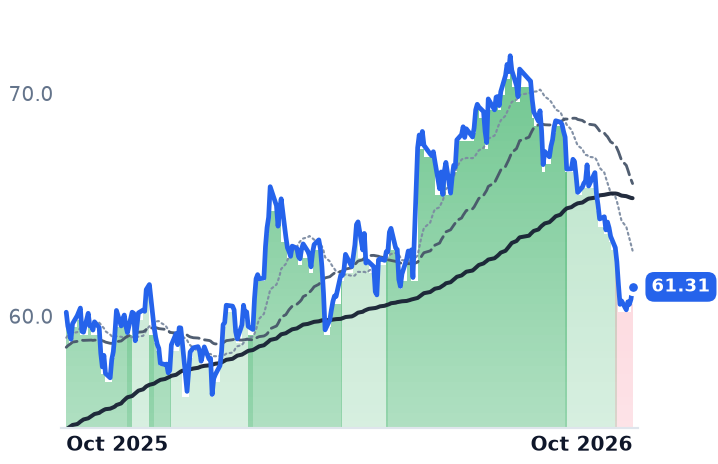
SRE | Sempra | US Electric & Gas Utilities | ⚠️ Emerging Bear | −6.7% | −14.0% |
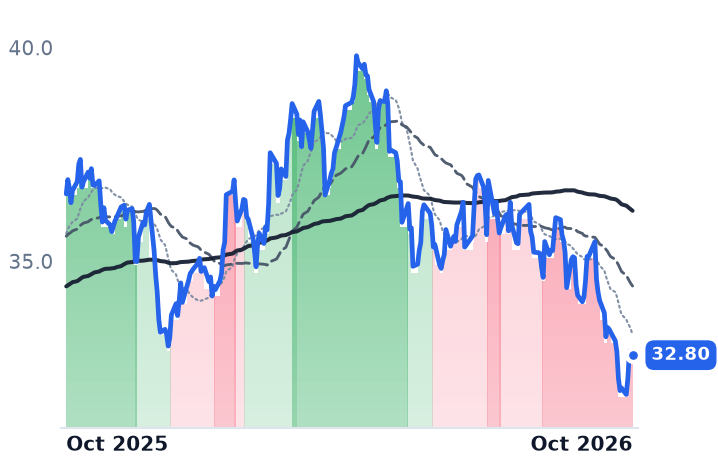
CNP | CenterPoint Energy | US Electric & Gas Utilities | ⚠️ Emerging Bear | −4.7% | −3.2% |
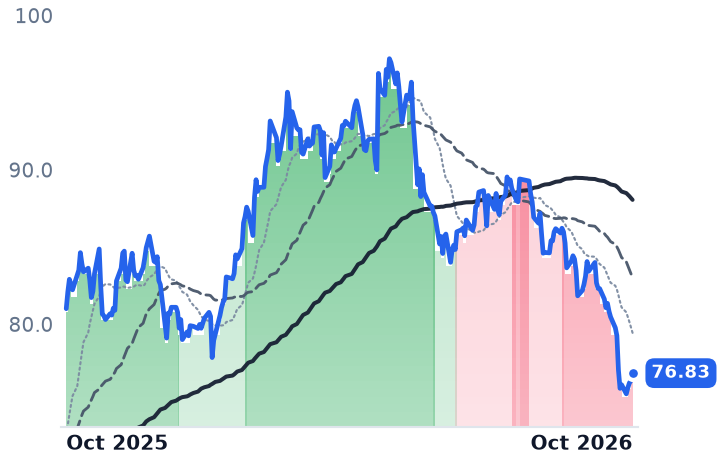
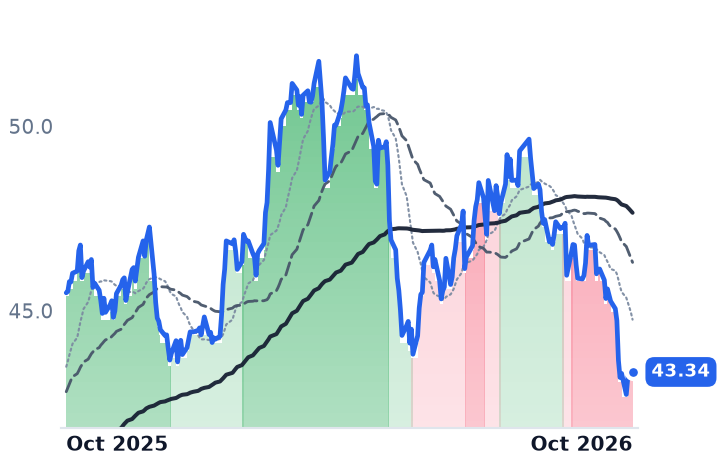
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −6.9% | +1.9% |
FE | FirstEnergy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −7.3% | −4.7% |
EXC | Exelon | Vertically Integrated Utilities | ⚠️ Emerging Bear | −6.7% | −9.3% |
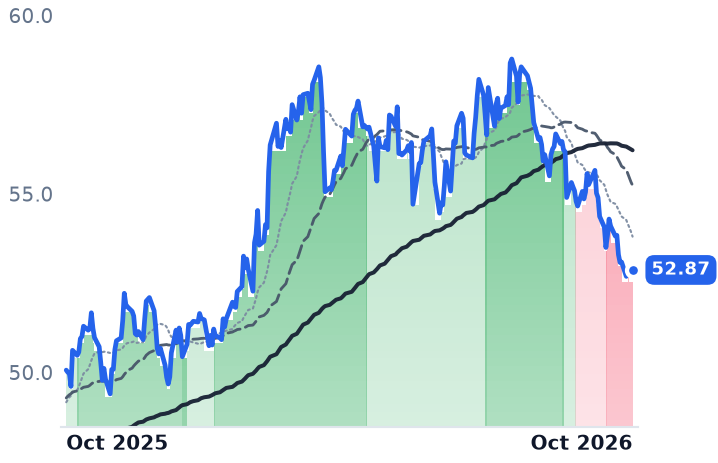
XEL | Xcel Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.7% | −10.5% |
PPL | PPL | Transmission & Distribution Only | 🔴 Cont. Bear | −6.6% | −10.3% |
| Compared against · context, not the story | |||||
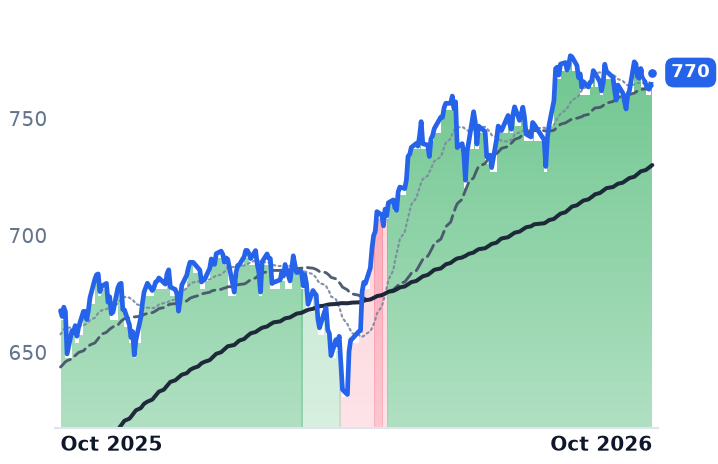
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.1% | +15.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEP | $65.1B | 20.5x | 18.7x | 2.9x | 2.8x | 5.9x | 5.7x | 13.7x | 13.8% |
ETR | $47.1B | 25.5x | 22.9x | 3.5x | 3.4x | 9.0x | 8.7x | 13.9x | -6.7% |
NEE | $160.3B | 17.2x | 19.3x | 5.5x | 5.2x | 7.7x | 7.2x | 15.1x | -6.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FTS | $26.9B | 22.1x | 14.7x | 3.1x | 2.1x | 11.0x | 7.6x | 12.3x | -4.9% |
SRE | $51.2B | 22.6x | 15.3x | 3.8x | 3.8x | 9.0x | 9.1x | 13.5x | -11.5% |
CNP | $24.9B | 22.2x | 19.8x | 2.6x | 2.5x | 4.8x | 4.6x | 12.4x | -10.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
D | $53.9B | 21.2x | 17.1x | 2.9x | 2.9x | 6.0x | 5.9x | 14.6x | -12.7% |
FE | $25.1B | 23.1x | 15.9x | 1.6x | 1.6x | 3.0x | 3.0x | 11.6x | 6.3% |
EXC | $42.0B | 14.9x | 14.3x | 1.7x | 1.6x | 6.8x | 6.7x | 10.3x | -4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
XEL | $44.6B | 19.5x | 17.3x | 3.1x | 2.9x | 6.2x | 5.9x | 12.7x | -17.2% |
PPL | $24.7B | 26.3x | 16.8x | 3.5x | 2.5x | 10.2x | 7.4x | 13.4x | 1.0% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AEP | Revenue | +9.4% | +5.9% | +7.6% |
| EPS | +8.0% | +7.5% | +10.6% | |
ETR | Revenue | +8.6% | +9.8% | +9.8% |
| EPS | +12.3% | +16.1% | +13.6% | |
NEE | Revenue | +8.9% | +9.7% | +9.0% |
| EPS | +7.5% | +9.0% | +8.6% | |
FTS | Revenue | +0.1% | +7.2% | +10.2% |
| EPS | +3.4% | +7.3% | +6.0% | |
SRE | Revenue | −4.2% | −1.5% | +1.7% |
| EPS | +11.6% | +8.1% | +8.4% | |
CNP | Revenue | +8.9% | +3.7% | +5.1% |
| EPS | +8.4% | +9.2% | +9.3% | |
D | Revenue | +14.4% | +6.4% | +6.1% |
| EPS | +5.1% | +6.3% | +6.9% | |
FE | Revenue | +10.0% | +5.3% | +5.3% |
| EPS | +7.2% | +8.0% | +8.0% | |
EXC | Revenue | +5.2% | +2.9% | +3.4% |
| EPS | +5.5% | +6.3% | +7.2% | |
XEL | Revenue | +5.7% | +10.5% | +8.3% |
| EPS | +8.2% | +10.4% | +10.6% | |
PPL | Revenue | +10.3% | +5.8% | +5.5% |
| EPS | +7.7% | +8.7% | +8.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Paid in the year it spends
On 1 January the network service rate charged by American Electric Power's eastern transmission companies rose to $60,050.97 per megawatt-year from $56,289.43. No commission heard argument over it. The figure is the output of a forward-looking formula on file at the Federal Energy Regulatory Commission, computed off the coming year's projected costs, lifting the annual revenue requirement those companies collect to $1.44bn from $1.257bn, with the prior rate year's difference trued up and billed with interest at an approved 9.85% base return on equity plus a 50 basis-point adder — half a percentage point — for membership in a regional transmission organization.
That machinery is why AEP, the Columbus, Ohio holding company whose four segments include a standalone transmission arm, is a different business from most of the regulated owners it trades beside. Forty-two percent of its raised $78bn five-year capital plan is transmission, with transmission rate base scheduled to grow from $32bn in 2025 to $55bn in 2030. For a utility in a buildout, the decisive variable is not how much it spends but how long it waits to earn on it.
Entergy waits for a test year
Entergy, the New Orleans utility serving 3 million customers across Arkansas, Louisiana, Mississippi and Texas, spends through the other kind of mechanism. Its $57bn 2026-29 plan runs mostly through state jurisdictions, and Entergy Louisiana filed its formula rate plan evaluation report with regulators on 1 June 2026 for test year 2025 — this year's rates set off last year's costs. The filing sought $149m of rate change, of which only $15m came through the base plan; riders for transmission and distribution carried $36m each and market-based recovery $40m.
The plan itself has to be renewed. "Yeah, I think that we have a long history of extending Formula Rate Plans within Louisiana," chairman and chief executive Drew Marsh told analysts on the July 29 call. "Our expectation is that we would probably be able to extend."
In the meantime the gap is funded with shares. Entergy's June quarter grew revenue 5.9% to $3.524bn and net income 3.4%, yet diluted earnings came to $1.03 a share against $1.05, because the diluted count rose 4.6% to 466.3m. Management widened its 2026 dilution drag to $0.20-$0.25 a share from $0.15-$0.20. AEP issues equity too — a $3bn forward transaction in the second quarter, which it says covers all anticipated marketed equity needs for the $78bn plan — but it collects a current return on the largest slice of what the money builds.
Who carries the stranded-cost risk
The protection for existing customers lives in contract terms rather than announced gigawatts. AEP's Ohio data-center tariff, effective 23 July 2025, obliges new loads of 25 MW or more to pay for at least 85% of subscribed capacity whether they use it or not, over a ramp of up to four years plus eight, with an exit fee of three years of minimum charges. Entergy's agreement to serve Meta's Hyperion campus runs 15 years, with Meta covering a substantial portion of roughly $3.2bn of gas-plant cost only if a further 15-year contract is signed; intervenor witnesses argued for 25 years to match the plant's life.
What the quarter's selling earned
Neither company gave the market a reason. AEP raised 2026 operating guidance to $6.25-$6.55 a share and lifted its capital plan; Entergy affirmed its range. Yet the eleven largest regulated electric owners fell an average of about 12.8% in the three months to 2 October while the S&P 500 rose 3.3% — AEP down 13.7%, Entergy down 12.3% — and the Utilities Select Sector SPDR fell 6% in September, its steepest month since 2023. The likelier reading is arithmetic rather than news: the 10-year Treasury yield went through 5% in mid-September and reached 5.28% on 2 October, while allowed returns are fixed by commissions for years. NextEra showed what that costs at the margin, selling $3.75bn of junior subordinated debentures on 22 June at initial fixed rates of 6.000% to 6.625% against the 10.95% return Florida allows its utility through 2029.
So the discount rate explains the direction for both, and the multiples decide the rest. Entergy carries the group's richest forward earnings multiple at 22.9x, against a peer median near 17.3x, and 2.51x book, while delivered per-share earnings go backwards and the rate base it is buying waits on a test year — a de-rating the business has earned. AEP sits at 18.7x forward against 20.5x trailing and 2.02x book, with guidance raised twice and the shortest recovery lag of the two; that part of its decline is harder to attribute to anything the company is doing. One further constraint bounds both plans from upstream: heavy-duty gas turbines from the three dominant makers are sold out into the end of the decade, with reservation slots stretching to 2031 delivery.
Entergy's next Louisiana rates will be set off a 2026 test year, filed next June. AEP's transmission rate resets again on 1 January, trued up and billed with interest, whatever the 10-year yield happens to be doing by then.